
Sentira Launch Could Change The Case For 10x Genomics Stock
- 10x Genomics has launched Sentira Single Cell, a cloud-based agentic AI application that lets researchers analyze Chromium single cell data through natural language, supported by Anthropic's Claude and delivered via 10x Cloud with consumption-based pricing.
- The release of Sentira Single Cell points to 10x Genomics leaning further into AI-driven software and cloud workflows, which may shift its mix toward higher-value analytical tools that sit on top of its existing hardware and consumables base.
- We will now look at how 10x Genomics' investment narrative could be reshaped by this AI powered Sentira Single Cell launch.
10x Genomics Investment Narrative Recap
To own 10x Genomics, you need to believe high complexity single cell and spatial work will keep shifting onto its instruments, consumables and now AI software, even while academic and government budgets stay tight. The biggest near term swing factor is execution on product adoption across Chromium, spatial platforms and Sentira, and the ability to turn that installed base into recurring consumables and cloud usage.
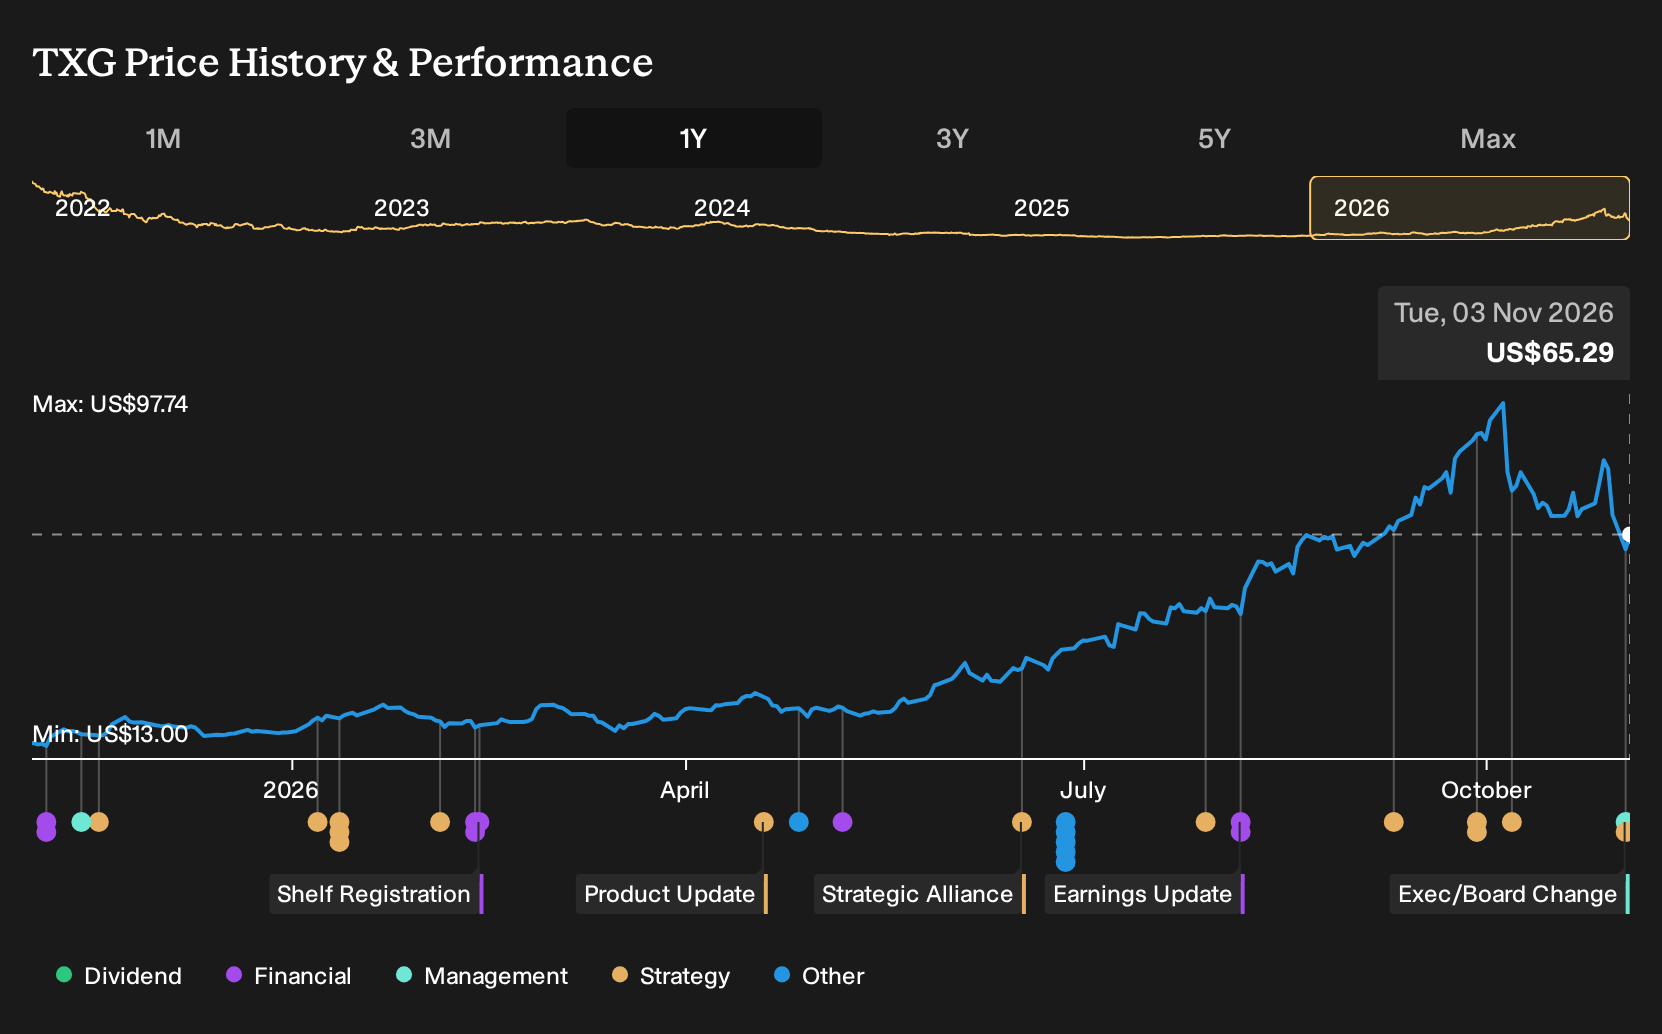
Macro pressure on CapEx, discounting of hardware and lower priced consumables remain the key operational risk, especially since 10x Genomics is still loss making and trades on a rich P/S multiple. The Sentira Single Cell launch and stock volatility around sector moves may not materially change that risk reward skew in the short run.
The announcement that looks most relevant for the Sentira launch is the board refresh. Adding Ansuman Satpathy, who runs immunotherapy and genomics programs at Stanford and has co founded several AI enabled drug discovery companies, suggests 10x Genomics wants deep domain input on data heavy workflows that operate on top of its hardware.
Bringing in Joseph Gilliam, President and COO of Glaukos and a former JPMorgan healthcare banker, also adds a seasoned operator with financing and M&A experience at a time when 10x Genomics is leaning harder into cloud, AI and potentially more software like revenue streams. For investors, execution around cash discipline, pricing power and consumables pull through still matters more than governance headlines, but this board mix aligns with the current product and catalyst focus.
Analysts' current narrative for 10x Genomics points to revenues of US$808.4 million and earnings of US$133.3 million by 2029. This implies 9.4% yearly revenue growth and an earnings swing of about US$208.4 million from a loss of US$75.1 million today.
Uncover why 10x Genomics' fair value indicates a 19% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Not every analyst views 10x Genomics through the same lens. Some of the lowest forecasts already bake in softer AI driven demand, with revenue projections of about US$734.4 million and earnings around US$119.8 million by 2029. Those expectations came before this Sentira and board news, so these views may change meaningfully.
Explore 3 other 10x Genomics fair value estimates, including one that suggests as much as 48% downside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your 10x Genomics research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for 10x Genomics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate 10x Genomics' overall financial health at a glance.
Looking for more 10x Genomics style investment ideas?
If the 10x Genomics story has sharpened your thinking about risk, reward and balance sheets, it can help to widen the lens and compare it with other opportunities using the Simply Wall St Screener.
- For readers who care most about financial resilience and low probability of distress, start with a 30 resilient stocks with low risk scores that keeps downside risk in tighter check.
- If your focus is on quality at a sensible entry point, filter for businesses trading below estimated value through a 35 high quality undervalued stocks that combines fundamentals with pricing discipline.
- Those hunting for under-the-radar prospects may prefer a 19 high quality undiscovered gems that couples strong data with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com