
Is Veracyte (VCYT) Undervalued On New Thyroid And Prostate Test Data?
Veracyte (VCYT) is back in focus after new clinical data and conference activity put its diagnostic tests on center stage. Fresh prostate and thyroid evidence now frames how investors may think about this US$3.9b diagnostics specialist.
Veracyte’s recent data releases have landed on a rising chart, with a 30-day share price return of 9.78% and an 18.64% share price gain year-to-date, while total shareholder return over three years sits at 109.45%. This signals momentum that investors are now reassessing against clinical traction and valuation.
Scan beyond Veracyte and explore other diagnostics-focused opportunities with the curated 34 healthcare AI stocks, which also connect genomics and clinical evidence to real-world decision making.
After a sharp move and the release of new clinical data, Veracyte now trades at a meaningful discount to both intrinsic estimates and analyst targets. The key question is whether this represents a valuation gap or reflects the market pricing in genuine execution risk.
Most Popular Narrative: 16% Undervalued
Veracyte’s most followed narrative pegs fair value at $59.73, above the last close at $50.29. This frames the recent rally as only part of the potential re-rating if the thesis holds.
Pipeline momentum with five major product launches and a pivotal clinical study (OPTIMA) completing in the next 18 months positions Veracyte to further diversify revenue, drive cross-selling, penetrate new markets (e.g., MRD in bladder cancer, Prosigna for breast cancer), and significantly expand addressable markets, supporting long-term topline acceleration.
See why 14 investors see Veracyte as 16% undervalued.
Result: Fair Value of $59.73 (UNDERVALUED)
Still, the Veracyte story can break if Decipher underperforms expectations or if new products, such as Prosigna and MRD, struggle to secure or sustain reimbursement.
Find out about the key risks to this Veracyte narrative.
Another View: Veracyte Through The P/E Lens
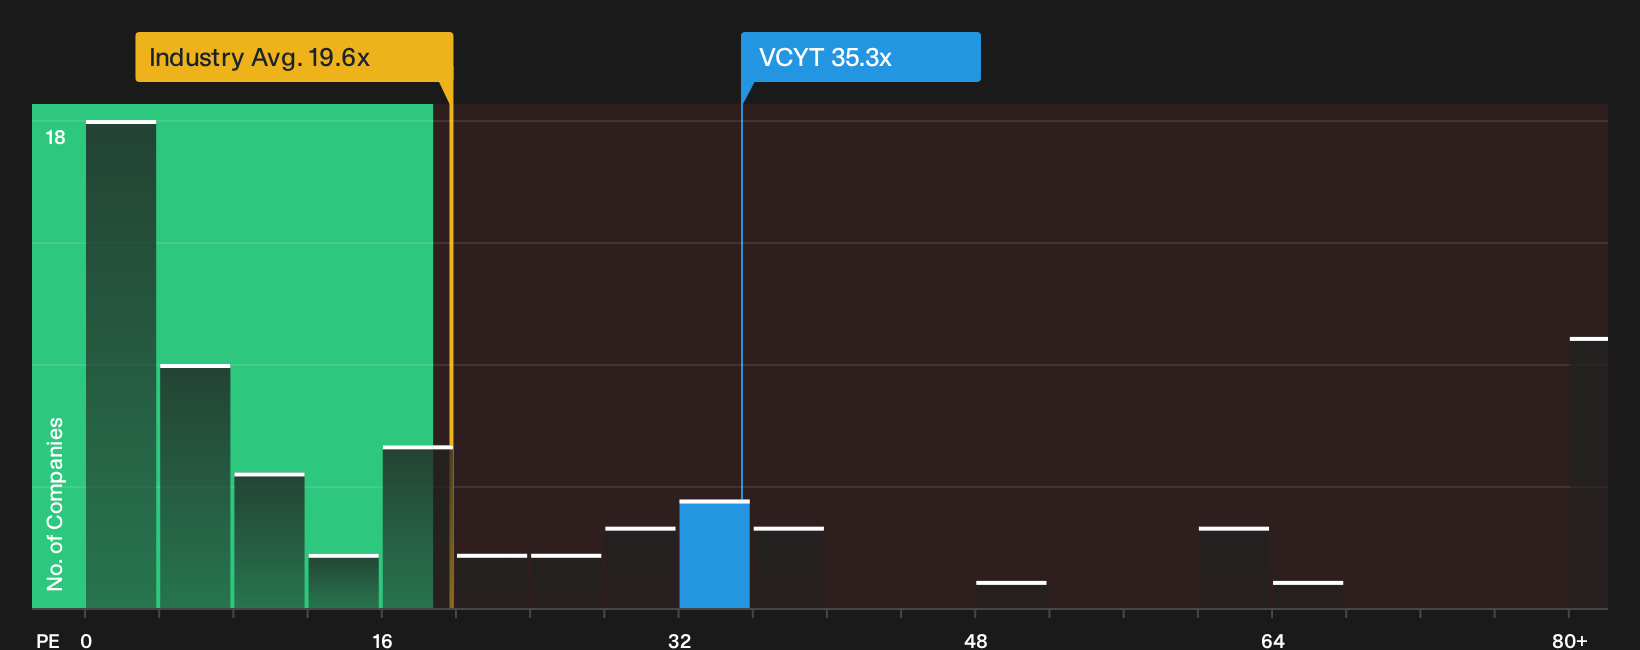
Veracyte screens as undervalued against the SWS fair value estimate, yet its P/E ratio of 35.3x tells a tougher story. That multiple is higher than the US Biotechs industry at 19.2x, the peer average at 34.8x, and the fair ratio of 17.8x, which points to real valuation risk if sentiment cools.
The gap between today’s P/E and the fair ratio suggests investors are already paying up for execution on Decipher and newer assays. The question is whether that premium feels justified once you weigh the clinical progress against reimbursement, competition, and more modest earnings forecasts.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of optimism and concern around Veracyte resonates, do not remain undecided. Review the evidence on 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Veracyte?
If Veracyte has sharpened your thinking, now is the moment to widen your watchlist with a few focused screens that surface very different types of opportunities.
- Target potential mispricing by reviewing quality companies that screen as attractively valued through the 35 high quality undervalued stocks.
- Strengthen your defense by filtering for financially resilient businesses using the 30 resilient stocks with low risk scores.
- Get early exposure to potential future leaders by scanning the 19 high quality undiscovered gems before they attract broader attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com