
Is Palo Alto Networks (PANW) Below Fair Value On Its NodeZero Cortex XSOAR Integration?
Palo Alto Networks (PANW) is back in focus after Horizon3 released a certified integration that feeds its NodeZero penetration testing findings directly into Cortex XSOAR as incidents on the Cortex Marketplace.
Recent trading has been choppy for Palo Alto Networks, with the share price down 12.82% over the past week and 13.15% over 30 days, even as integrations like NodeZero and Guardz highlight deeper adoption of its security platforms and upcoming fiscal Q1 2027 results refocus attention on fundamentals. Despite this pullback from a recent high, the 90 day share price return of 3.44% lower and the year to date share price return of 95.24% still point to strong momentum over 2026. Multi year total shareholder returns of 63.25% over one year, 189.33% over three years and 310.13% over five years underline how long term holders have been rewarded.
Scan how Palo Alto Networks compares with other cybersecurity names reacting to the same headlines by reviewing the hand picked 30 resilient stocks with low risk scores in this space.
Palo Alto Networks now trades well below its recent highs, even as integrations and upcoming results keep it in the spotlight. Is this pullback enough of a reset, or does patience on price still make more sense?
Most Popular Narrative: 12% Undervalued
Palo Alto Networks closed at $350.20 against a widely followed fair value estimate of $396.12, which frames the current pullback as a discount that relies heavily on how new software pillars perform over time.
The main requirement is that Palo Alto Networks continues to turn platformization, recent acquisitions such as Idira and Chronosphere, and AI-driven offerings like Prisma AIRS and Unit 42 Frontier AI Defense into durable multi-billion dollar ARR pillars, while avoiding margin pressure from higher cloud and hardware costs or stock-based compensation.
See why 391 investors see Palo Alto Networks as 12% undervalued.
Result: Fair Value of $396.12 (UNDERVALUED)
Still, the Palo Alto Networks thesis leans heavily on the clean integration of Idira and Chronosphere and on keeping gross margins steady as cloud and hardware costs rise.
Find out about the key risks to this Palo Alto Networks narrative.
Another View: Palo Alto Networks Through The Sales Multiple Lens
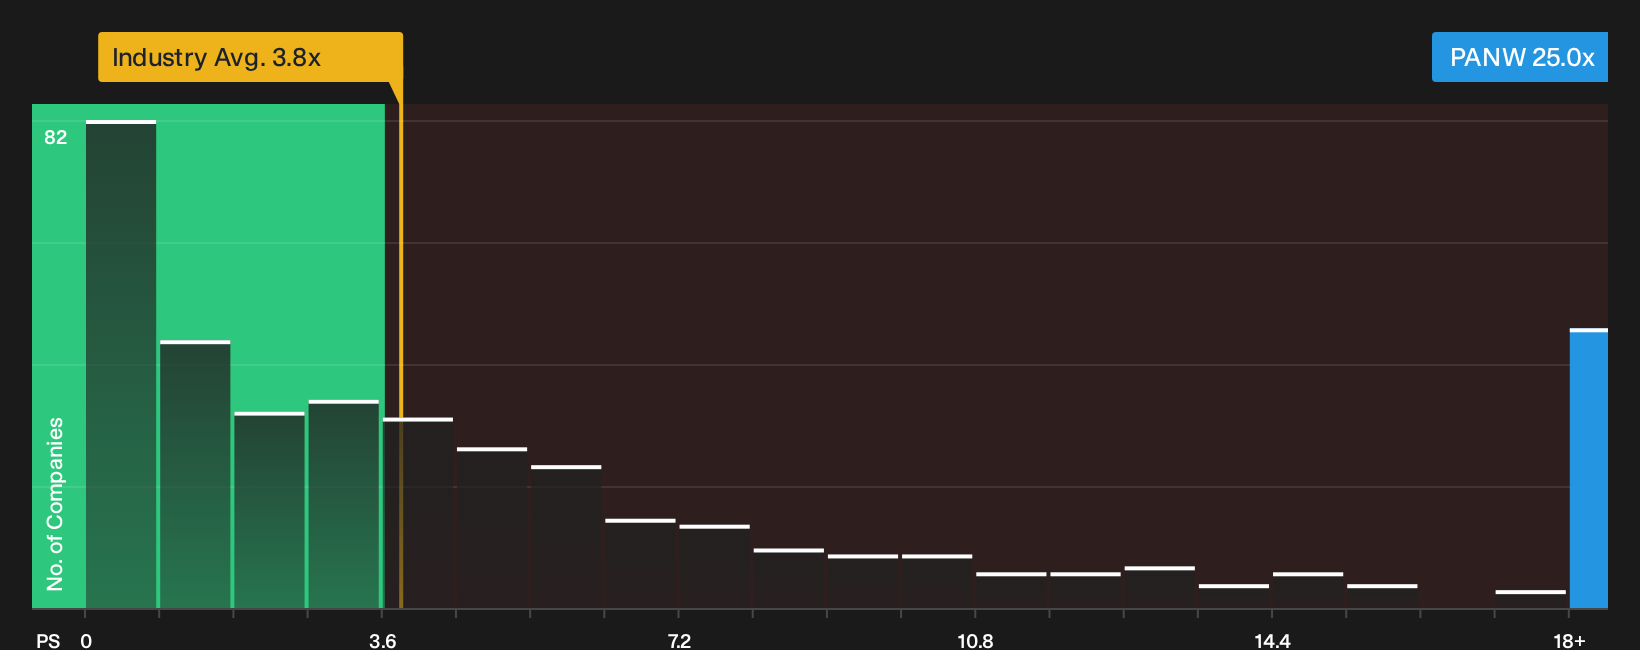
On the narrative fair value, Palo Alto Networks looks about 12% below the $396.12 estimate. On simple sales math, the picture is harsher. The stock trades on a P/S of 25x versus 17.8x for peers and 3.8x for the broader US Software group, while the fair ratio is 15.1x. That gap suggests investors are paying a premium that could magnify any disappointment, so the key question is whether you believe Palo Alto Networks has earned such a rich revenue tag yet.
See what the numbers say about this price in more detail in our valuation breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and sentiment only go so far, especially when Palo Alto Networks carries both flagged issues and clear bright spots in the data. Weigh those trade offs for yourself by starting with the 1 key reward and 3 important warning signs.
Looking For More Ideas Beyond Palo Alto Networks?
Do not stop with one cybersecurity giant. The best opportunities often appear where fewer people are looking and where the risk reward trade off is more compelling.
- Target resilient balance sheets by scanning a curated list of solid balance sheet and fundamentals (23 results) that surfaces companies with room to absorb shocks without stretching their finances.
- Hunt for mispriced quality by checking a focused 35 high quality undervalued stocks that highlights businesses where fundamentals and current prices are out of sync.
- Spot potential early stage outliers through a hand picked 19 high quality undiscovered gems that filters for strong underlying metrics before wider attention arrives.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com