
VinFast Auto (VFS) Stock Could Be Above Fair Value Despite Investor Investigation
VinFast Auto has put investors through a rough ride over the longer term, and that kind of history naturally raises a question about whether the current share price lines up with the sales the business is generating. With the stock now trading around US$3.21, the issue is less about short term swings and more about what that tag implies about the value of its revenue base.
- The share price has fallen about 67.0% over 5 years, which puts the focus squarely on whether the valuation still matches what the company delivers in sales.
- A recent investor investigation tied to rising operating losses and weaker gross profit margins points to pressure on how efficiently VinFast Auto can turn each dollar of revenue into sustainable value.
- The analysts covering VinFast Auto have run their own numbers. See what analysts think VinFast Auto's shares could be worth.
For investors, the debate is whether VinFast Auto's current price is adequately supported by the level and quality of its sales today.
If you are weighing whether VinFast Auto's current tag of US$3.21 is fair for its sales profile, it can help to compare that context with 35 high quality undervalued stocks.
Is VinFast Auto Getting Expensive on Sales?
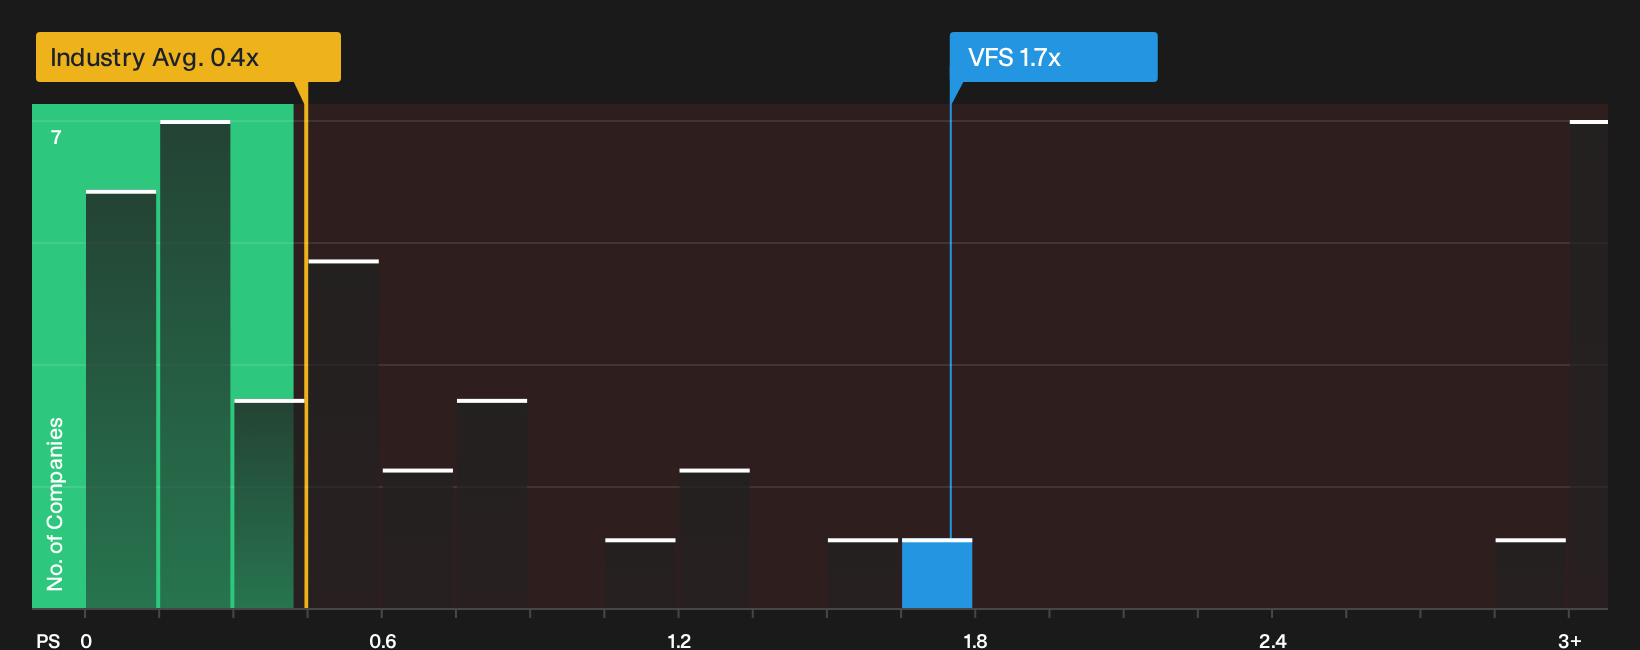
P/S is often a better yardstick for VinFast Auto because the group is still reporting free cash flow losses, so earnings-based measures do not tell you much about what investors are paying for each dollar of sales. On this metric, the stock trades on roughly 1.7x P/S, compared with an Auto industry average around 0.4x and a peer group nearer 1.2x.
That gap looks wide. The Fair Ratio model, which adjusts for VinFast Auto's margins, risk profile and size, points to a much lower multiple than the current 1.7x. The very large gap suggests the framework is heavily penalising the business for its cash burn and revenue quality rather than offering a precise target. Because the recent Pomerantz investigation highlights pressure on losses and gross margin, this richer P/S tag means you are paying a premium valuation for a company that is still working to stabilise its economics. Explore the numbers behind VinFast Auto's P/S valuation.
The VinFast Auto Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the VinFast Auto valuation puzzle leaves off by spelling out which combinations of future growth, margins and earnings would need to hold for the shares to look meaningfully higher or lower than today’s level, and they sit on the platform’s Community page. Each one treats fair value as a thesis about VinFast Auto's business that you can track over time rather than a single frozen snapshot.
One of the top community narratives on VinFast Auto: 42% undervalued
"The main thing that has to go right is VinFast Auto successfully executing its shift to an asset light model and GSM ecosystem partnership…"
Discover why this Narrative puts VinFast Auto at 42% undervalued.
One more VinFast Auto check that belongs beside the price tag
The last missing piece is who is actually steering VinFast Auto, how their incentives are wired, and whether that pay structure truly aligns with your interests as a shareholder. See who runs VinFast Auto and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com