
Protagonist Therapeutics (PTGX) Stock Looks Pricey Following Its 7x Three Year Run
Protagonist Therapeutics has delivered a very large 3 year share price gain, which puts a spotlight on whether the current valuation is still grounded in what the business is earning today. With the stock now trading around US$140.24, the question for investors is how closely that price lines up with the company’s earnings power.
- The share price has surged roughly 7x over the past 3 years. This makes any gap between earnings and market expectations far more consequential for new buyers and existing holders.
- Recent coverage points to strong earnings and sales momentum alongside progress in its clinical pipeline. This can support expectations for higher future profitability and influence how much investors are willing to pay for each dollar of earnings.
- The analysts covering Protagonist Therapeutics have run their own numbers. See what analysts think Protagonist Therapeutics's shares could be worth.
The issue now is whether Protagonist Therapeutics' recent price level is justified by its earnings when set against the Fair Ratio benchmark.
If you want to stress test this same earnings based valuation question beyond Protagonist Therapeutics, compare it with 35 high quality undervalued stocks
Does Protagonist Therapeutics Look Pricey on Earnings?
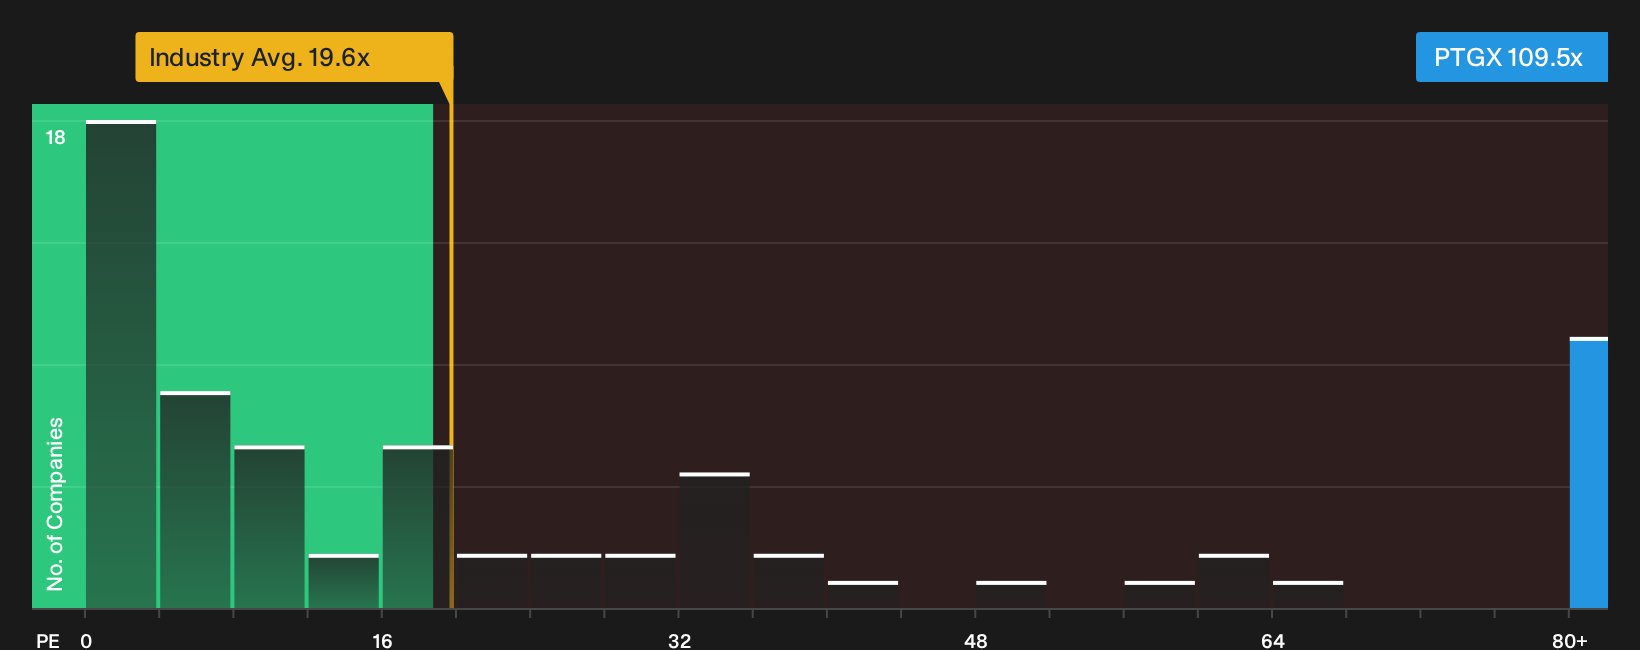
The P/E ratio is a useful metric for Protagonist Therapeutics because earnings are now a meaningful part of how the stock is being judged rather than just the clinical story. On this measure, the shares trade on about 109.5x earnings, which is far above the wider Biotechs sector average of roughly 19.6x and higher than the peer group on about 93.9x.
The Fair Ratio model, which looks at factors like growth potential, profitability profile, industry backdrop and risk, points to a much lower multiple and flags Protagonist Therapeutics as overvalued on this framework. Because that gap is so wide, the model is likely putting significant weight on the company’s risk profile and the quality and durability of its earnings rather than offering a precise target P/E. Recent commentary about strong growth momentum and a potential breakout helps explain why investors are willing to pay such a rich earnings multiple, but it also raises the bar for what the business must deliver to keep justifying this price. Explore the numbers behind Protagonist Therapeutics's P/E valuation.
The Protagonist Therapeutics Narrative: What Would Justify Today's Price?
Narratives for Protagonist Therapeutics pick up exactly where this valuation puzzle leaves you. They spell out which paths for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each scenario focuses less on a single P/E or model output and more on the underlying assumptions behind its fair value so you can later compare those expectations with the actual results reported on Simply Wall St's Community page.
One of the top community narratives on Protagonist Therapeutics: 20% undervalued
"The current valuation suggests the market is assigning limited value to Protagonist Therapeutics beyond existing ICOTYDE and MIMRYLO economics..."
Discover why this Narrative puts Protagonist Therapeutics at 20% undervalued.
One more angle on Protagonist Therapeutics that could change how you see this price
Everything here has focused on what Protagonist Therapeutics looks like today. Analyst models outline where they expect the business to be in a few years and offer a different lens on this valuation. Explore where analysts expect Protagonist Therapeutics to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com