
Is Avnet (AVT) A Bargain After Its Latest Earnings Beat?
Avnet (AVT) has just posted quarterly numbers that are hard to ignore, with revenue up 47.7% and earnings per share rising by a very large multiple compared with a year earlier.
Avnet's share price tells a more mixed story in the short term, with a 1-month share price return down 16.44% and a 7-day share price return down 5.17%, even after a 2.89% gain in the last session to US$88.73. Over a longer stretch, momentum has been positive, with a year-to-date share price return of 79.83% and a 1-year total shareholder return of 88.70%, extending to 109.37% over three years and 155.02% over five years.
Scan how Avnet compares with handpicked peers by reviewing 53 AI infrastructure stocks, which could be next in line for sharp moves on the back of AI hardware and systems demand.
Avnet now trades below the average analyst price target despite that sharp pullback. Is the discount compensation for real risks, or a misread of what this latest quarter says about the business?
Most Popular Narrative: 16% Undervalued
Against the current Avnet share price of $88.73, the most followed narrative framework works off a fair value of $106.25, which implies a meaningful valuation gap while anchoring that view to specific earnings and margin assumptions.
Improving operating leverage and capital efficiency are now more visible, with adjusted operating income reported to be growing about 2.6x faster than sales, SG&A as a percentage of gross profit trending toward a sub 60% target and return on working capital reaching 19%, which together create room for further operating margin expansion and support for adjusted EPS growth.
See why 11 investors see Avnet as 16% undervalued.
The narrative leans on a discount rate of 9.59% and ties the $106.25 fair value to a path where analysts see Avnet lifting profit margins from 1.2% to 3.7%, growing revenue to $37.1b and reaching earnings of $1.4b. It treats that earnings path and an 8.6x P/E on 2029 forecasts as the combination that could justify today’s implied upside versus the current share price.
That leaves investors with a clear scoreboard: last close at $88.73, consensus fair value at $106.25, and a narrative that depends heavily on Avnet converting AI linked demand, supply tightness and efficiency gains into higher returns on working capital over time.
Result: Fair Value of $106.25 (UNDERVALUED)
Still, the Avnet narrative can crack if pressure on gross margins from Asia and memory exposure proves sticky, or if recent share price strength proves ahead of fundamentals.
Find out about the key risks to this Avnet narrative.
Another Take On Avnet’s Valuation
The narrative fair value for Avnet sits at $106.25, yet the SWS DCF model points to a future cash flow value closer to $23.60. That gap frames the current $88.73 price as rich on a pure cash flow lens and raises a simple question: Which story do you trust more, the cash or the earnings path?
Look into how the SWS DCF model arrives at its fair value.
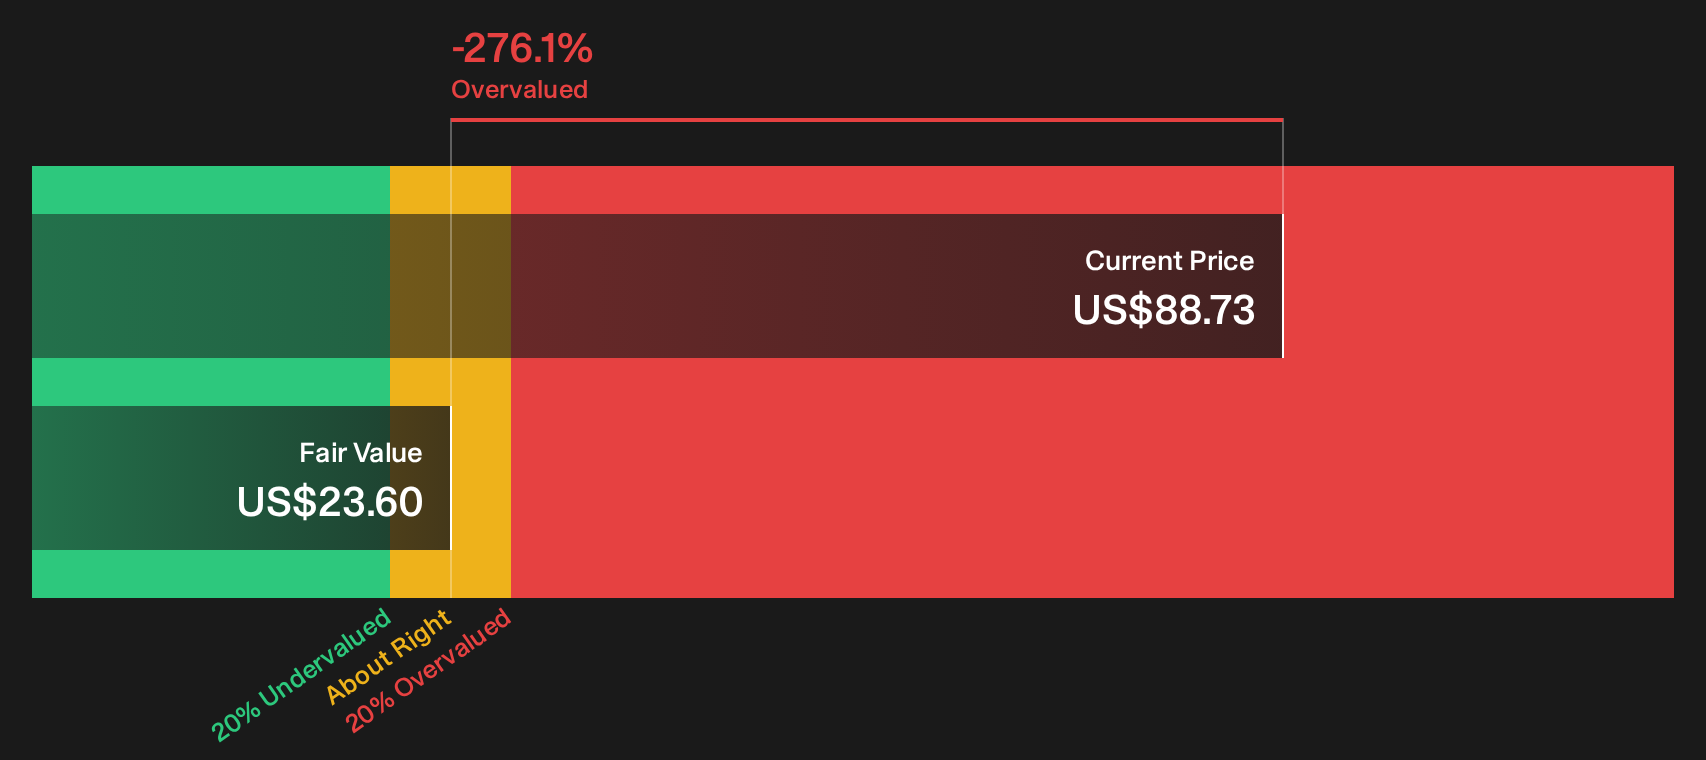
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Avnet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages in the Avnet story so far, with rapid earnings and cash flow gaps presenting both risks and bright spots now on the table. Move quickly, review the underlying numbers yourself, then pressure test that view against the balance of 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Avnet?
If Avnet has sharpened your focus, do not stop here. Broaden your watchlist and let fresh ideas challenge your convictions before the next move arrives.
- Target steady compounding and stress test your watchlist against 30 resilient stocks with low risk scores that score well on resilience and lower risk profiles.
- Hunt for quality at a discount by scanning 19 high quality undiscovered gems where fundamentals and price have not fully met yet.
- Build a sturdier core by reviewing a list of solid balance sheet and fundamentals (23 results) that can better handle shocks while you focus on the upside.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com