
How Investors Are Reacting To Andersons (ANDE) Record Quarterly Earnings
- The Andersons, Inc. recently reported record third quarter net income, with Renewables and Agribusiness both delivering strong segment results supported by efficient operations, higher co product values, and active grain merchandising.
- Management is also pushing ahead with growth projects such as the Port of Houston soybean meal export facility and an Indiana ethanol de bottlenecking initiative, which together indicate a focus on capacity, asset utilization, and more efficient production.
- We will now look at how Andersons' record third quarter earnings, especially in Renewables, could influence the broader investment narrative.
Scan for other agribusiness and commodity players showing similar earnings momentum and capacity build outs using our curated 19 high quality undiscovered gems.
Andersons Investment Narrative Recap
To own Andersons, you need to believe the business can keep turning its agribusiness and renewables footprint into steady cash flow while riding through grain and fertilizer cycles. The short term story still leans on executing current projects, such as the Port of Houston export facility and ethanol debottlenecking, and on maintaining recent operational efficiency.
The human resources restructuring and elimination of the Chief Human Resources Officer role looks more like an internal realignment than a driver of earnings. It does not obviously change the key near term swing factors, such as ethanol margins, grain merchandising conditions, or fertilizer demand, which remain the primary operating risks.
The most relevant recent development to consider alongside this HR change is Andersons pushing ahead with decarbonization and capacity work at its ethanol operations, supported by 45Z tax credits. Those investments, together with 100% ownership of ethanol plants, tie directly to the main earnings catalyst, which is how much value the renewables segment can deliver.
Viewed together, an internal reshuffle in human resources and ongoing project execution keep attention on a familiar question for investors: Can Andersons translate project spend, tax credits, and export capacity into durable returns while managing grain oversupply, fertilizer softness, and competition from Brazilian ethanol without eroding segment profitability?
For Andersons, analysts currently factor in yearly revenue growth of 5.9%, with earnings today at $177.3 million and a consensus forecast of $264.5 million by 2029. This implies an earnings increase of about $87.2 million and total revenues of $13.0b in that same year.
Uncover why Andersons' fair value indicates a 41% potential upside to its current price that could narrow quickly.
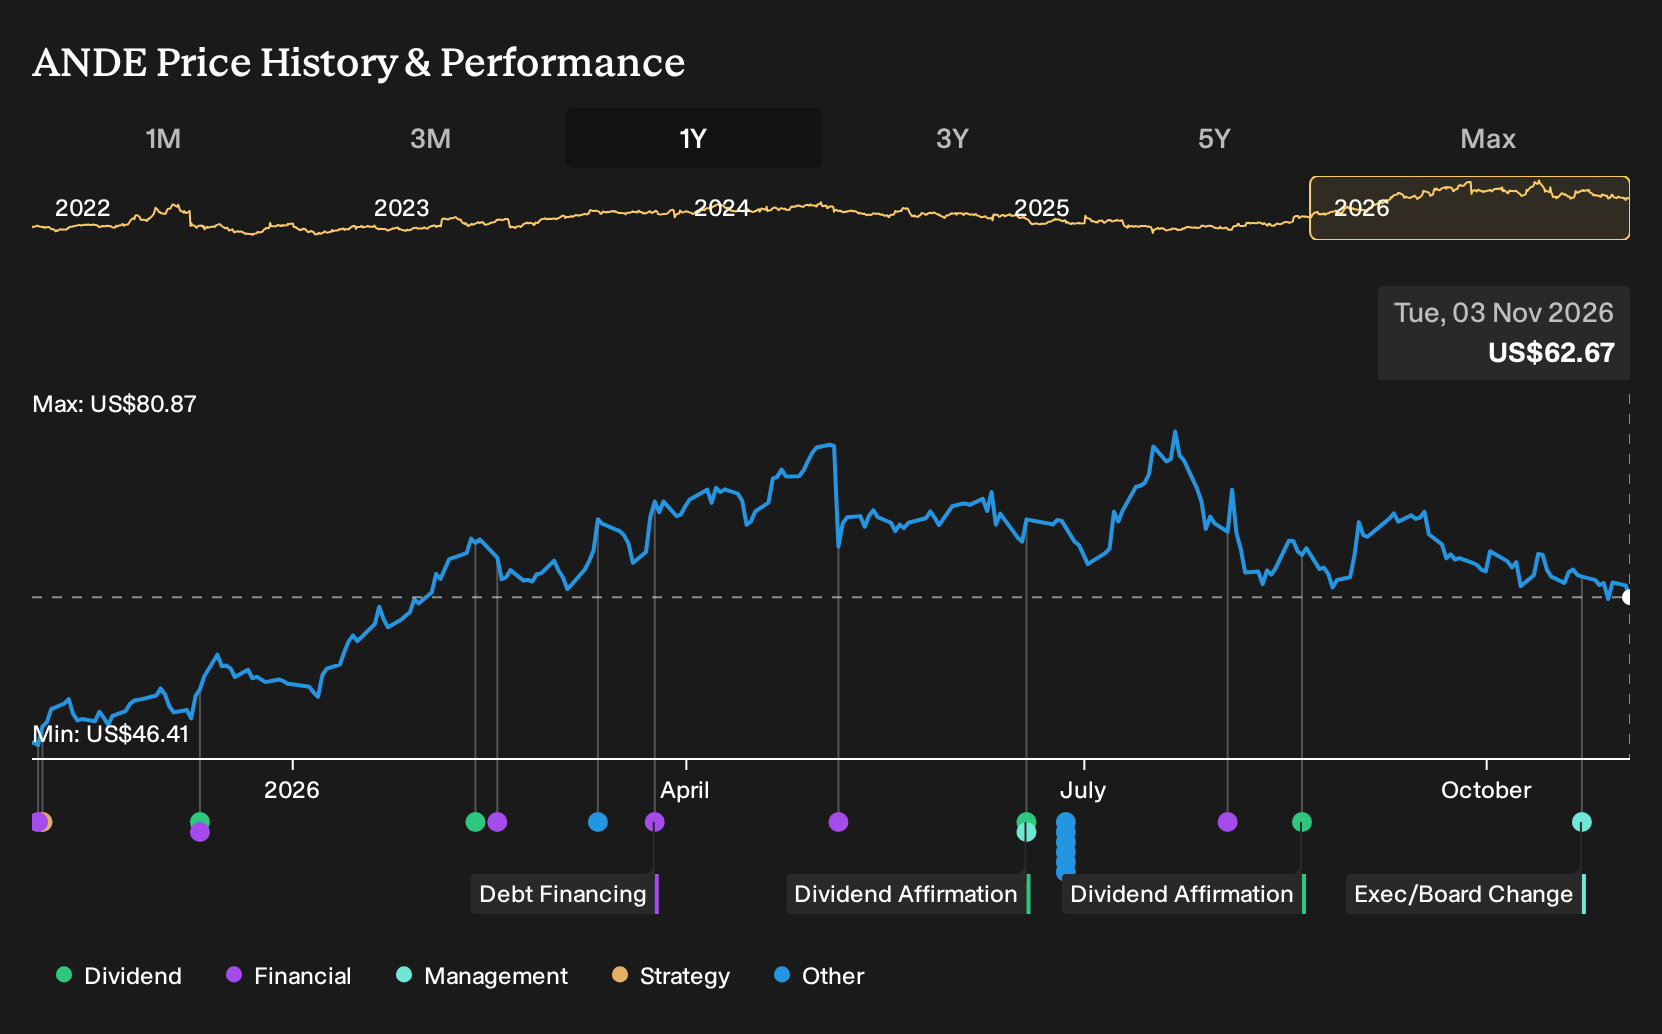
Exploring Other Perspectives
One alternate view on Andersons puts far more weight on the ethanol decarbonization catalyst. Bullish analysts, working off pre news numbers, were already modeling revenue reaching about $13.6b and earnings of roughly $287.7 million by 2029. You can read that as a much more optimistic story that may shift again after this HR change and the record quarter.
Explore another Andersons fair value estimate, including one that suggests as much as 1162% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Andersons research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Andersons. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Andersons' overall financial health at a glance.
Looking for more investment ideas beyond Andersons?
Once you have a view on Andersons, it can help to compare that thesis with other companies that share similar qualities or offer a very different risk profile. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that actually fits how you like to invest.
- If you want potential value with quality fundamentals, start by reviewing our curated 35 high quality undervalued stocks that fit a blend of cash flow strength and balance sheet resilience.
- For investors who prefer staying on the conservative side of the risk spectrum, scan through a 30 resilient stocks with low risk scores that score well on stability metrics and financial robustness.
- When you are hunting for lesser known opportunities, widen your research with a 19 high quality undiscovered gems that pair strong fundamentals with limited current market attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com