
Is Toyoda Gosei (TSE:7282) Cheap As Buyback Dividend And Earnings Reset Valuation?
Toyoda Gosei (TSE:7282) just packed a lot into one day. A new share buyback, a higher interim dividend, fresh earnings figures, and forward guidance now give investors more concrete numbers to work with.
Toyoda Gosei’s latest announcements land after a mixed stretch in the market, with the share price up 23.82% year to date but down 5.09% over the past month. Meanwhile, a 34.23% 1-year total shareholder return hints that long-term momentum has held up better than recent trading suggests.
See how Toyoda Gosei’s buyback and dividend move compares with other potential opportunities by reviewing our hand picked 19 high quality undervalued stocks that score well on quality and pricing.
Toyoda Gosei has already delivered a strong 1-year run, and the latest buyback, dividend lift, and guidance outline a fresh set of numbers. Has most of the upside been realised, or does valuation still leave room?
Preferred P/E of 9.5x: Is it justified?
On simple earnings maths, Toyoda Gosei trades on a P/E of 9.5x, which lines up with the wider JP Auto Components group yet still implies a discount to what some models suggest the ratio could be.
The P/E multiple compares the current share price with earnings per share and gives you a quick sense of how much investors are paying for each unit of profit. For a parts supplier like Toyoda Gosei, where earnings are a key focus, this metric is a common shorthand for how the market is weighing current profitability against expectations.
Here the picture is mixed. The stock is described as expensive relative to the broader JP Auto Components industry at 9.5x because it is not below that sector average. However, it is also flagged as good value versus a peer group on a higher 19.5x average P/E. Against an estimated fair P/E of 11.6x, the current ratio of 9.5x also sits lower, which suggests the multiple may have scope to rise if the market eventually prices Toyoda Gosei closer to that fair level.
Explore the SWS fair ratio for Toyoda Gosei.
Result: Price-to-earnings of 9.5x (UNDERVALUED)
Still, the narrative can crack if Toyoda Gosei’s recent revenue and net income growth rates of 3.83% and 6.60% fade, or if auto demand weakens globally.
Find out about the key risks to this Toyoda Gosei narrative.
Another view on Toyoda Gosei’s value
The P/E story presents Toyoda Gosei as only mildly cheap, yet the SWS DCF model points to something far more extreme. At ¥997, the share price is well below an estimated future cash flow value of ¥2,229.5, which indicates a much deeper undervaluation using this approach.
If that gap narrows, holders would see returns driven by more than just earnings progress. Alternatively, the discount might indicate that the market perceives real long term risk that the model does not fully capture. Which side of that debate do you think is closer to reality?
Look into how the SWS DCF model arrives at its fair value.
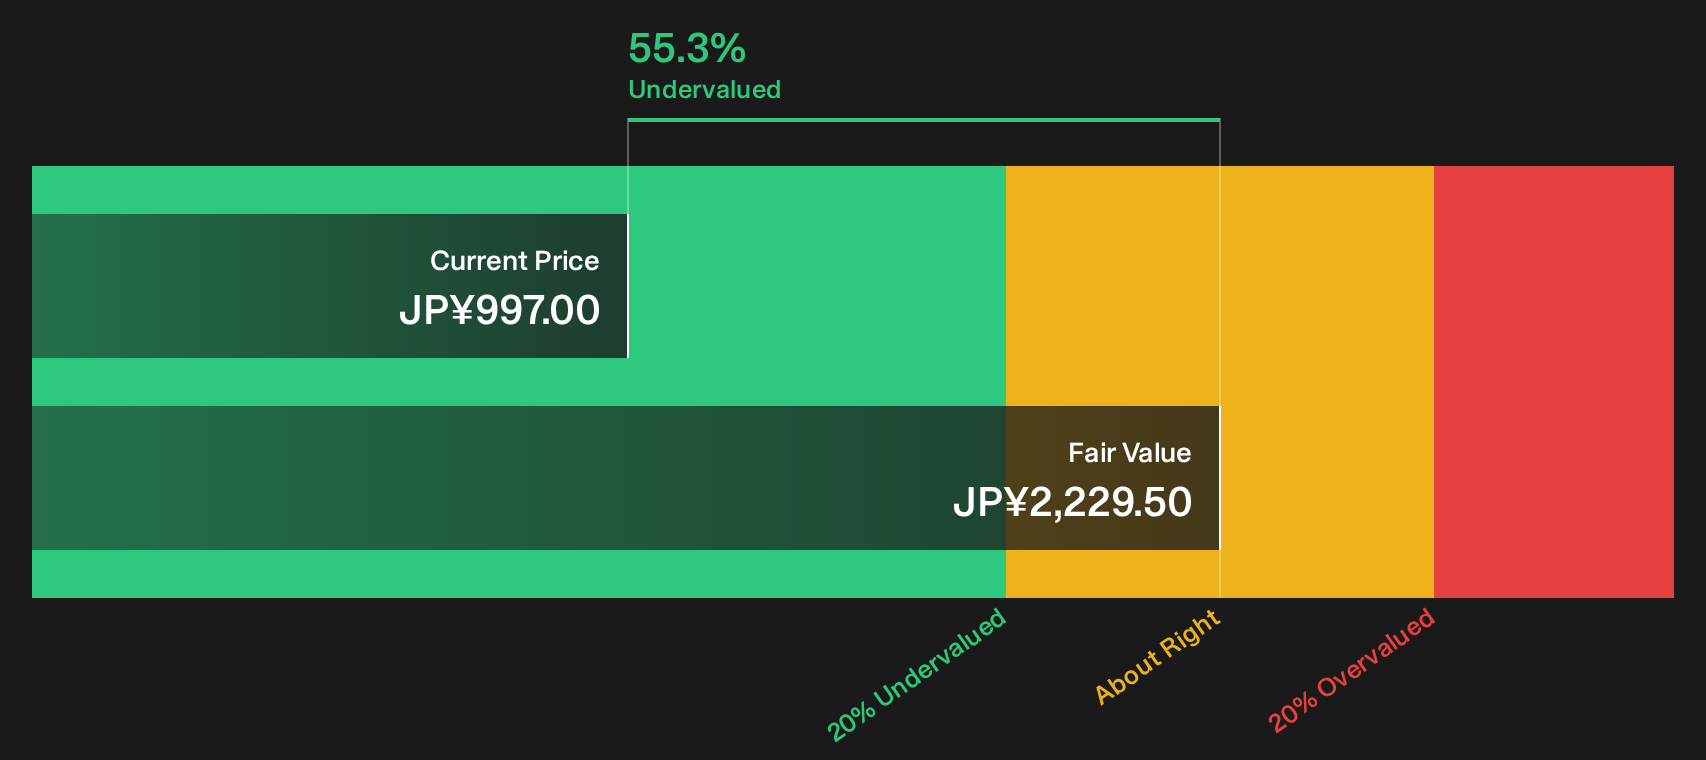
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Toyoda Gosei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 19 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or quiet opportunity, either way Toyoda Gosei gives you enough data today to form your own view if you move quickly. To weigh both the concerns and the positives side by side, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Toyoda Gosei?
Do not stop with Toyoda Gosei. Use the Simply Wall Street Screener to quickly surface fresh opportunities that fit the kind of portfolio you want to build.
- Target stability first by scanning a list of solid balance sheet and fundamentals (22 results) that can help you focus on companies with stronger fundamentals when markets feel unpredictable.
- Hunt for mispriced quality by reviewing a curated 74 high quality undiscovered gems before other investors start paying closer attention.
- Dial down volatility risk by filtering a 22 resilient stocks with low risk scores so you are not leaving potential resilience on the table.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com