
Is Zillow Group (ZG) Stock Now A Bargain Or Fully Priced?
Zillow Group shares have retreated sharply over the past year, which puts fresh focus on a basic question for anyone following the stock. Is the current US$31.35 price adequately supported by the earnings the business is generating today and what those profits may realistically support over time?
- The stock is down 55.2% over the past 12 months, which turns the spotlight squarely onto whether the earnings profile now lines up with the lower market value.
- The US$212.5 million settlement over the former home flipping unit and the ongoing build out of services such as Zillow Home Loans can affect how much profit ultimately flows through to shareholders and when.
- The analysts covering Zillow Group have run their own numbers. See what analysts think Zillow Group's shares could be worth.
The stock's next move may depend on whether Zillow Group's current earnings are enough to justify the valuation that last closed at US$31.35 per share.
If you are weighing Zillow Group against other opportunities built on earnings power, a side by side view of companies in the same zone can help, starting with 35 high quality undervalued stocks
Has Zillow Group Run Too Far on Earnings?
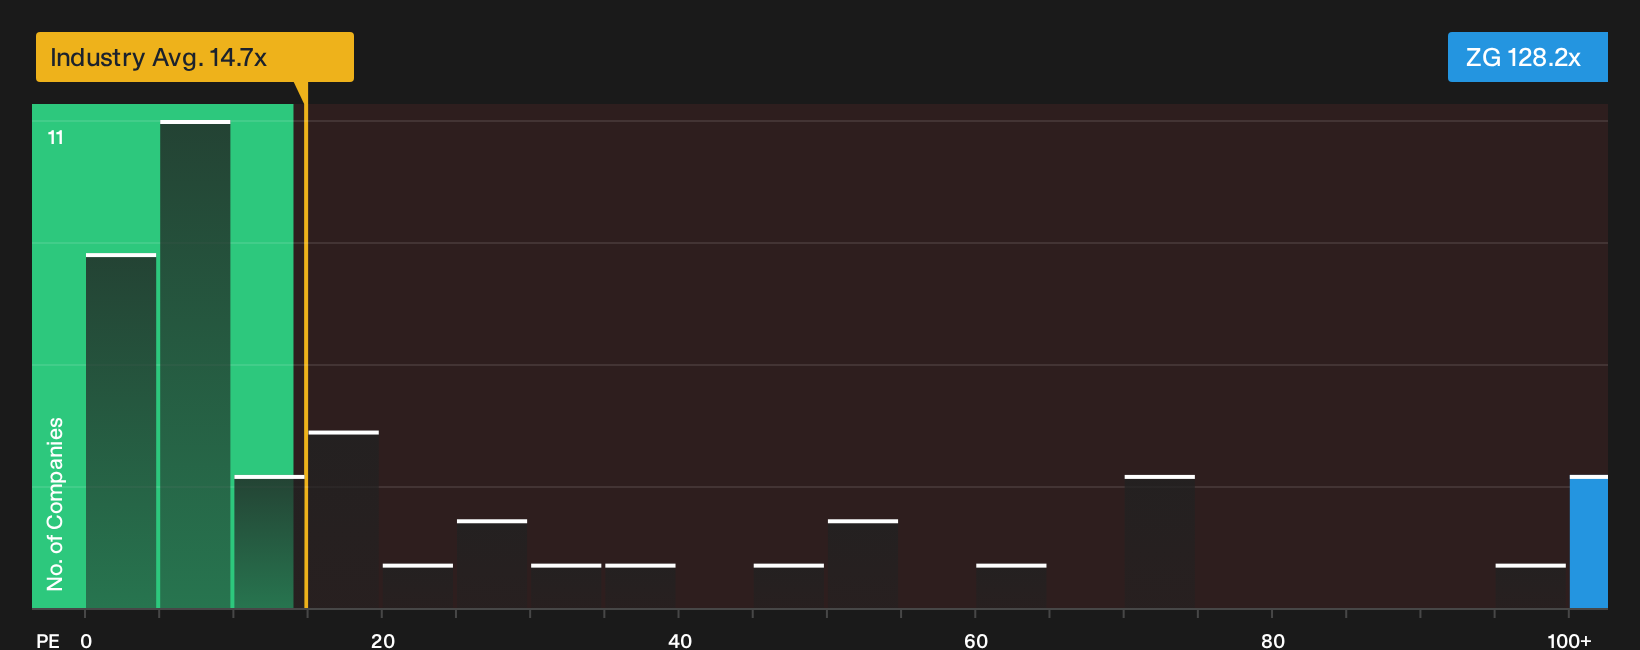
The P/E ratio is a useful shorthand for Zillow Group because earnings ultimately have to carry the current share price. On this yardstick, the stock trades at about 128.2x earnings, compared with roughly 14.7x for the wider real estate sector and around 51.2x for closer peers. That is a hefty step up from both reference points, so you are paying far more for each dollar of current profit than the typical real estate stock.
The internal fair P/E that blends Zillow Group's growth assumptions, margins, size and risk profile sits well below the market multiple, and the gap is so wide that the model effectively treats the shares as very expensive on an earnings basis rather than pointing to a precise fair value target. Because the recent US$212.5 million settlement relates to a past business line and not the current platform focus, the market multiple still asks you to accept a rich price for the earnings that remain. Explore the numbers behind Zillow Group's P/E valuation.
The Zillow Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Zillow Group's valuation puzzle leaves off by spelling out the future growth, margin and earnings paths that would need to play out for the share price to look materially higher or lower than it does today, all housed on the Community page. Each one sets out a fair value argument as something you can track over time, so you can see how the underlying business case holds up as new information comes through.
Community views on Zillow Group split between those who see extra upside and those who think the stock already prices in most of the story.
Bull case: 31% undervalued
"The accelerated digital transformation of real estate, combined with Zillow's leading traffic, engagement, and product innovation, positions the company to expand market share and drive higher user conversion rates…"
Discover why this Narrative puts Zillow Group at 31% undervalued.
Bear case: roughly fairly valued
"Although the shift to the Preferred, success based model currently lifts revenue per connection, the plan to route more than 75% of connections through this structure by the end of 2026 introduces a 400% to 600% basis point For Sale revenue headwind…"
Explore why this Narrative puts Zillow Group at roughly fairly valued.
One more angle on Zillow Group that could change how you see the stock
Earnings multiples tell you what the market is willing to pay today, but analyst projections sketch out where they think this business might be a few years down the road. Explore where analysts expect Zillow Group to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com