
Is Cactus (WHD) Priced Too Richly For Its Earnings Story?
Cactus has had a strong multi year run, and the latest stretch of earnings news keeps the story in focus. With the share price recently at $62.03, the question for you is whether that level can be explained by what the business is currently earning.
- Over the past 5 years, Cactus has delivered a total return of 49.5%, which puts real weight on whether those gains line up with its underlying earnings power.
- Recent earnings and cash generation, helped by strong demand for its Spoolable Technologies products and a growing international footprint, may support expectations for how efficiently Cactus can turn its asset base into future profit.
- There is a second opinion on Cactus worth weighing. See what analysts think Cactus's shares could be worth.
The issue now is whether the stock's present valuation is justified by the earnings that Cactus is generating today.
If you want more ideas like Cactus, a focused stock screen can be a useful next step, especially one that highlights 35 high quality undervalued stocks.
Has Cactus Run Too Far on Earnings?
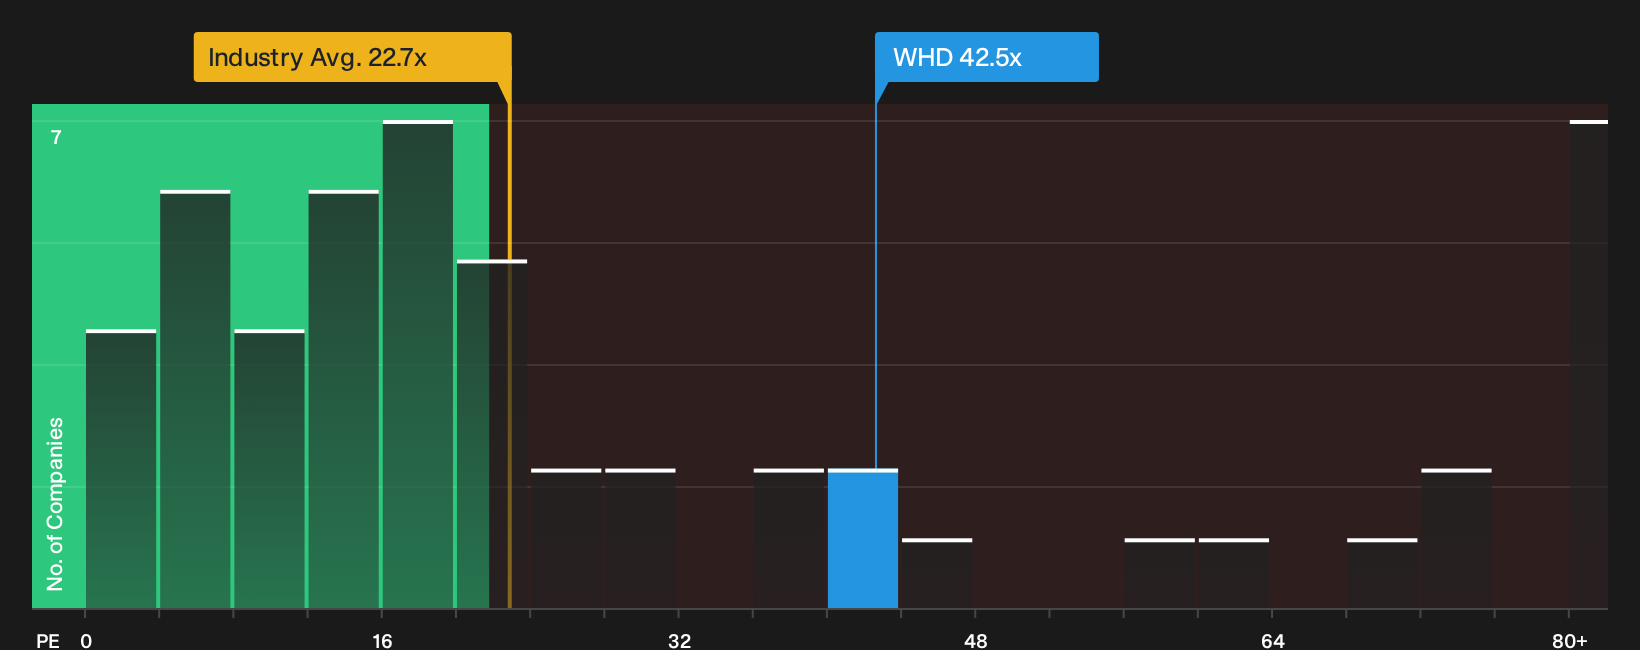
The P/E ratio fits Cactus well because earnings are a central part of how investors seem to be framing the story after its recent Q3 2026 results. On this lens, the stock trades on about 42.5x, compared with an Energy Services sector average of roughly 22.7x and a peer group closer to 25.9x. That is a sizeable premium to both the wider industry and more direct comparables.
The valuation model that blends Cactus specific growth, margins, size and risk points to a lower P/E than where the shares change hands today, so the current multiple screens as overvalued on this framework. Because the latest quarter brought solid earnings and a new Middle East facility plan, the elevated P/E suggests investors are already paying up heavily for that expansion story and for future execution. Explore the numbers behind Cactus's P/E valuation.
The Cactus Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take the valuation puzzle around Cactus' P/E and turn it into a set of explicit assumptions about future growth, profitability and earnings power, all hosted on the Community page. Each scenario ties a fair value estimate to a particular storyline about Cactus' potential catalysts and key risks, allowing you to track over time which version of events seems closest to reality.
Community views on Cactus are split between investors who see upside in international execution and synergies and those focused on backlog risk and margin pressure.
Bull case: 19% undervalued
"Vietnam manufacturing is moving from concept to tangible output as Cactus ramps shipments that face a 50% tariff instead of the 75% tariff on China imports..."
Discover why this Narrative puts Cactus at 19% undervalued.
Bear case: 9% overvalued
"Reliance on tariff mitigation, supplier concessions and customer acceptance of surcharges to sustain a 31% to 33% Pressure Control margin range increases vulnerability if trade policies shift or partners push back..."
Explore why this Narrative puts Cactus at 9% overvalued.
Cactus valuation leaves one key angle unresolved
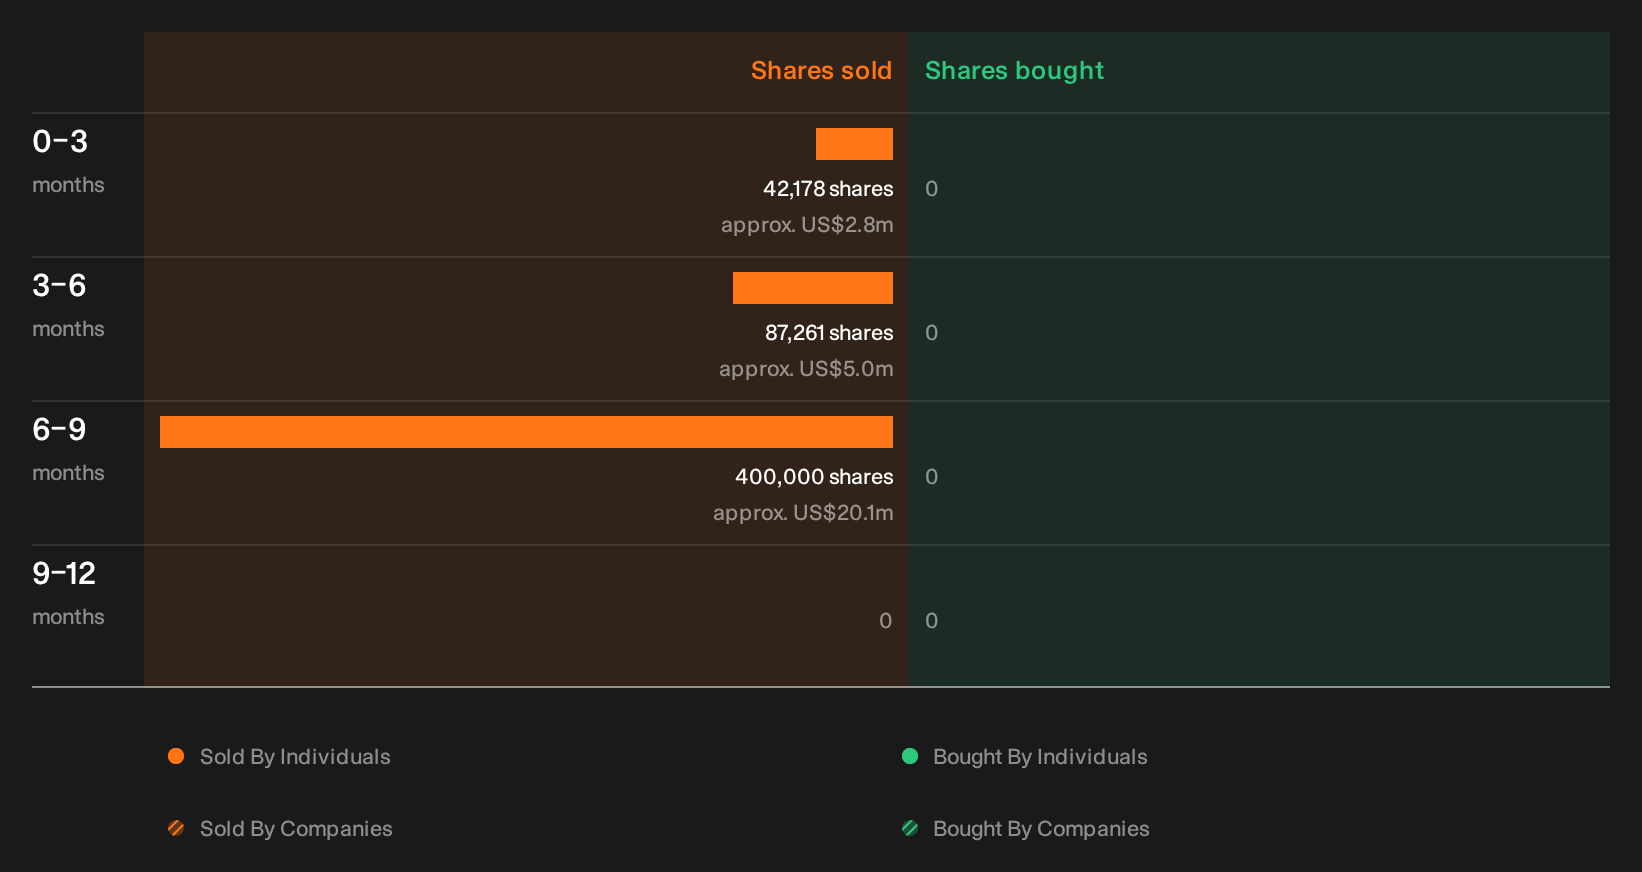
Price multiples and storylines say a lot about Cactus, yet recent trading by those closest to the business raises a separate question that only the underlying disclosures can answer. See the recent insider selling flagged for Cactus.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com