
Ouster (OUST) Stock May Be Overvalued After Its Huge 3 Year Run
Ouster has seen sharp swings in its share price in recent years, and with the stock closing at US$28.98 most recently, the live question is whether that level makes sense compared with what the business currently generates in sales. Recent product traction and contract activity give investors more to work with, but they also put fresh focus on how much revenue is being priced in today.
- Over the past 3 years the share price has risen by a very large amount, which puts considerable weight on whether the underlying sales base can support that kind of equity value.
- Recent rollouts of lidar sensors into defense and robotics applications, including autonomous vehicles operating in Ukraine and new AI computing hardware from Stereolabs, may support expectations for stronger product demand and potentially higher future sales.
- Your read on Ouster is one view; the desks covering it have another. See what analysts think Ouster's shares could be worth.
The issue now is whether Ouster's current market price is adequately supported by its sales when viewed against the Fair Ratio benchmark.
If you want to see how this same sales based valuation question plays out across a broader set of lidar and robotics related plays, check out 93 robotics and automation stocks.
Does Ouster Look Pricey on Sales?
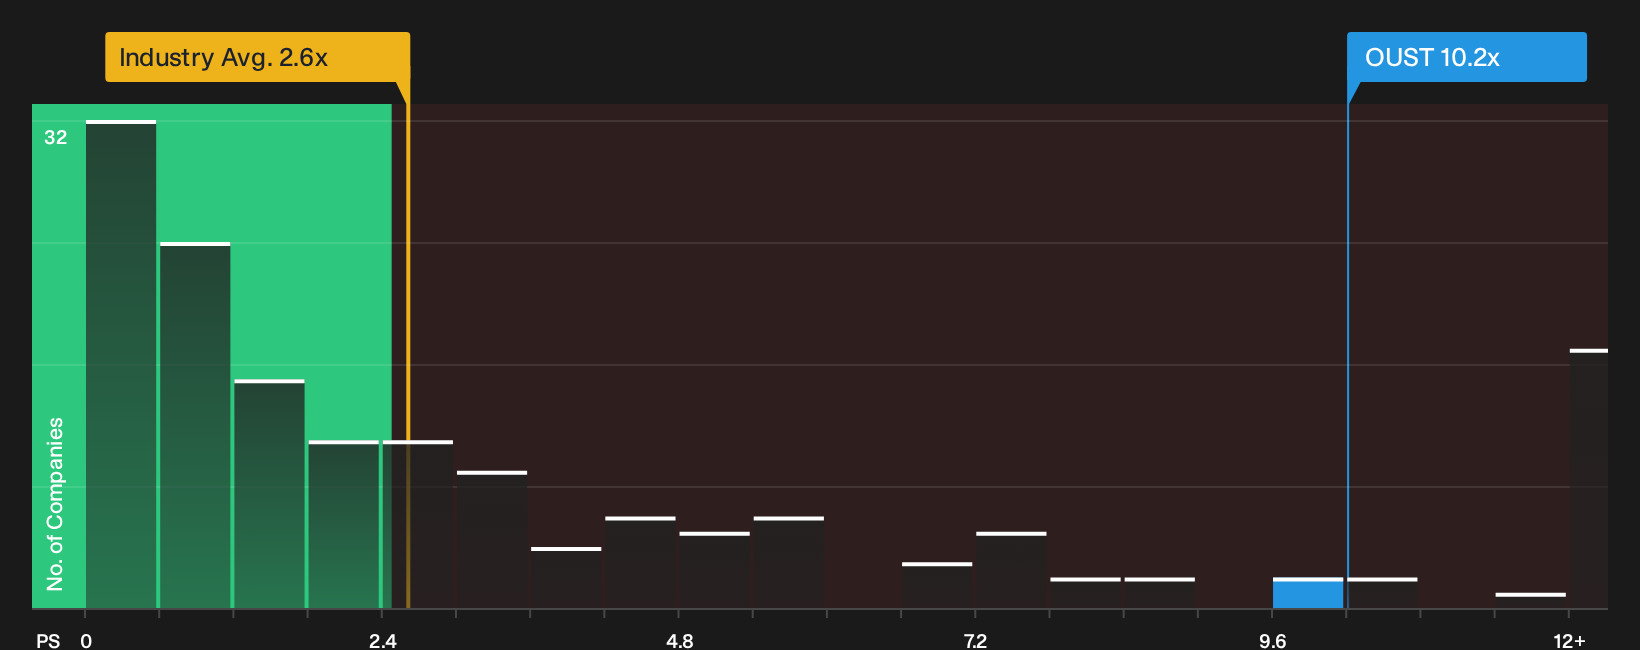
P/S is a useful lens for Ouster because investors are mainly paying for its revenue base and commercial traction rather than current profits. On this measure, the stock trades on a P/S ratio of 10.2x, compared with an Electronic industry average of about 2.6x and a peer group near 4.0x. This puts a lot of emphasis on how durable its lidar and robotics revenue proves to be.
Despite the recent headlines around Forterra’s Ukraine deployments and record sensor shipments, that 10.2x multiple still sits above what the Fair Ratio model suggests for Ouster once growth, margins, size and risk are blended into one benchmark. The current valuation implies that the market is already assigning a premium price tag to each dollar of sales relative to sector norms and the tailored Fair Ratio signal. You would need confidence that the lidar portfolio and Stereolabs AI hardware can justify that richer sales tag over time before treating the multiple as comfortable. Explore the numbers behind Ouster's P/S valuation.
The Ouster Narrative: What Would Justify Today's Price?
Ouster's valuation story only really snaps into focus once you spell out what would need to happen next with growth, margins and earnings for that P/S multiple to look either stretched or restrained. Simply Wall St Narratives do exactly that by turning those moving parts into clear, alternative paths for the business and its share price, with each scenario tying its number to a specific view on future growth, profitability and risk that you can test again as fresh information comes through.
One of the top community narratives on Ouster: 51% undervalued
"The main thing that has to go right is that Ouster converts growing lidar and camera shipments, expanded manufacturing capacity, and public sector program eligibility into sustained demand for its unified sensing, compute, and software platform…"
Discover why this Narrative puts Ouster at 51% undervalued.
One more piece of the Ouster puzzle worth checking
Balance sheet snapshots and sales multiples only tell part of Ouster's story, because professional coverage also sketches out where this business might be a few years from now. Explore where analysts expect Ouster to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com