
What YETI Holders Got Right
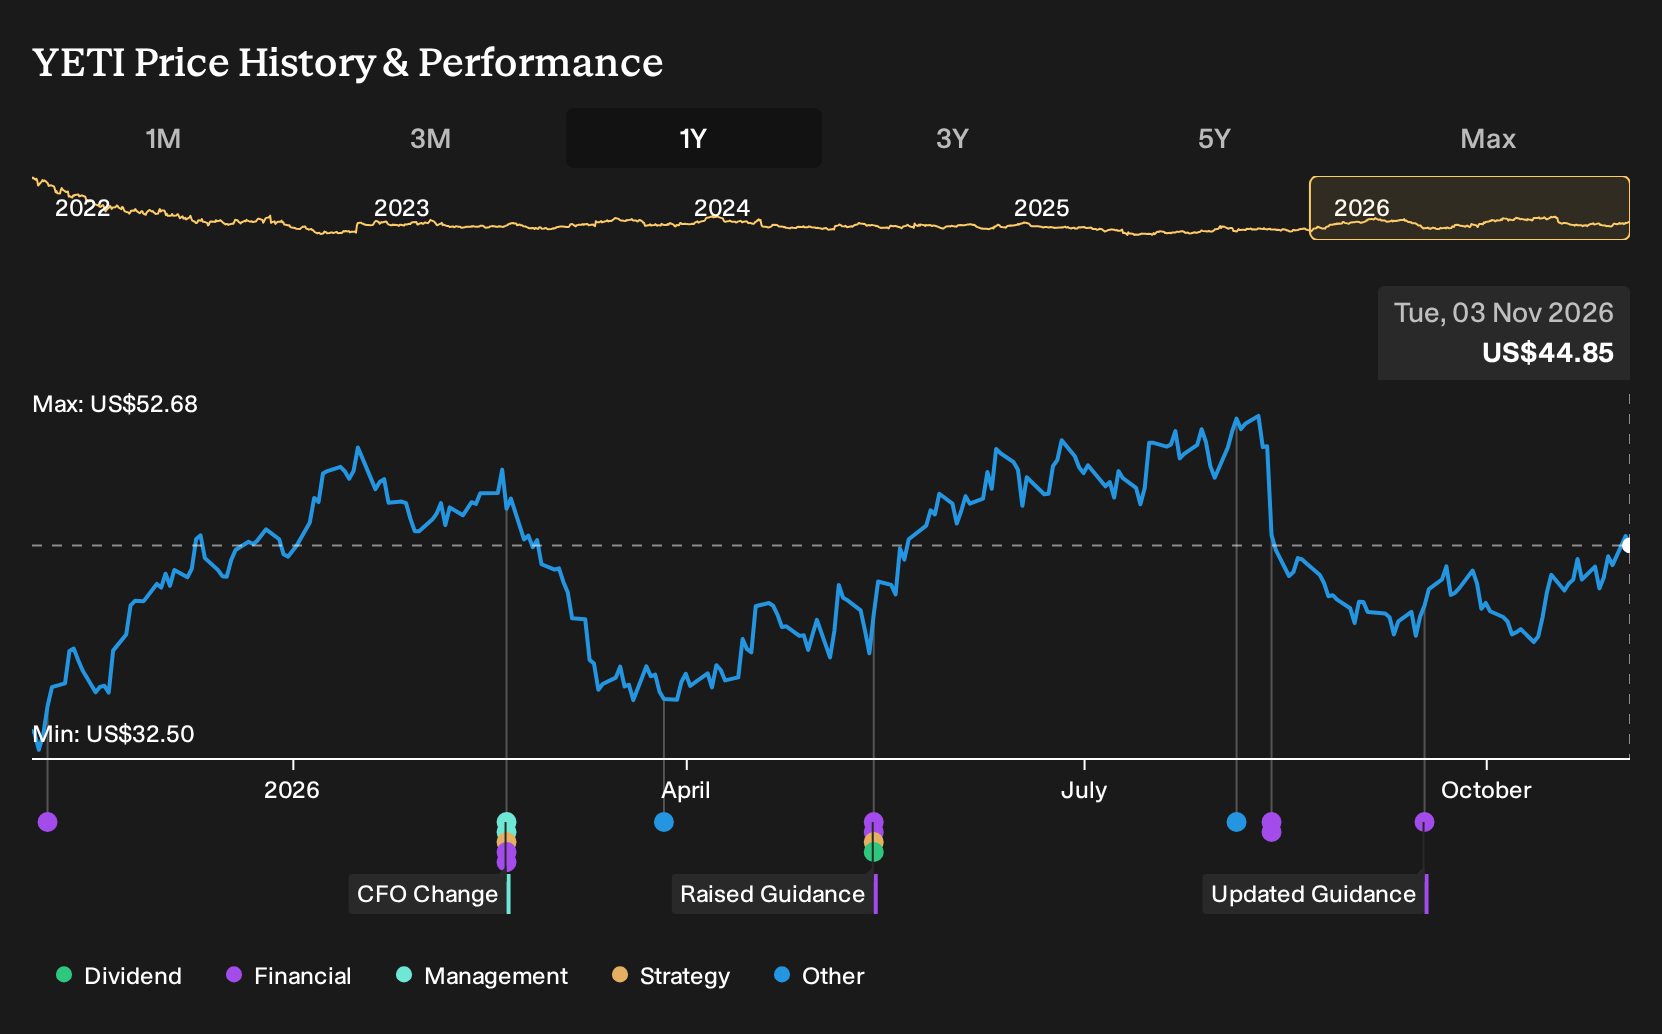
If you only glanced at recent headlines about softness in YETI’s U.S. drinkware category, a strong return might come as a surprise. Holding YETI over the past year would have returned 38.0%, including dividends. That outcome landed in the middle of a wide split, with bullish analysts arguing for global premium expansion and margin resilience, while bearish voices flagged economic pressure and online rivals. If you had faced that fork a year ago, which story would you have trusted?
YETI has already moved. See which of 35 high quality undervalued stocks still trade below our estimates.
The Two Stories YETI Investors Had To Weigh
The shares cost US$33.54 at the start of the period, and anyone looking at YETI then had to pick between two very different stories about where value might sit.
On the bullish side, one camp saw a Fair Value of US$53. This price was implied by assumptions about the business, built on rapid international expansion such as Japan’s jump from 17 to over 270 outlets and a supply chain shift that was expected to reset margins through lower tariffs.
The bearish view anchored on a Fair Value of US$29.83, also an implied number, and focused on risks that rising online competitors and private labels could chip away at YETI’s pricing power and push a gradual squeeze on profit margins from 9.7% to 9.3% over three years.
What The YETI Evidence Actually Showed
YETI lifted its fiscal 2026 earnings outlook after Q2 2026, as revenue rose to US$483.9 million and net income reached US$71.3 million, with net margin moving from 11.5% to 14.7%. That outcome supported the bullish view that margin resilience and international demand could hold up even while U.S. drinkware stayed soft. Tariff costs and margin pressure flagged in earlier quarters meant the cautious case was not fully dismissed. Overall, the evidence cut both ways.
The key assumption here was margin durability. For another consumer brand, you would track whether net income and net margin move in the same direction as management’s guidance, then judge how much of the story rests on cost structure rather than just sales growth.
What YETI's Price Now Asks You To Believe
YETI trades at US$44.85 today, after a 38.0% gain over the past year. The selected Narrative sees Fair Value above that level and roots the gap in what free cash flow and capital returns could mean for long term owners.
The argument is that today’s price still does not fully credit YETI turning brand reach, category breadth and productivity gains into sustained free cash flow that materially shrinks the share count.
"The plan to generate US$1.2b to US$1.4b of cumulative free cash flow through 2030, combined with a track record of meaningful share repurchases and a commitment to return at least 50% of free cash flow, provides scope for lower share count and higher earnings per share even if revenue growth remains in the guided range."
One Narrative disagrees with today's price. → See where this Narrative says YETI should trade
Before The Next Story Makes Headlines
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 45% below our estimate - turn a record project backlog into higher margin mechanical and modular build work.
- Company 2 - 33% below our estimate - sell GPU platforms that data centre buyers use to run large scale AI workloads.
- Company 3 - 38% below our estimate - secure subsea projects that shorten brownfield tieback timelines and support recurring services revenue.
Three companies from the same screener. Open the full list of 23 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com