
Could InvenTrust Properties (IVT) Be 11% Undervalued As 2026 Guidance Rises?
InvenTrust Properties (IVT) moved into focus after reporting third quarter earnings, with basic and diluted earnings per share from continuing operations at US$0.25, and raising full year 2026 net income guidance.
Despite the stronger third quarter figures and raised 2026 guidance, InvenTrust Properties shares have eased 7.2% over the past 90 days. However, the year-to-date share price return of 11.48% and 1-year total shareholder return of 16.36% point to momentum that has been positive over a longer stretch.
Scan how InvenTrust Properties compares with other real estate names showing resilient momentum and fundamentals by reviewing the hand-picked list of solid balance sheet and fundamentals (23 results) in a single view.
The recent pullback leaves InvenTrust Properties giving back a slice of that multi year run, not the whole story. Is the better guidance now largely reflected in US$31, or is there still valuation headroom?
Most Popular Narrative: 11% Undervalued
On the most followed view, InvenTrust Properties screens as cheaper than an assessed fair value of $35, against a last close of $31.08. The gap rests on how far Sun Belt leasing momentum and cash flow conversion can carry earnings over time.
Ongoing capital redeployment toward Sun Belt and emerging secondary markets such as Nashville, Knoxville, Charleston and Greensboro, supported by approximately US$290 million of acquisitions in the first half of 2026, can continue to tilt InvenTrust Properties toward assets where rent growth and NOI have room to progress, which can support higher revenue and earnings over time.
See why 0 investors see InvenTrust Properties as 11% undervalued.
Result: Fair Value of $35 (UNDERVALUED)
Still, two pressure points could challenge that 11% undervalued story for InvenTrust Properties: higher acquisition pricing compressing returns, and external analysts guiding to a lower US$29 target.
Find out about the key risks to this InvenTrust Properties narrative.
Another View: InvenTrust Properties Looks Expensive On Earnings
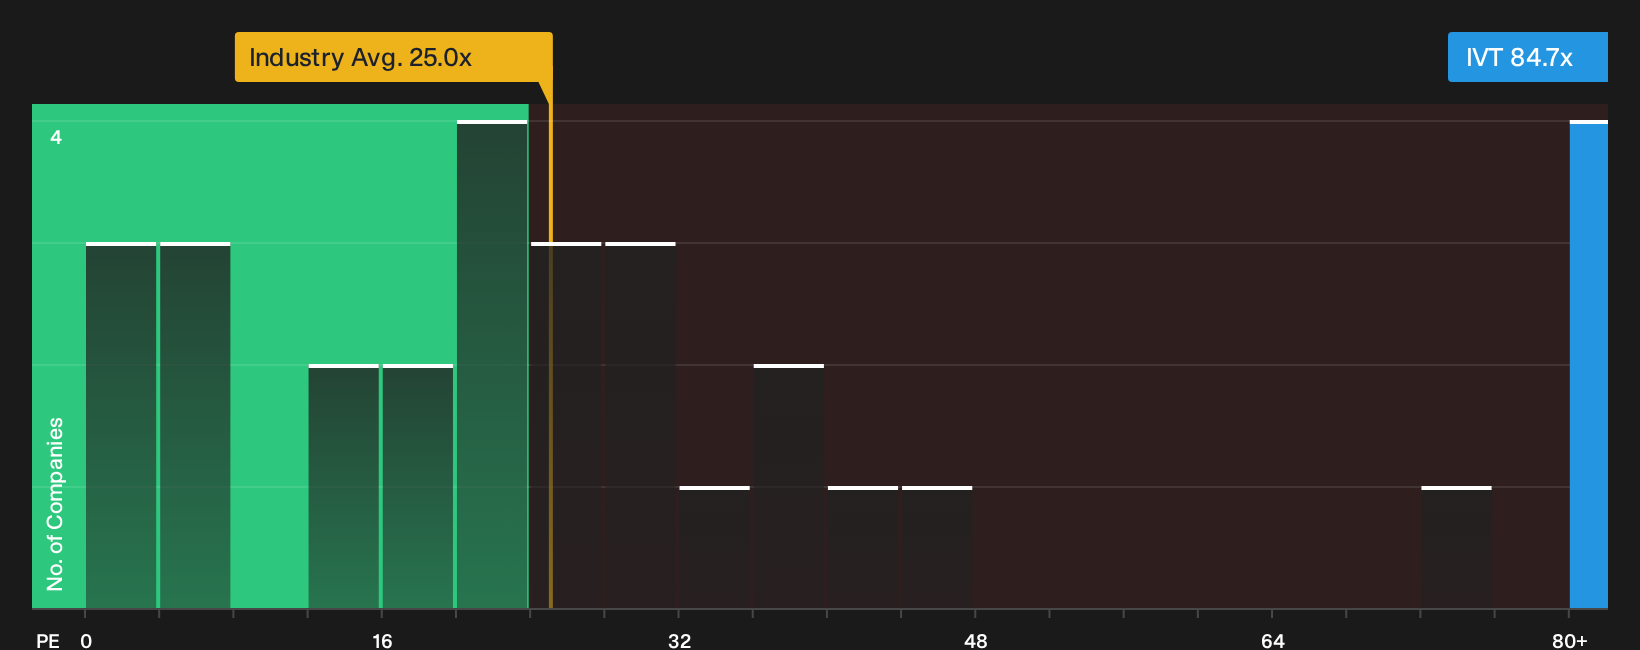
Looking beyond the 11% undervalued story, InvenTrust Properties appears very different on an earnings basis. The shares trade on a P/E of 84.7x, compared with 55.4x for peers and 24.1x for the wider US Retail REITs group. The fair ratio sits at 18.1x. This gap highlights a meaningful valuation risk if current enthusiasm does not persist.
For a closer look at how this earnings-based view compares with cash flow assumptions, review how the SWS DCF model is built and what it is actually pricing in for InvenTrust Properties. Then test those inputs against your own expectations. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on valuation and earnings can easily pull sentiment in opposite directions, so review the underlying figures and form your own stance quickly. For a structured view of both the risks investors worry about and the potential rewards that still attract interest, start with the 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond InvenTrust Properties?
If InvenTrust Properties has sharpened your thinking on valuation and risk, broaden your watchlist with a few focused stock pools built from hard numbers, not headlines.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results), which filters for financial strength first.
- Hunt for potential mispricings by working through the 35 high quality undervalued stocks, which surfaces companies trading below assessed value on key metrics.
- Prioritise income and staying power by reviewing the 30 resilient stocks with low risk scores, which combines lower risk scores with clear, data backed profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com