
What Are Wall Street Analysts' Target Price for Johnson Controls Stock?
Johnson Controls International plc (JCI), headquartered in Cork, Ireland, engineers, manufactures, commissions, and retrofits building products and systems. With a market cap of $90.8 billion, the company offers air systems, building management, HVAC controls, security, and fire safety solutions.
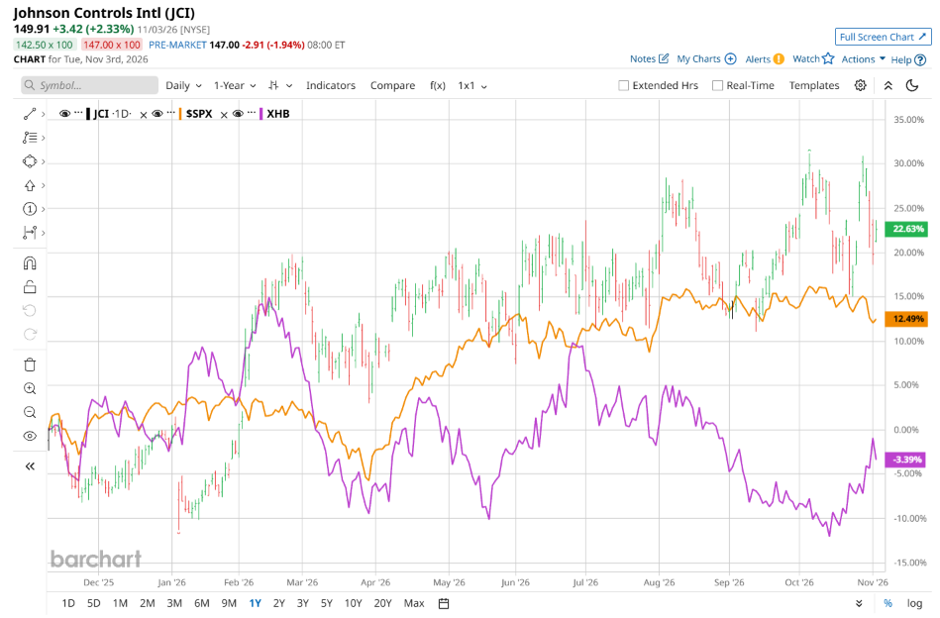
Shares of this engineering giant have outperformed the broader market over the past year. JCI has gained 32.5% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 10.5%. In 2026, JCI stock is up 25.2%, surpassing the SPX’s 10.6% gains on a YTD basis.
Zooming in further, JCI’s outperformance looks more pronounced compared to the State Street SPDR S&P Homebuilders ETF (XHB). The exchange-traded fund has declined about 1.4% over the past year. Moreover, JCI’s double-digit gains on a YTD basis outshine the ETF’s marginal losses over the same time frame.
Johnson Controls outperformed driven by robust data center and mission-critical demand, disciplined capital execution, and strategic investments in thermal management. Strong quarterly execution fueled a top-line performance with Q4 revenue reaching $7.1 billion alongside an adjusted EPS of $1.66, beating expectations. A record $23 billion backlog, margin expansion across the Americas and Asia-Pacific, and ongoing portfolio simplification, such as the residential intrusion divestiture, further fueled growth. Looking ahead, JCI aims to leverage its $900 million capex plan, manufacturing efficiencies, and a new restructuring program to drive profitability and capacity expansion through fiscal 2029.
For fiscal 2027, ending in September 2027, analysts expect JCI’s EPS to grow 21.9% to $6.29 on a diluted basis. The company’s earnings surprise history is impressive. It beat the consensus estimate in each of the last four quarters.
Among the 21 analysts covering JCI stock, the consensus is a “Moderate Buy.” That’s based on 12 “Strong Buy” ratings, eight “Holds,” and one “Strong Sell.”
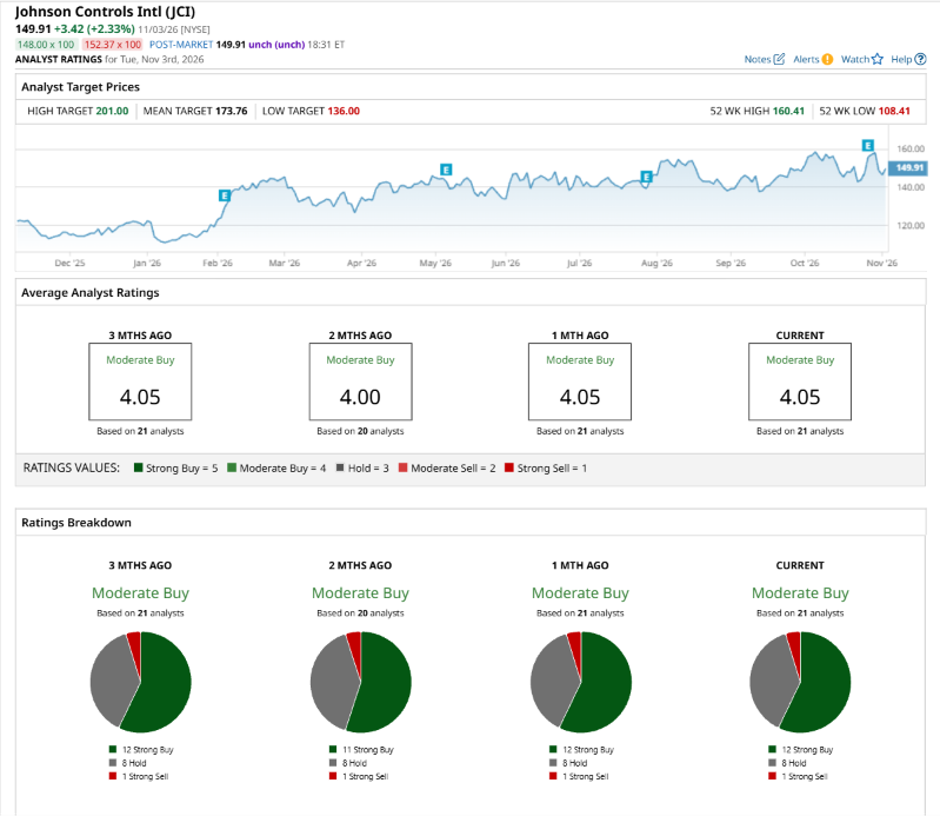
This configuration is more bullish than two months ago, with 11 analysts suggesting a “Strong Buy.”
On Nov. 1, Varun Govindaraj from Bernstein maintained a “Buy” rating on JCI, with a price target of $194, implying a potential upside of 29.4% from current levels.
The mean price target of $173.76 represents a 15.9% premium to JCI’s current price levels. The Street-high price target of $201 suggests a notable upside potential of 34.1%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.