
Is Mixed Earnings Altering The Investment Case For AutoNation (AN)?
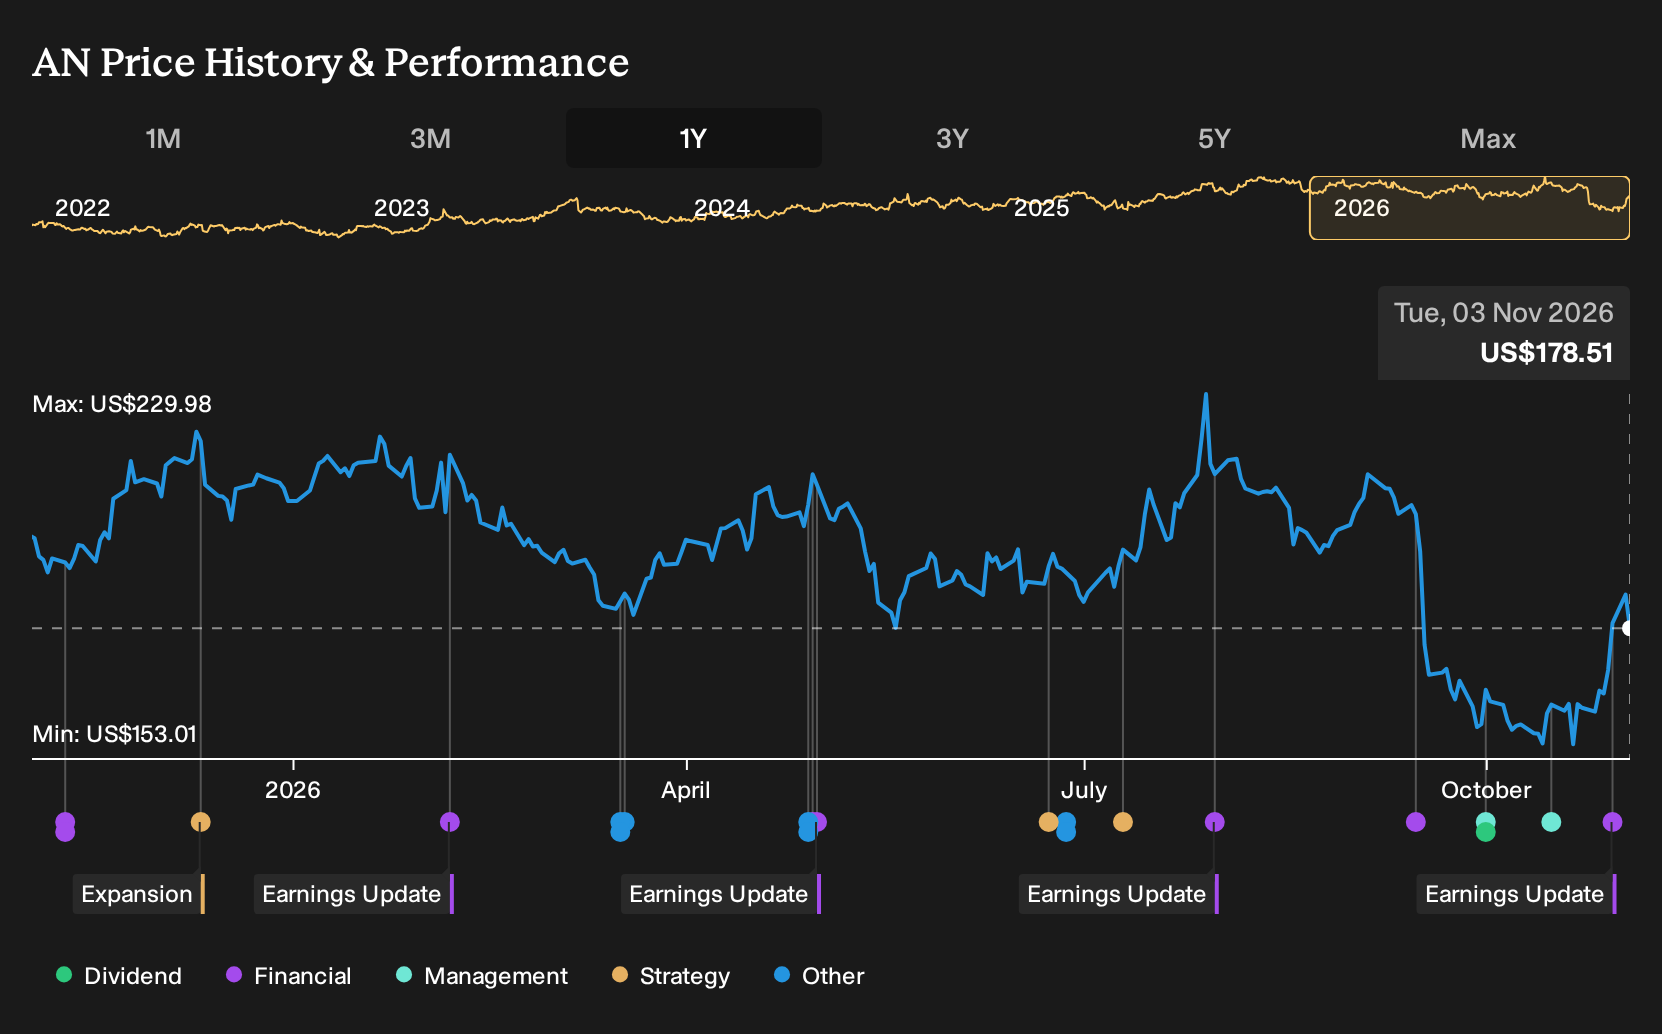
- AutoNation reported third quarter 2026 revenue of US$7,010.3 million and net income of US$162.3 million, alongside a share repurchase of 1,121,543 shares for US$210.96 million between July and late October.
- The nine month figures show higher net income and earnings per share from continuing operations compared with the prior year, while the long running buyback program has now absorbed over 175 million shares for about US$11 billion. As a result, current holders own a larger slice of the earnings base.
- We will now look at how AutoNation’s mixed quarterly earnings and continued buybacks could influence the broader investment narrative.
Scan beyond AutoNation and compare how other capital return focused businesses stack up using our curated 35 high quality undervalued stocks as a starting point for your next idea.
AutoNation Investment Narrative Recap
To own AutoNation, you need to be comfortable with a story where aftersales and customer finance do more of the heavy lifting than new car volume. The third quarter showed softer quarterly earnings, so the near term hinge point is whether parts, service and AutoNation Finance keep offsetting pressure on vehicle margins and premium luxury demand.
The biggest near term risk is that customers pull back on maintenance or higher ticket vehicles, which would test the resilience of that higher margin mix. Recent results did not fundamentally change that risk reward balance. They mostly gave you a cleaner read on how the existing model behaves in a cooler quarter.
The most relevant update here is the third quarter and nine month earnings print. Revenue for the quarter was US$7,010.3 million with net income of US$162.3 million, while nine month revenue reached US$20,492.2 million and net income was US$549.8 million. Earnings per share from continuing operations followed this pattern on both a basic and diluted basis.
That profile matters for your catalyst checklist. Aftersales and finance are still doing the work in a tougher selling backdrop, but the moderation in quarterly profit keeps the spotlight on execution, especially around AutoNation Finance growth, credit quality and cost control. Any sustained hit to service activity or regulatory pressure on dealer practices would directly affect that thesis.
What The Current AutoNation Setup Implies
AutoNation's narrative projects US$30.2b revenue and US$829.7m earnings by 2029. This assumes 3.3% yearly revenue growth and an earnings increase of about US$107.8m from US$721.9m today.
Uncover why AutoNation's fair value indicates a 20% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic AutoNation analysts focus on share repurchases as the key catalyst. Before this earnings update, that group was penciling in revenue of about US$31.7b and earnings near US$794.6m by 2029, along with a higher 11.5x P/E. You can now weigh those pre news expectations against today’s softer quarter and sizeable buyback, and decide which narrative feels closer to your own view.
Explore another AutoNation fair value estimate, including one that suggests there could be as much as 85% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your AutoNation research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for AutoNation. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate AutoNation's overall financial health at a glance.
Looking For More Investment Ideas Beyond AutoNation?
Once you have a handle on AutoNation, it can help to widen the lens and compare it with other companies that match the type of profile you prefer, whether that is value, income or resilience.
- If you want potential value with quality fundamentals in mind, start by scanning our curated set of 35 high quality undervalued stocks that could fit a more disciplined watchlist.
- For investors who care most about stability and balance sheet strength, focus on businesses from the list of solid balance sheet and fundamentals (23 results) to see which ones line up with your risk tolerance.
- When you prefer underfollowed stories with strong financial underpinnings, hunt through the 19 high quality undiscovered gems to spot candidates that might not yet be on the market's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com