
What Investors Got Wrong About Tsakos Energy Navigation Before A 121% Jump
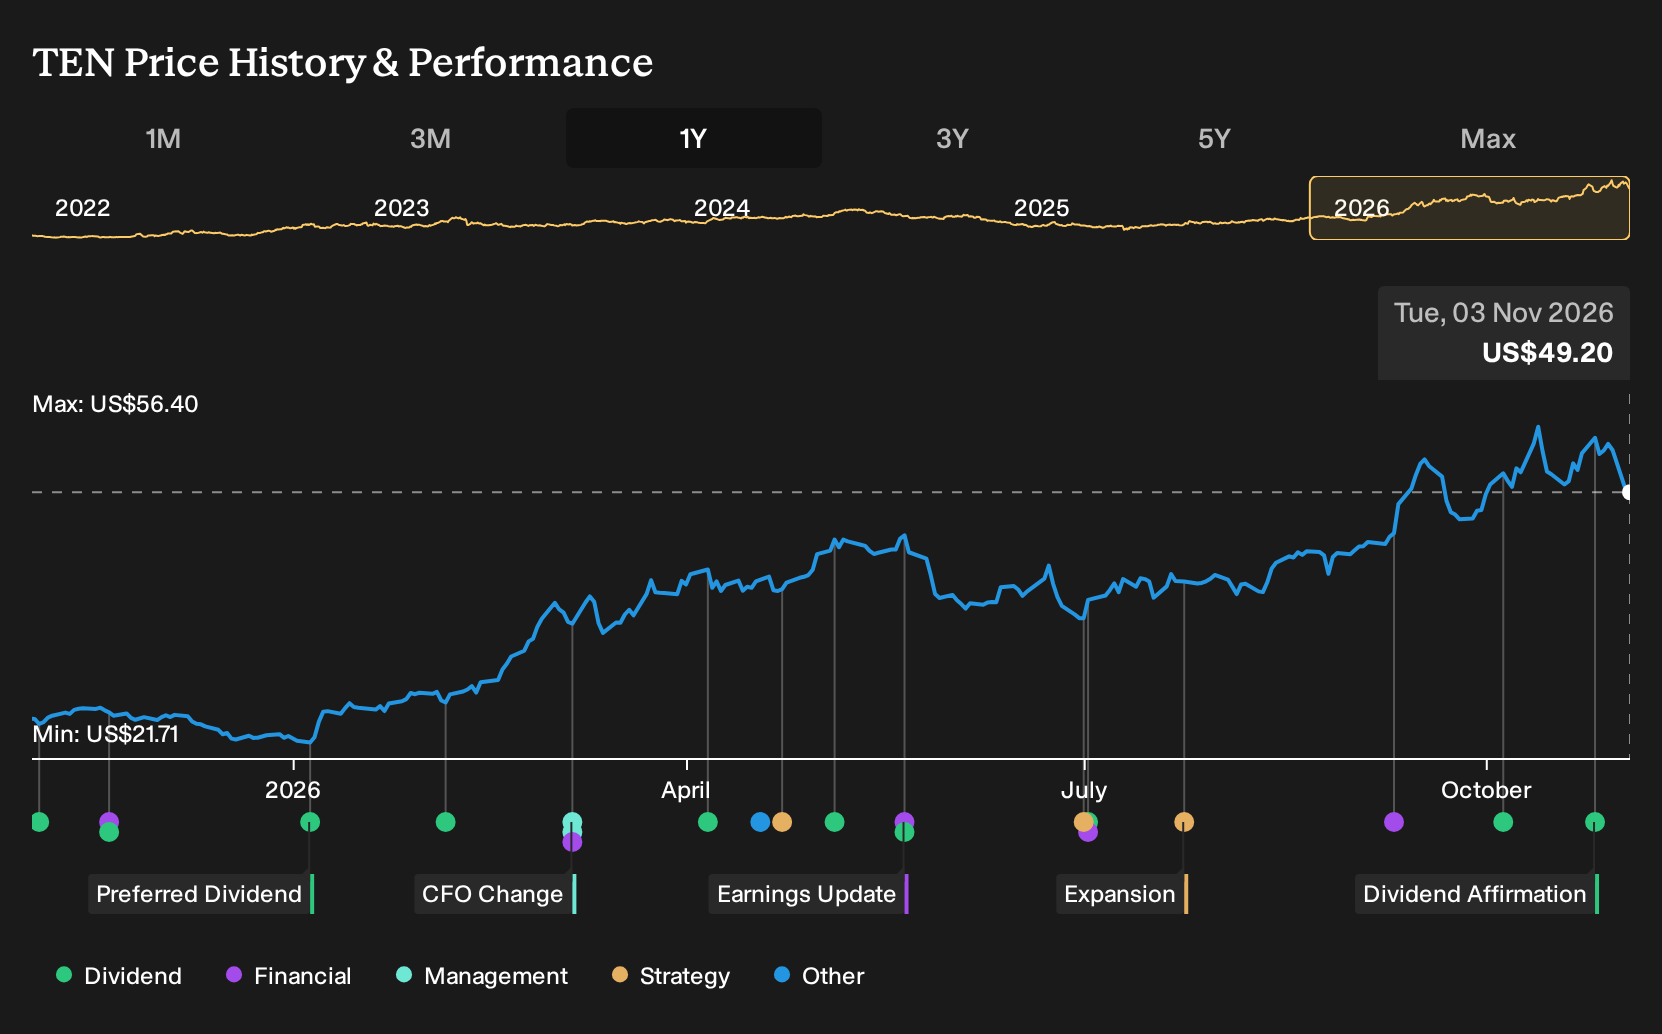
If you had bought Tsakos Energy Navigation on 3 November 2025 and simply sat tight for a year, the outcome was dramatic. Holding Tsakos Energy Navigation over the past year would have returned 121.3%, including dividends. At the start, you were staring at a tanker owner pouring money into eco-friendly upgrades while analysts argued over whether decarbonization or a US$3.7 to 4.0 billion charter backlog would matter more. If you faced that choice again today, how would you weigh those trade offs?
A Narrative on Simply Wall St is one investor's written case for a company, with its growth, margin and multiple assumptions spelled out. Those assumptions imply an estimated Fair Value.
The easy part of this move is behind Tsakos Energy Navigation. Zero in on 35 high quality undervalued stocks for companies trading below our estimates.
The Argument Tsakos Energy Navigation Investors Were Really Weighing
The shares cost US$24.29 at the start of the period, and Tsakos Energy Navigation sat between two sharply different stories that both sounded reasonable at the time.
On the bullish side, one Fair Value case of US$30.33 rested on heavy investment in eco-friendly, dual fuel vessels, as well as a US$3.7 to 4.0b charter backlog that was expected to support margins and earnings resilience.
The more cautious view put Fair Value at US$22 and focused on decarbonization trends, tighter regulations, and an aging fleet that could require recurring upgrade spending and make future funding more difficult.
What The Results Changed For Tsakos Energy Navigation
Tsakos Energy Navigation then reported Q2 2026 revenue of US$298.4 million and net income of US$131.9 million, with net margin rising to 44.2% from 10.2%. That outcome leaned toward the bullish case that focused on upgraded vessels and a multi billion dollar charter backlog. The cautious view was not erased, but the earnings power argument gained more support than the decarbonization worries.
The episode hinged on one assumption: cash flow from contracts and fleet renewal needed to show up as fatter margins. When you judge another shipper, track how net margin and contracted backlog move together from one reporting period to the next.
What Tsakos Energy Navigation's Rally Already Prices In
Tsakos Energy Navigation now trades at US$49.2, after a 121.3% gain over the past year. The selected Narrative places its Fair Value above that level, based on how the refreshed fleet plan and contract book reshape earnings power.
At this price, you are effectively judging whether recycling older ships into a large newbuilding pipeline and long term profit sharing deals still is not fully reflected.
"Tsakos Energy Navigation is committing around $3.1–3.2b to a 20–26 vessel newbuilding pipeline while also adding modern secondhand ships. This increases future capital employed and can lift revenue and earnings expectations well beyond what current contracted cash flows support."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 38% below our estimate - advises on increasingly complex AI failures, user safety issues and regulatory challenges.
- Company 2 - 33% below our estimate - targets large-scale AI data center buildouts reliant on its GPUs and software stack.
- Company 3 - 45% below our estimate - converts a substantial technology backlog into long-duration data center and modular infrastructure projects.
Those are three of them. See every one of the 23 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com