
Stepan (SCL) As Stronger Q3 Results And Dividend Growth Revive The Undervalued View
Stepan (SCL) has moved back into focus after reporting third quarter sales of US$692.15 million and net income of US$17.81 million, along with another incremental increase in its long running dividend.
Recent trading has reflected that mix of improving quarterly numbers and a still-recovering longer history, with Stepan’s share price returning 8.98% over the past month and 45.59% year to date, while its 5 year total shareholder return is down 40.33% even after a 67.28% gain over the past 12 months.
Compare Stepan’s rebound with a curated list of solid balance sheet and fundamentals (23 results) that could help you find other businesses pairing durable finances with recent share price momentum.
Stepan now pairs a long dividend record with a sharp share price rebound. The harder question is whether that recovery already reflects what this chemicals business is worth today.
Most Popular Narrative: 19% Undervalued
On Simply Wall St’s most followed view, Stepan’s fair value sits at $85 against a last close of $68.66. That gap puts the focus squarely on whether the firm can turn its cost reset and product mix ambitions into steadier earnings.
Ongoing Project Catalyst actions, including site closures such as Fieldsboro and asset decommissioning in Millsdale and Stalybridge, together with targeted salaried headcount and procurement efficiencies, are expected to support the approximately US$100 million pretax savings plan over two years and could reset Stepan’s cost base in a way that benefits earnings quality and margins.
See why 6 investors see Stepan as 19% undervalued.
Result: Fair Value of $85 (UNDERVALUED)
Still, Stepan’s story can unravel if oleochemical input costs stay elevated, or if weak rigid polyol demand keeps construction-exposed earnings under pressure.
Find out about the key risks to this Stepan narrative.
Another View: What Multiples Say About Stepan
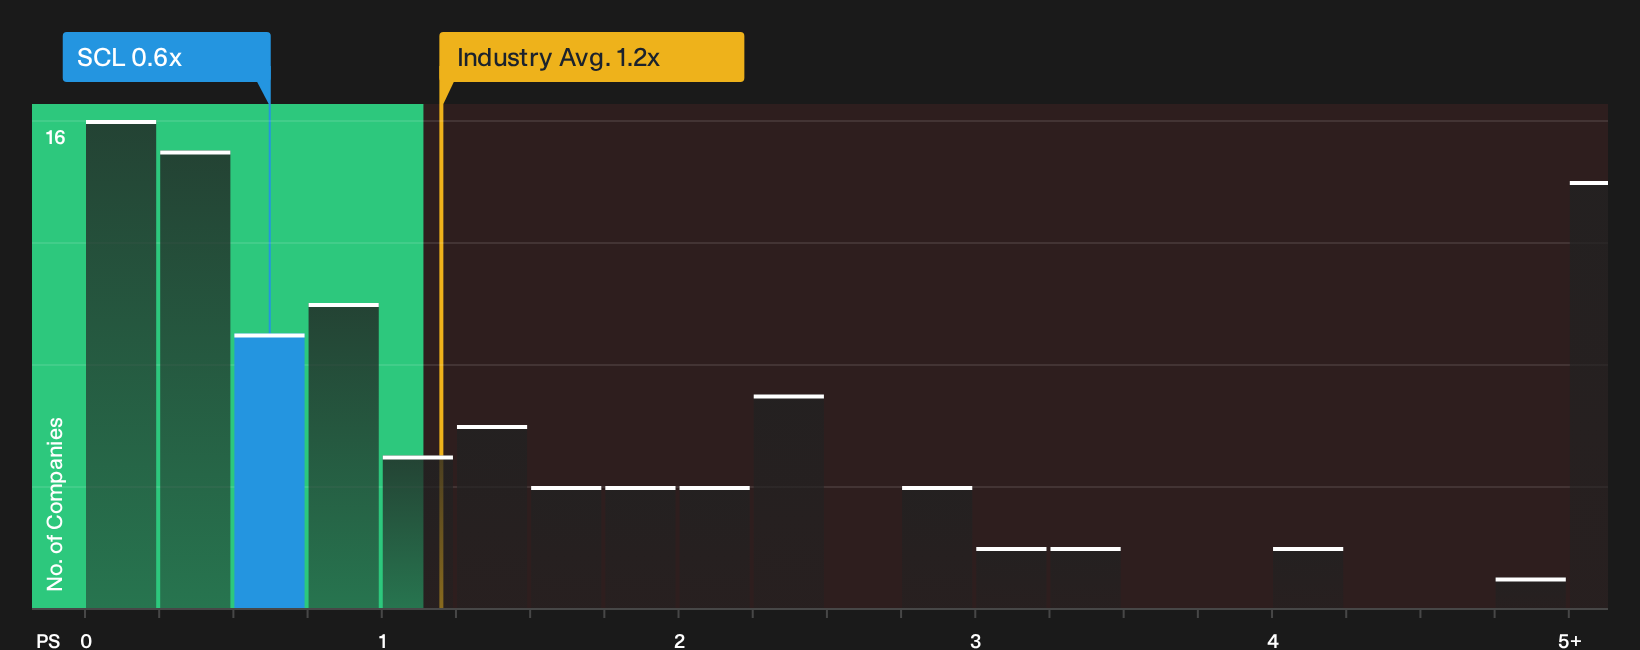
Set against that fair value of $85, Stepan looks very different when you zoom in on its sales multiple. The stock trades on a P/S ratio of 0.6x, which lines up exactly with the fair ratio of 0.6x suggested by the Simply Wall St model.
At the same time, that 0.6x P/S sits well below both the US Chemicals industry average of 1.2x and a peer group average of 1.1x. The gap hints at either a cushion if earnings and margins repair or a market that still has doubts about Stepan’s recent profitability and debt load. Which side of that trade do you think is closer to the truth?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals over Stepan’s rebound make this a moment to move fast, review the numbers directly, and pressure test your own thesis. To balance the optimism against the issues on the table, start with our breakdown of 2 key rewards and 4 important warning signs
Looking for more Stepan investment ideas?
If Stepan has put you back in research mode, do not stop at a single ticker. Use Simply Wall St screeners to pressure test fresh opportunities before they move.
- Target potential upside by scanning a focused universe of 19 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- Strengthen your defensive side by filtering for 30 resilient stocks with low risk scores that aim to limit balance sheet and volatility shocks.
- Pursue value opportunities by reviewing a curated list of 35 high quality undervalued stocks that combine quality metrics with discounted pricing.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com