
Earnings Beat Might Change The Case For Investing In Vaisala Stock
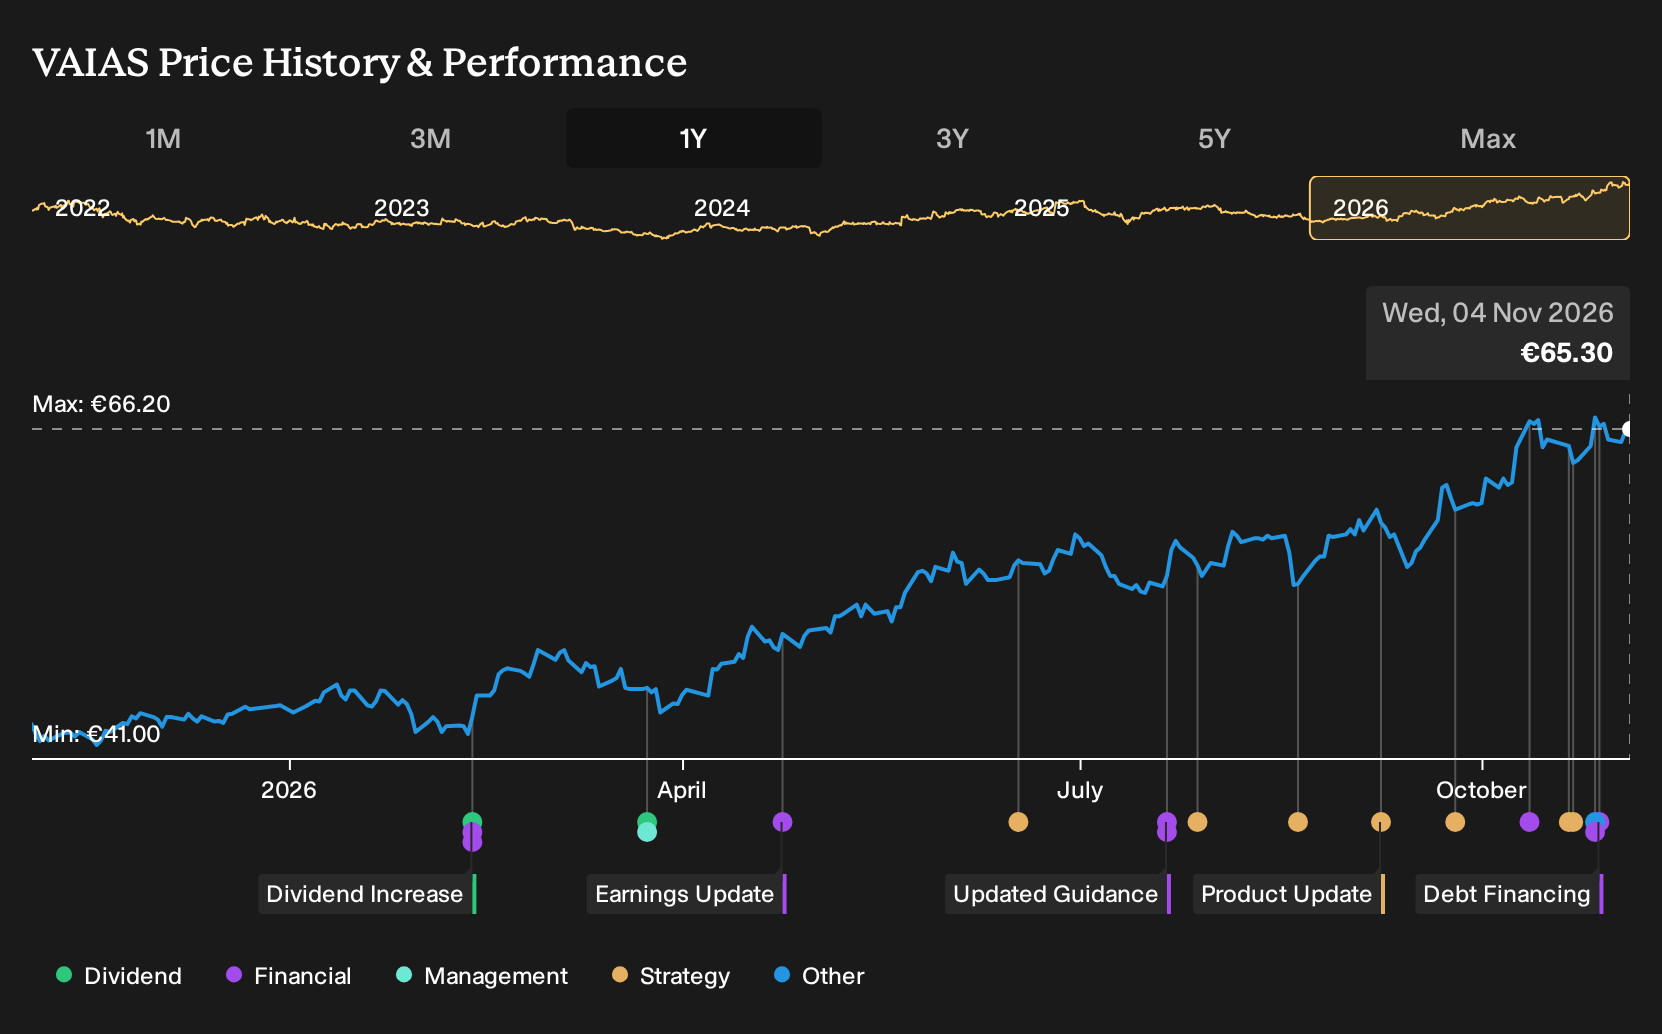
- Vaisala Oyj recently reported third quarter 2026 sales of €162.9 million and net income of €29 million, alongside a new €100 million unsecured three year loan facility intended for general corporate purposes, including the refinancing of a €70 million term loan.
- Together with the launch of the Viewlinc Cloud Suite and an AI focused weather collaboration with NVIDIA, Vaisala is emphasizing higher value monitoring, digital, and data driven services that can reshape its revenue mix over time.
- This article examines how Vaisala Oyj's investment narrative relates to its Q3 earnings performance and its new AI weather collaboration.
Scan beyond Vaisala Oyj and this AI and data driven weather theme by reviewing a curated group of 53 AI infrastructure stocks.
Vaisala Oyj Investment Narrative Recap
To own Vaisala Oyj, you need to believe its mix of environmental measurement hardware, software and services can keep compounding despite cyclical pockets such as renewable energy and public sector projects. The latest quarter, with €162.9 million in sales and €29 million in net income, supports a story of solid execution while the business pushes further into digital and subscription offerings.
The key near-term swing factor is whether industrial and digital demand stays strong enough to offset weak renewable activity and any uneven government ordering. The new €100 million loan facility appears more like balance sheet housekeeping than a major catalyst, although gearing covenants add another hard constraint if conditions soften.
The earnings release is the most relevant event in this context. Higher Q3 net income of €29 million, with both basic and diluted EPS from continuing operations ahead of last year, gives Vaisala Oyj more room to keep funding product development, AI collaborations and lifecycle services from a position of financial strength rather than relying solely on external borrowing.
That consideration matters when set against the catalysts investors are watching. Growth in Industrial Measurements, Xweather and now Viewlinc Cloud Suite relies on continued investment and reliable delivery. Strong recent profitability and the new loan facility together help support that execution, while the main risk still lies in any prolonged softness in renewables, aviation and public spending that could offset these gains.
Vaisala Oyj’s current analyst story points to forecast revenues of €751.7 million and earnings of €104.5 million by 2029, based on an assumed 7.5% yearly revenue growth rate and an earnings increase of about €39.2 million from €65.3 million today.
Uncover why Vaisala Oyj's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The three fair value estimates from the Simply Wall St Community cluster tightly between €60.8 and €66, so retail investors there see only a narrow valuation gap. You should weigh that against the new €100 million loan capacity, Viewlinc Cloud Suite rollout and NVIDIA collaboration, which together could reshape how Vaisala Oyj earns and funds its future.
Explore 2 other Vaisala Oyj fair value estimates, including one that suggests it could be worth as much as €66.00.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Vaisala Oyj research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Vaisala Oyj. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vaisala Oyj's overall financial health at a glance.
Looking For More Ideas Beyond Vaisala Oyj?
If the Vaisala Oyj story has sharpened your thinking about quality, risk and income, it can be useful to line it up against a broader watchlist built around clear themes.
- For investors who want potential mispricing paired with robust fundamentals, scan a curated group of 197 high quality undervalued stocks that meet strict quality filters.
- If capital preservation sits high on your priority list, focus on resilience first by reviewing a 223 resilient stocks with low risk scores that score well on stability metrics and business strength.
- When you care most about balance sheet strength and dependable fundamentals, build out a shortlist using a list of solid balance sheet and fundamentals (195 results) as a reference point for further research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com