
Half Year Earnings Beat Might Change The Case For M and S Shares
- Marks and Spencer Group reported half year sales of £9,168.6 million and net income of £265.8 million for the period to 26 September 2026, with basic earnings per share from continuing operations at £0.129.
- The sharp shift in profitability versus the prior year reflects how operating performance and cost control are contributing to higher earnings for Marks and Spencer Group.
- Attention now turns to how Marks and Spencer Group's stronger half year earnings profile might influence the investment narrative that analysts outlined previously.
Marks and Spencer Group Investment Narrative Recap
For an investor to stay with Marks and Spencer Group, the belief has to be that heavy spend on store rotation, supply chain automation and digital tools turns into cleaner execution and steadier profitability. The latest half year earnings lift that case, because stronger profits give more headroom to keep funding £650m to £750m of capital projects without stretching the balance sheet.
The near term swing factor still looks like execution on those programmes, especially in Clothing and Home and in online where weaker margins have been a concern. The biggest risk remains that high cost projects, cyber issues or stock flow snags chip away at margins and leave cash generation under pressure.
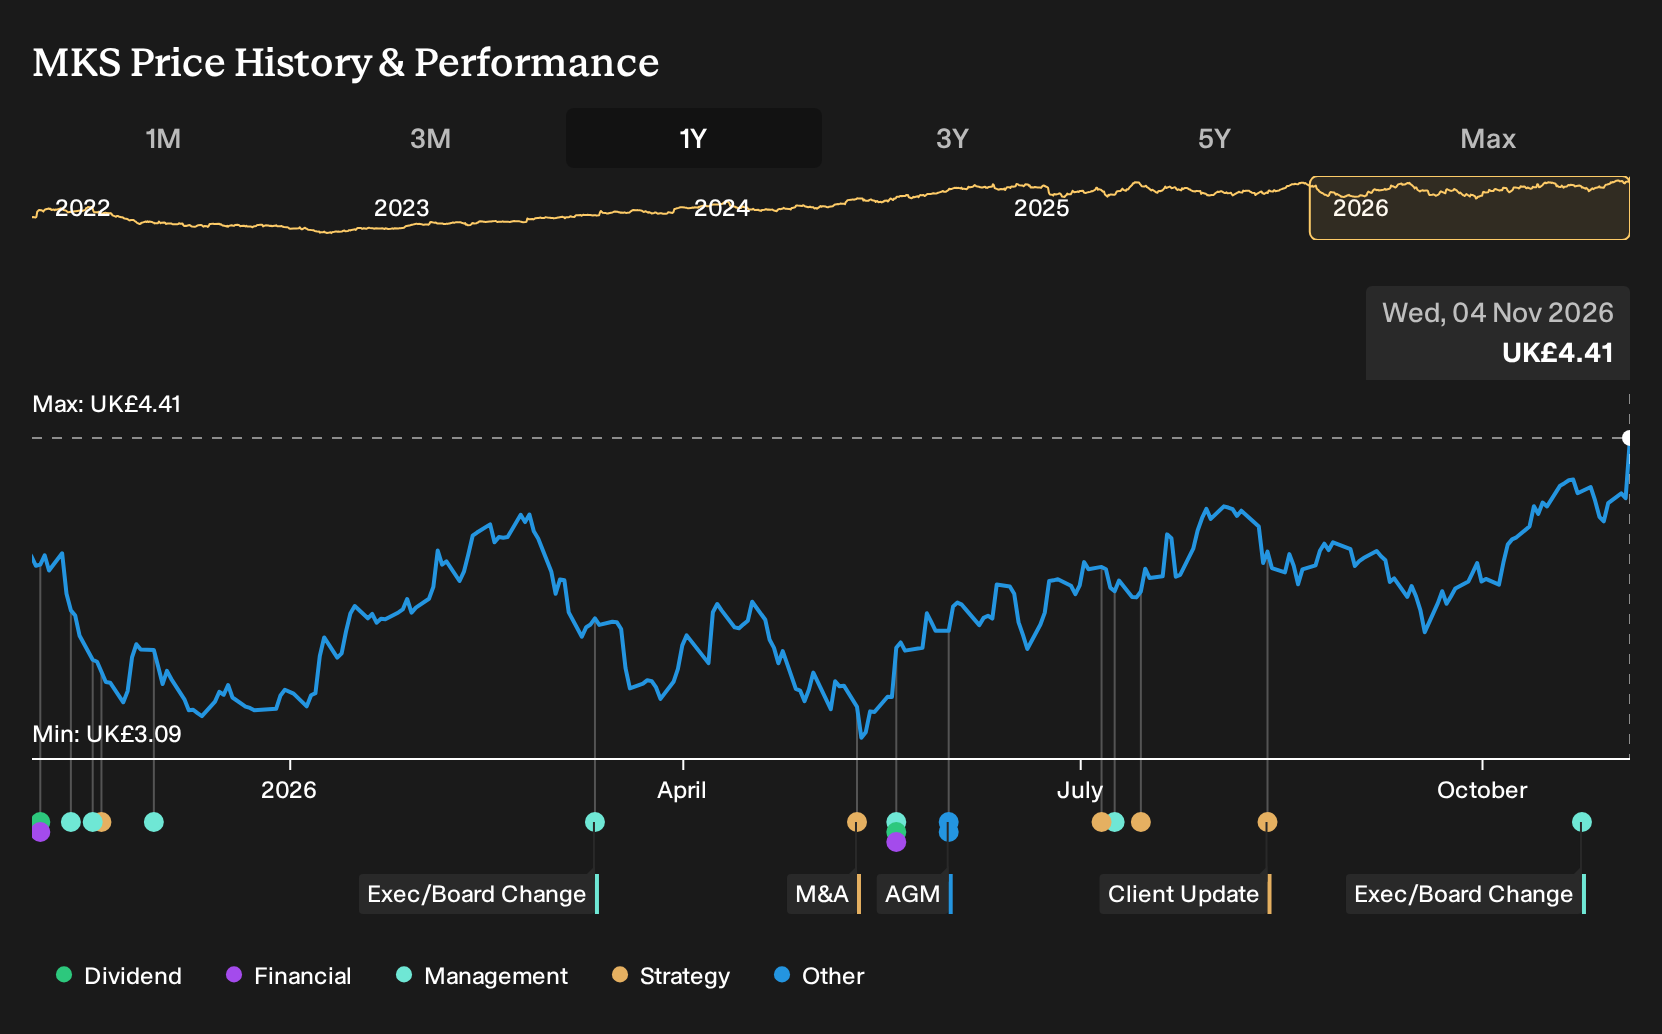
Among recent updates, the H1 2027 earnings release on 4 November 2026 is most relevant. Marks and Spencer Group reported £9,168.6m of sales and £265.8m of net income for the half year, with basic earnings per share from continuing operations of £0.129. Those numbers sit against analysts expecting earnings to grow over time, but at a measured pace.
For you, the read across is simple. Better profitability supports the long term plan built around food store expansion, automation and digital investment. At the same time, past one off items and still modest net margins signal that execution risk has not gone away. The pre recorded earnings call gives extra colour on how management sees that trade off between ongoing spend and returns.
Marks and Spencer Group's analyst narrative points to £21.0b of revenue and £762.8m of earnings by 2029, tied to assumed yearly revenue growth of 6.7% and an earnings increase of about £503m from £259.4m today.
Uncover why Marks and Spencer Group's fair value aligns with its current price.
Exploring Other Perspectives
There are only 3 fair value estimates from the Simply Wall St Community, yet they already span a wide band from £4.45 up to about £8.37. That kind of spread shows how far opinions on Marks and Spencer Group can diverge, especially before the latest earnings and international or online execution risks are fully factored in. Treat this as a prompt to compare several viewpoints rather than anchor on a single number.
Explore 2 other Marks and Spencer Group fair value estimates, including one that suggests it could be worth just £4.45.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Marks and Spencer Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Marks and Spencer Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Marks and Spencer Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Marks and Spencer Group?
Once you have formed a view on Marks and Spencer Group, it can help to widen the lens and compare it with other opportunities that share some of the qualities you value most. The Simply Wall St Screener lets you do exactly that by filtering the market around the factors that matter to you, from balance sheet strength to lower risk profiles.
- If capital preservation comes first for you, start with a shortlist of resilient candidates using our 5 resilient stocks with low risk scores as a reference point.
- If dependable finances matter most, focus on businesses with sturdier balance sheets by scanning the list of solid balance sheet and fundamentals (10 results) for ideas that may merit a closer look.
- If you are hunting for mispriced quality, narrow the universe to compelling value situations by running through our hand picked 14 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com