
Is Materion (MTRN) Fully Priced On Record Earnings And Higher Guidance?
Materion (MTRN) is back in focus after reporting record third quarter value added sales and adjusted earnings per share of $1.93, topping Wall Street expectations while full year guidance moved higher.
Materion’s latest report landed after an already strong run, with the share price up 76.95% year to date and a 1 year total shareholder return of 104.65% at a last close of $227.43. The stock has pulled back sharply with a 30 day share price return of down 27.14% and a 90 day move of down 23.44%, even as recent earnings, a fresh Q3 earnings call and a reaffirmed quarterly dividend have kept investor attention on how much of that longer term momentum, including a 5 year total shareholder return of 151.86%, is still being priced in.
Compare Materion’s earnings breakout with a curated set of peers by scanning 19 high quality undiscovered gems that share strong fundamentals but have yet to gain the same spotlight.
Materion’s operations look strong on paper, yet the share price has sprinted ahead and then stumbled hard in just a few weeks. Is this business now attractively valued, or still priced for perfection?
Most Popular Narrative: 25% Undervalued
Materion’s most followed valuation narrative pegs fair value at $303.75. This means the $227.43 last close sits at a sizable discount while still assuming a fairly optimistic profit path.
Accelerating demand tied to AI related semiconductor, memory and data storage applications, reflected in recent double digit growth in semiconductor sales and high performance memory and data storage linked to AI, supports the view that Materion can keep growing value added revenue from Electronic Materials and related offerings as these programs are fulfilled.
See why 11 investors see Materion as 25% undervalued.
Result: Fair Value of $303.75 (UNDERVALUED)
Still, the Materion story can break if AI linked orders or defense and space programs pause, or if the current premium P/E multiple compresses sharply.
Find out about the key risks to this Materion narrative.
Another View: Materion And Rich Earnings Multiples
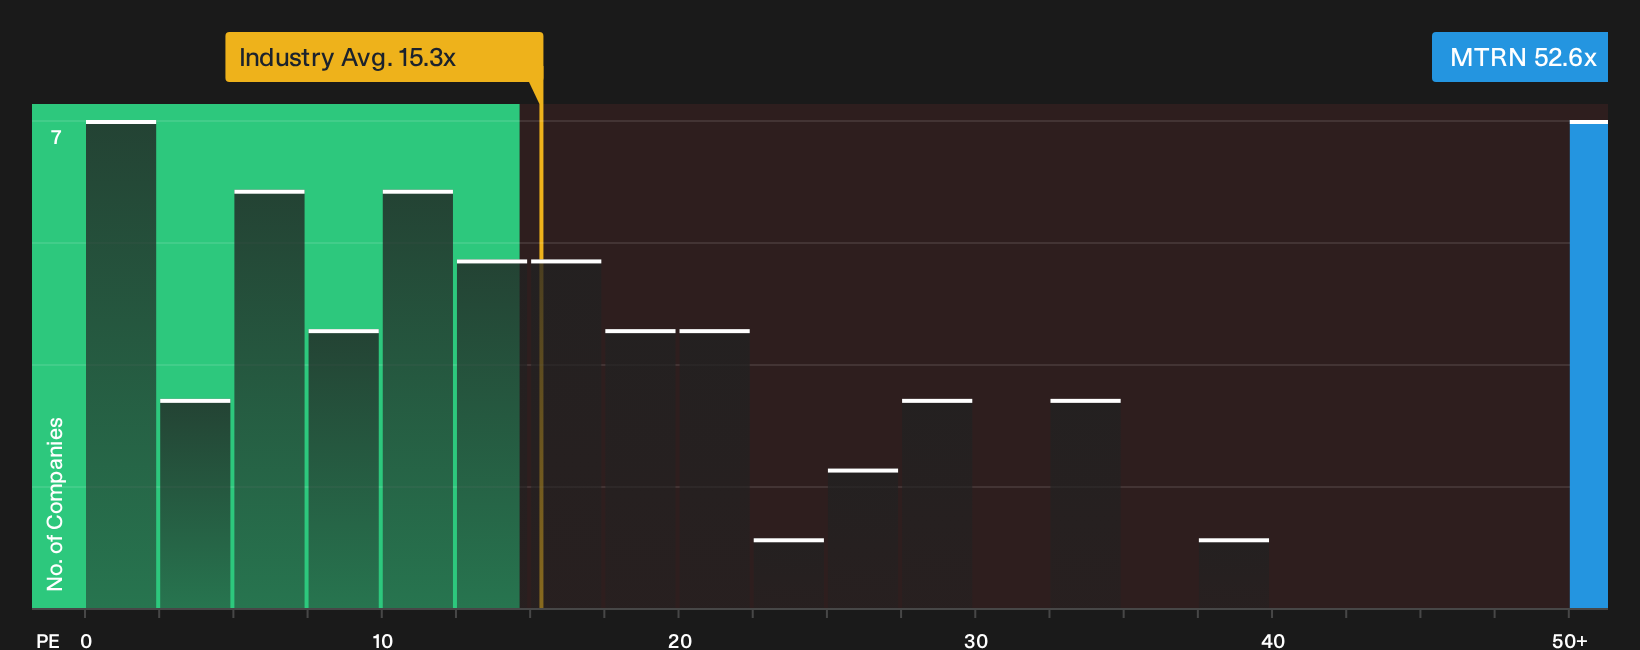
The story changes if you swap the SWS DCF model for a simple earnings multiple. Materion trades on a P/E of 52.6x, compared with a fair ratio of 28.4x, US Metals and Mining on 15.8x and peers on 25.6x. That is a steep premium. Is the market leaving much room for mistakes?
To see how those valuation gaps could matter when sentiment shifts, review the detailed earnings multiple breakdown in See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Materion is clearly mixed, so move quickly from headline opinions to hard numbers by weighing both the upside and the pressure points in the 4 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Materion?
If Materion has you rethinking what is already priced into your portfolio, now is the moment to line up a fresh set of opportunities before the crowd moves in.
- Target stronger potential upside by scanning quality candidates on the 35 high quality undervalued stocks that pair solid fundamentals with discounted market prices.
- Prioritize resilience and capital protection by reviewing the 30 resilient stocks with low risk scores where financial strength and lower risk scores help narrow your watchlist.
- Anchor your income plan by assessing payout heavyweights through the 4 dividend fortresses that focus on higher yield companies built for regular distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com