
We're Not Worried About TOMO Holdings' (HKG:6928) Cash Burn
We can readily understand why investors are attracted to unprofitable companies. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. Nonetheless, only a fool would ignore the risk that a loss making company burns through its cash too quickly.
So, the natural question for TOMO Holdings (HKG:6928) shareholders is whether they should be concerned by its rate of cash burn. For the purposes of this article, cash burn is the annual rate at which an unprofitable company spends cash to fund its growth; its negative free cash flow. Let's start with an examination of the business' cash, relative to its cash burn.
When Might TOMO Holdings Run Out Of Money?
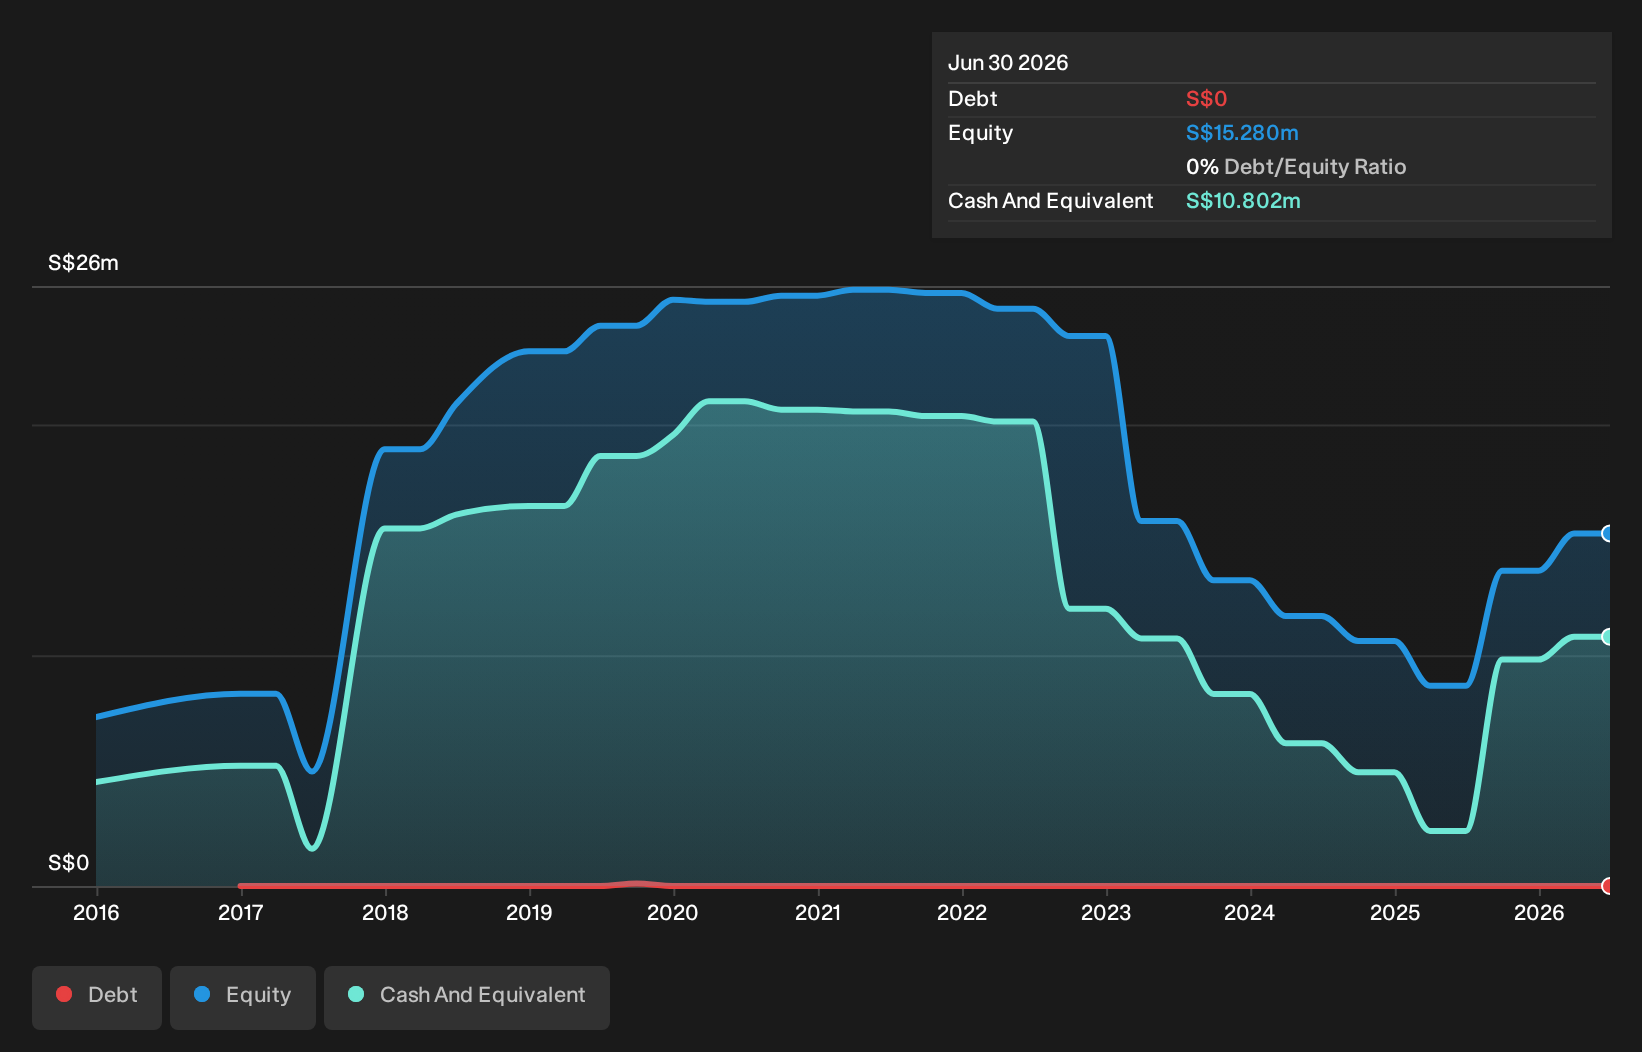
A company's cash runway is the amount of time it would take to burn through its cash reserves at its current cash burn rate. When TOMO Holdings last reported its June 2026 balance sheet in September 2026, it had zero debt and cash worth S$11m. Importantly, its cash burn was S$852k over the trailing twelve months. That means it had a cash runway of very many years as of June 2026. While this is only one measure of its cash burn situation, it certainly gives us the impression that holders have nothing to worry about. Depicted below, you can see how its cash holdings have changed over time.
Check out our latest analysis for TOMO Holdings
How Is TOMO Holdings' Cash Burn Changing Over Time?
Whilst it's great to see that TOMO Holdings has already begun generating revenue from operations, last year it only produced S$2.7m, so we don't think it is generating significant revenue, at this point. Therefore, for the purposes of this analysis we'll focus on how the cash burn is tracking. The 78% reduction in its cash burn over the last twelve months may be good for protecting the balance sheet but it hardly points to imminent growth. TOMO Holdings makes us a little nervous due to its lack of substantial operating revenue. We prefer most of the stocks on this list of stocks that analysts expect to grow.
How Easily Can TOMO Holdings Raise Cash?
While we're comforted by the recent reduction evident from our analysis of TOMO Holdings' cash burn, it is still worth considering how easily the company could raise more funds, if it wanted to accelerate spending to drive growth. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Commonly, a business will sell new shares in itself to raise cash and drive growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
TOMO Holdings' cash burn of S$852k is about 2.8% of its S$30m market capitalisation. That means it could easily issue a few shares to fund more growth, and might well be in a position to borrow cheaply.
How Risky Is TOMO Holdings' Cash Burn Situation?
It may already be apparent to you that we're relatively comfortable with the way TOMO Holdings is burning through its cash. For example, we think its cash runway suggests that the company is on a good path. And even its cash burn relative to its market cap was very encouraging. After taking into account the various metrics mentioned in this report, we're pretty comfortable with how the company is spending its cash. Separately, we looked at different risks affecting the company and spotted 4 warning signs for TOMO Holdings (of which 1 is a bit concerning!) you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.