
Why Inspire Medical Systems Stock Is In Focus After Earnings Beat And Reimbursement Update
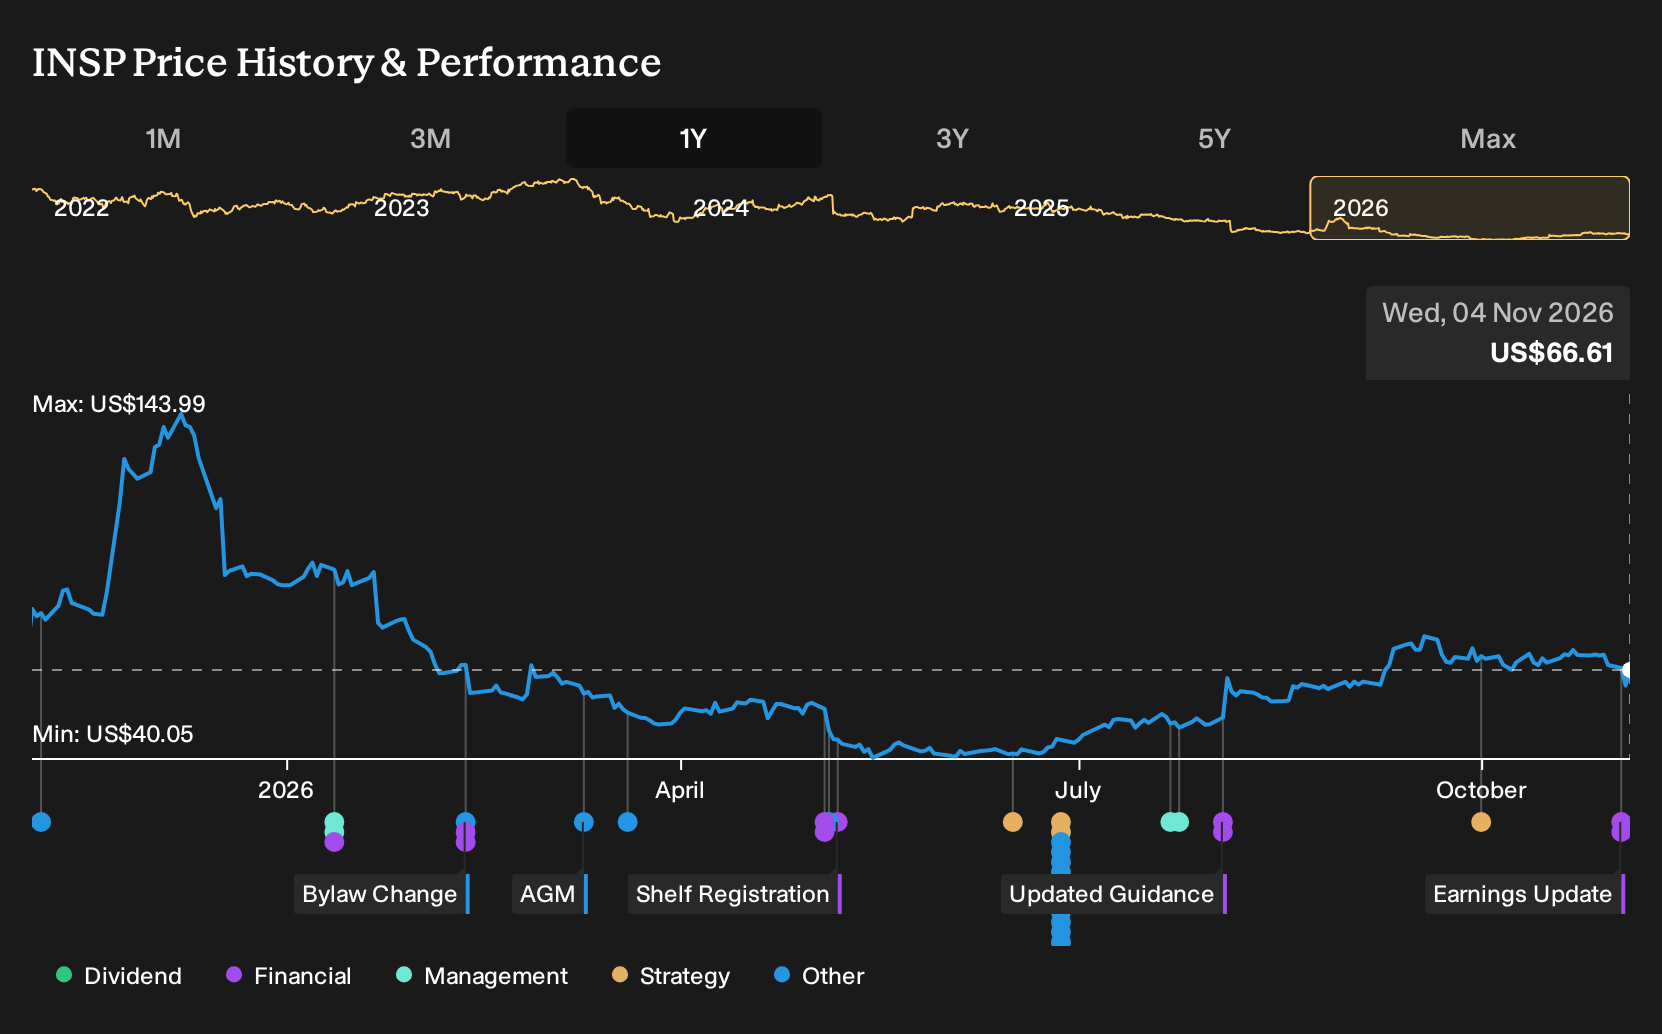
- Inspire Medical Systems reported third quarter 2026 sales of US$206.7 million and a net loss of US$24.4 million, while tightening full year revenue guidance to a range of US$850 million to US$860 million and projecting diluted EPS between a loss of US$0.36 and a loss of US$0.10.
- Management paired weaker year over year revenue and a swing to losses with billing and coding updates, including a planned Category I CPT code and reimbursement clarity intended to ease current disruption and support more consistent access to Inspire therapy over time.
- The focus now turns to how Inspire Medical Systems' investment narrative absorbs a quarter of losses alongside tighter, clarified 2026 guidance.
Compare Inspire Medical Systems' latest guidance with peers by scanning a curated list of healthcare stocks showing resilient fundamentals through earnings resets in the list of solid balance sheet and fundamentals (25 results).
Inspire Medical Systems Investment Narrative Recap
To stay invested in Inspire Medical Systems, you need to believe that the sleep apnea therapy franchise can work through coding friction and WISeR related disruption and still support consistent implant activity. The third quarter showed that reality is messy. Sales of US$206.7 million were lower than a year ago and the company moved from a profit to a loss of US$24.4 million.
The key short term catalyst is clearer reimbursement and coding. Management is trying to address this through new CPT pathways and payer education. The biggest immediate risk is that coding complexity and legal scrutiny keep implant volumes and net margins under pressure for longer, even with narrowed 2026 guidance of US$850 million to US$860 million and projected diluted EPS still in loss territory.
The guidance update is the announcement that matters most right now. Inspire Medical Systems tightened its 2026 revenue outlook to US$850 million to US$860 million and projected diluted EPS between a loss of US$0.36 and a loss of US$0.10. That range frames what management currently considers achievable while it works through reimbursement and operational headwinds.
For you as a shareholder, this guidance becomes the reference point to judge execution on coding clean up, Inspire V roll out and adoption tools such as SleepSync and Project Horizon. Any future update on the Category I CPT code effective January 1, 2028 or on proposed 2027 Medicare facility reimbursement will feed directly into how credible this earnings path looks versus the ongoing risks around procedure growth and one off financial items.
Inspire Medical Systems' narrative uses analyst assumptions that revenues will reach US$983.3 million and earnings will reach US$76.9 million by 2029. These figures are based on forecast revenue growth of 3.0% annually and a projected earnings decline of US$58.1 million from current earnings of US$135.0 million.
Uncover why Inspire Medical Systems' fair value appears to be generally consistent with its current price.
Exploring Other Perspectives
One alternate view on Inspire Medical Systems leans heavily into reimbursement risk. The most bearish analysts were only penciling in about US$947.1 million of revenue and US$29.0 million of earnings by 2029 before this earnings miss and guidance tweak. That is a far more pessimistic story. Use it as a prompt to test your own assumptions and explore multiple angles.
Explore 3 other Inspire Medical Systems fair value estimates, including one that suggests as much as 40% downside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Inspire Medical Systems research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Inspire Medical Systems. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Inspire Medical Systems' overall financial health at a glance.
Looking For More Investment Ideas Beyond Inspire Medical Systems?
Once you have a view on Inspire Medical Systems, it can help to cross check that thesis against other companies with different risk and return profiles. The Simply Wall St Screener is built for exactly this kind of comparison, letting you move from a single stock story to a wider watchlist that matches how you like to invest.
- If capital preservation is front of mind, consider starting with a set of companies filtered for balance sheet strength using the 31 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable entry point, a curated pool of fundamentally sound businesses trading below their estimated worth in the 34 high quality undervalued stocks can sharpen your shortlist.
- Those who enjoy finding earlier stage opportunities can scan through a focused collection of smaller, financially robust stocks by working through the 7 elite penny stocks with strong financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com