
Viking Holdings (VIK) Lands ETF Interest On A Valuation Story Still In Focus
Viking Holdings (VIK) drew fresh attention after the First Trust WCM International Equity ETF initiated a new position worth about US$44.1 million, giving the cruise operator a 2.61% weight in the fund.
That ETF move landed after a choppy stretch for Viking Holdings, where a 12.51% 30 day share price return and 5.40% 7 day gain helped offset a 14.14% decline over 90 days. The 1 year total shareholder return of 59.44% points to momentum still skewed toward the longer term trend.
Scan how Viking Holdings compares to other cruise and travel operators by reviewing a hand picked 34 high quality undervalued stocks that may also be catching institutional attention.
After a sharp rebound, fresh ETF money and a 1 year return near 60% set the stage for a tougher question on Viking Holdings. Is the meaningful upside still in front of you, or mostly in the rear view mirror as valuation tightens?
Most Popular Narrative: 18% Undervalued
Viking Holdings closed at $91.17 against a narrative fair value estimate of about $110.81, leaving a sizable valuation gap that depends on the business continuing to execute on premium cruise demand and disciplined expansion.
Advanced bookings for core products remain exceptionally strong, with 96% of 2025 capacity and 55% of 2026 capacity already sold at higher rates. This indicates durable repeat demand and allows for mid-single-digit pricing growth that directly benefits company earnings and net margins. Consistent investment in a standardized, modern, and energy-efficient fleet across ocean and river segments enables tight operational control, better shipyard pricing, and scalable cost efficiencies. These factors are expected to support ongoing margin expansion and improved long-term profitability.
See why 9 investors see Viking Holdings as 18% undervalued.
Result: Fair Value of $110.81 (UNDERVALUED)
Still, Viking Holdings leans heavily on affluent older travelers, and rising environmental and fuel related costs could pressure earnings if pricing power or demand softens.
Find out about the key risks to this Viking Holdings narrative.
Another View: Viking Holdings On Earnings Multiples
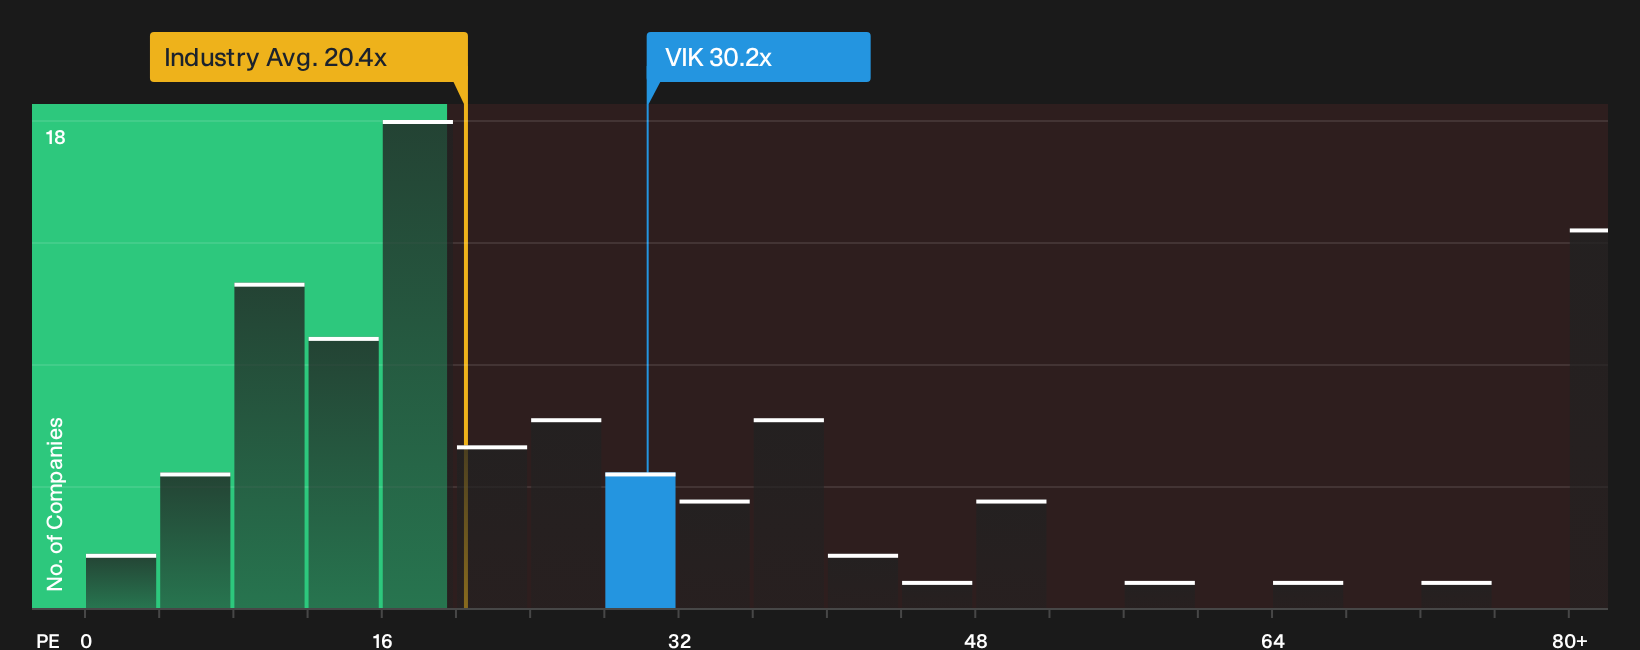
There is a different story when you look at Viking Holdings using its P/E. The shares trade at about 30.2x earnings compared with 20.4x for the US Hospitality group and 14.8x for closer peers, while the fair ratio sits nearer 31.7x.
That leaves the stock priced well above the sector and peer averages, yet not far from the fair ratio. This suggests less obvious mispricing and more debate about how much future growth is already reflected in today’s tag.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Viking Holdings story so far. Use the numbers, charts, and competing views to move quickly and build your own thesis, starting with 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Viking Holdings?
If Viking Holdings has sharpened your focus, do not stop here. Broaden your watchlist using data driven screeners built to spotlight clear, differentiated opportunities.
- Target income first by scanning companies with resilient cash flows and higher yields through a focused 5 dividend fortresses.
- Zero in on financial strength using a list of solid balance sheet and fundamentals (25 results) that helps you filter for sturdier balance sheets when quality really matters.
- Hunt for potential future leaders hiding in plain sight with a curated 19 high quality undiscovered gems before the wider market pays attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com