
Is Otter Tail (OTTR) Below Fair Value On Weak Q3 Earnings And Tighter Guidance?
Otter Tail (OTTR) is back in focus after third quarter earnings missed analyst expectations, management tightened full year guidance, and the board confirmed its regular dividend despite ongoing pressure in the Plastics segment.
At a share price of $83.82, Otter Tail has given investors a 1-year total shareholder return of 4.10%, while the share price return is 2.91% year to date. Recent momentum has faded, with the 30-day share price return down 5.20% and the 90-day move down 9.92%. Weaker Plastics earnings, a tighter guidance range, and a fresh dividend affirmation have reset expectations around both growth potential and risk.
Scan how Otter Tail compares to other utilities under earnings pressure by running through our hand picked 31 resilient stocks with low risk scores list that emphasizes resilience over short term noise.
Otter Tail now trades below recent highs after the Plastics hit and guidance tweak. Does that reset create a fair entry today or argue for waiting until the valuation math looks cleaner?
Most Popular Narrative: 7% Undervalued
Otter Tail's most followed valuation story points to a fair value of $90.50 using a 7.24% discount rate, compared with the recent $83.82 close. This suggests a modest undervaluation gap that depends on how the utility plan and Plastics reset develop over the next few years.
Continued execution of Otter Tail’s US$1.9b electric capital program, with a reaffirmed 10% rate base CAGR and nearly 1:1 conversion of that rate base growth into utility earnings, is expected to support future EPS.
Use of cash generated by Manufacturing and Plastics, together with an equity layer in the low 60% range and over US$600 million of liquidity at mid 2026, and with no external equity issuance expected through at least 2030, is expected to support funding of the utility capex plan while aiming to protect EPS and return on equity.
See why 3 investors see Otter Tail as 7% undervalued.
Result: Fair Value of $90.50 (UNDERVALUED)
Still, the PVC pipe settlements and the guided reset in Plastics earnings give Otter Tail a couple of pressure points that could quickly challenge this undervalued story.
Find out about the key risks to this Otter Tail narrative.
Another View On Otter Tail’s Valuation
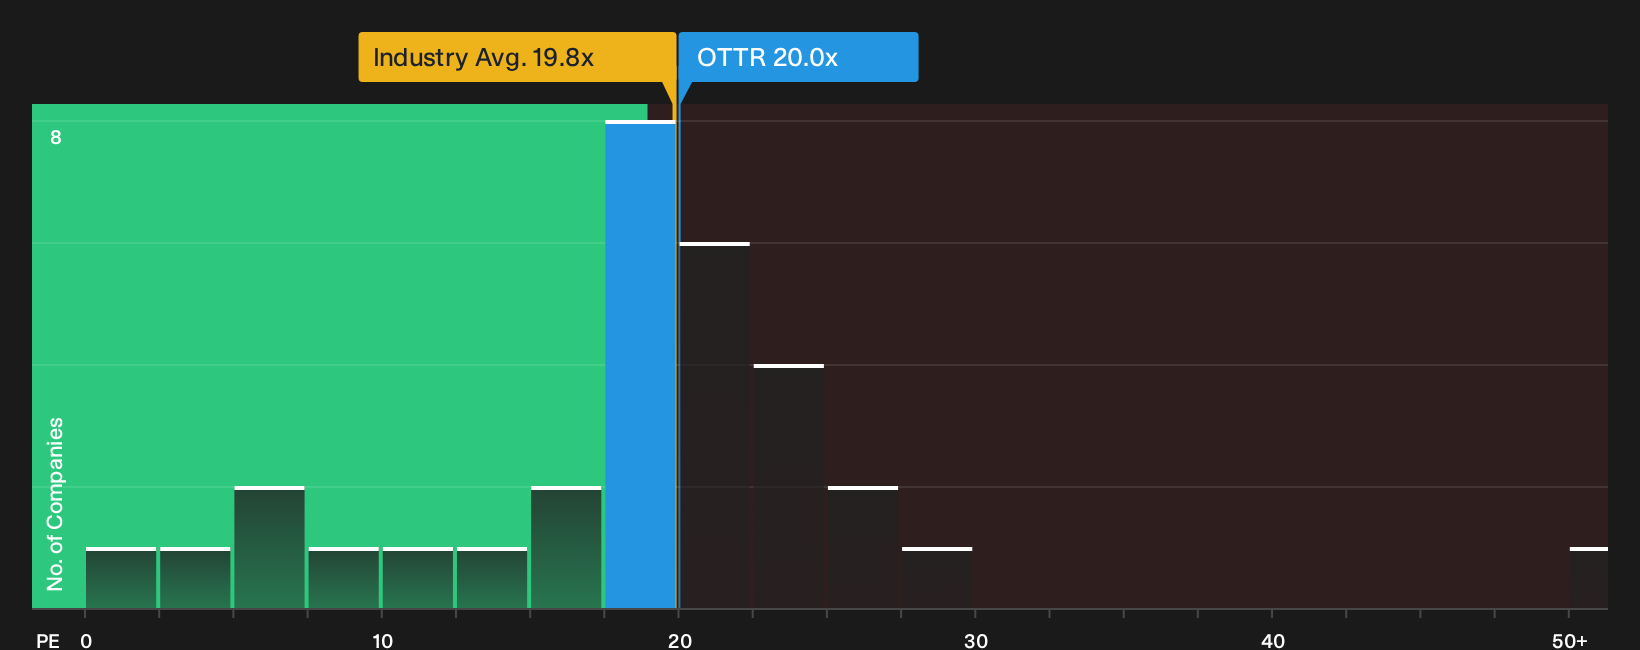
The popular story has Otter Tail looking about 7% undervalued at a fair value of $90.50. The P/E picture says something different. At roughly 20x earnings, OTTR trades above its fair ratio of 16.7x and slightly above the US Electric Utilities average of 19.8x, while still below peers at 22.4x. That mix points to limited cushion if sentiment sours, so which story do you trust more: the fair value gap or the higher than fair ratio P/E?
If you lean on this ratio view, it is worth seeing what a full breakdown of earnings, peers and the fair ratio suggests about where the share price could migrate over time: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Otter Tail’s value story make this a judgment call. Move quickly to test the numbers yourself and weigh both the downside and upside that others are flagging through the 1 key reward and 5 important warning signs.
Looking for more investment ideas beyond Otter Tail?
If Otter Tail has your attention but you want a wider watchlist, now is the moment to line up fresh ideas that could fit your portfolio next.
- Target dependable cash generators by scanning companies with strong yields and balance sheet support through the 5 dividend fortresses.
- Hunt for mispriced quality by reviewing the 34 high quality undervalued stocks that pair healthy financials with potential upside.
- Consider ways to future proof your portfolio by checking a list of solid balance sheet and fundamentals (25 results) so short term volatility does not dictate your long term plans.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com