
Earnings Update May Test The Case For Scotts Miracle Gro Stock
- Scotts Miracle-Gro reported fourth quarter sales of US$302.9 million and a net loss of US$121.9 million, alongside full-year sales of US$3.29 billion and net income of US$103.9 million.
- The Board also approved a cash dividend of US$0.66 per share, indicating a continued capital return decision despite the quarterly loss profile.
- Investors may now evaluate how Scotts Miracle-Gro's investment narrative could be influenced by full-year earnings that include lower annual net income.
Scan beyond Scotts Miracle-Gro's mixed earnings and dividend decision by comparing its profile with a curated 34 high quality undervalued stocks that combines strong cash flows and balance sheet strength.
Scotts Miracle-Gro Investment Narrative Recap
To own Scotts Miracle-Gro, you need to believe the core lawn, garden and indoor growing categories stay relevant while the product mix keeps tilting toward more natural, branded solutions and e-commerce channels. The latest results showed a quarterly loss alongside positive full-year earnings, so the near term story still revolves around execution rather than clean, straight line progress.
The key short term swing factor is whether cost savings, portfolio clean up and retail sell through can keep full year profitability intact even when a single quarter is weak. The main risk remains financial flexibility. Debt is not well covered by operating cash flow, so any stumble in seasonal demand or weather sensitive volumes can tighten room to invest.
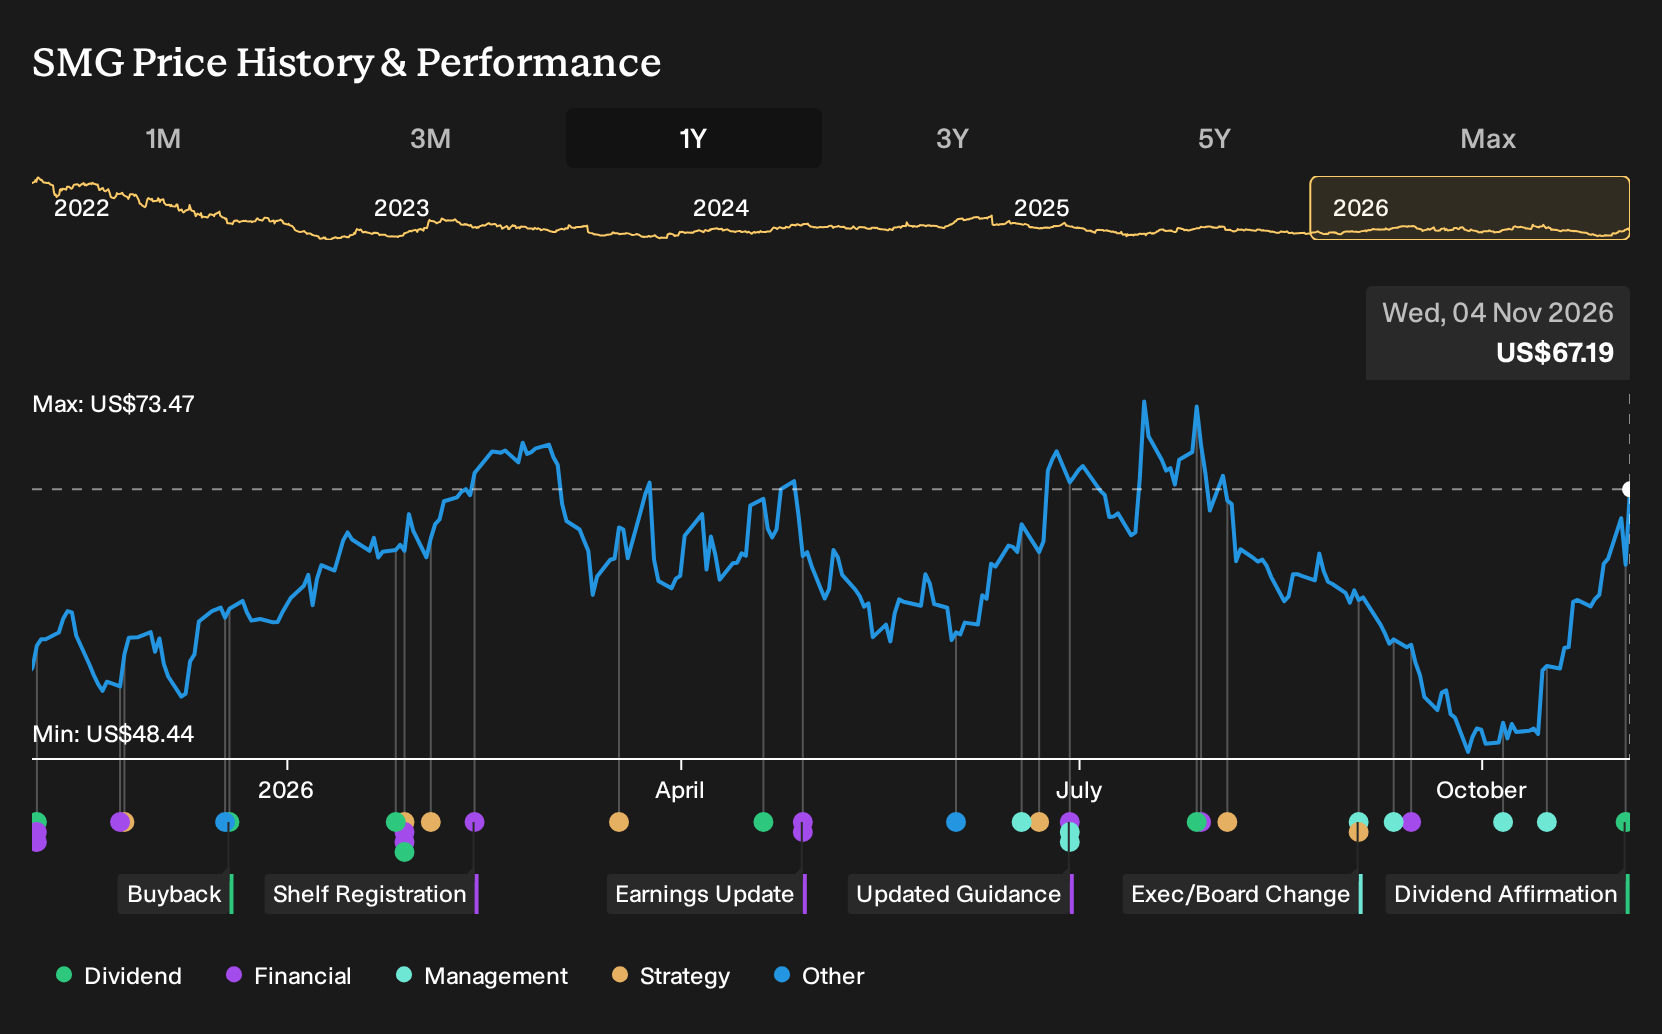
The most relevant update for that thesis is the Board’s decision on a US$0.66 per share dividend, coming right after a quarter with a US$121.9 million loss and lower full year net income of US$103.9 million. That indicates management is keeping cash returns in place while still working through higher leverage and uneven quarterly profitability.
For you as a shareholder, the question is whether that payout fits comfortably alongside the transformation plan and the goal of steadier earnings. Analysts flag that the dividend is not well covered by earnings and that debt coverage by operating cash flow is weak. As a result, the dividend policy now sits directly in the path of both the main catalyst and the main risk.
Scotts Miracle-Gro's narrative projects US$3.5b revenue and US$348.1 million earnings by 2028. This assumes revenue decreases by 0.8% per year and an earnings increase of about US$295 million from US$53.1 million today.
Uncover why Scotts Miracle-Gro's fair value indicates a 12% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on cost savings as the key catalyst for Scotts Miracle-Gro. The most optimistic analysts were modeling revenue of about US$3.6b and earnings of US$277.1 million by 2029, with a higher implied P/E. Those projections pre-date this earnings and dividend update, so you may see those viewpoints shift.
Explore 3 other Scotts Miracle-Gro fair value estimates, including one that suggests as much as 44% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Scotts Miracle-Gro research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Scotts Miracle-Gro. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Scotts Miracle-Gro's overall financial health at a glance.
Looking For More Ideas Beyond Scotts Miracle-Gro?
If you want to cross-check your view on Scotts Miracle-Gro with other opportunities, the Simply Wall St screener can help you quickly filter the market by quality, balance sheet strength and risk profile so you are not relying on a single stock to carry your thesis.
- If you want potential upside with a margin of safety, start with a curated group of high quality businesses using the 34 high quality undervalued stocks.
- For investors who prioritize resilient finances, focus on companies with stronger balance sheets and fundamentals through the list of solid balance sheet and fundamentals (25 results).
- If you prefer steadier profiles over headline excitement, concentrate on relatively lower risk opportunities using the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com