
Learn Why The Bull Case For Sotera Health Stock Could Change Following Earnings Beat
- Sotera Health reported Q3 2026 revenue of US$324.89 million and net income of US$58.39 million, with earnings per share of US$0.20. The company also reaffirmed full year 2026 revenue guidance of US$1.233b to US$1.250b and provided new Q4 guidance for about 6% constant currency revenue growth.
- The business combined stronger contributions from Sterigenics and Nelson Labs with a Moody's credit rating upgrade, which pointed to improved balance sheet strength and financial flexibility. Management continued to address softer European medical device demand and ongoing ethylene oxide related litigation.
- The focus now turns to how Sotera Health's reaffirmed full year outlook shapes the existing investment narrative on capacity, risk, and cash generation.
Sotera Health Investment Narrative Recap
Owning Sotera Health means believing that demand for outsourced sterilization and lab testing can support consistent revenue, while heavy spend on ethylene oxide controls and new capacity eventually feeds earnings and cash generation. The reaffirmed 2026 outlook and Q4 guide for roughly 6% constant currency growth keep that core idea intact and do not redefine it.
For the near term, the key swing factor is how quickly sterilization and testing volumes absorb the large 2026 capex program without squeezing free cash flow. This is particularly important while ethylene oxide litigation and European med device softness continue to affect the story. The latest update does not materially shift those risks or the main capacity driven catalyst.
The reaffirmed full year 2026 revenue outlook of US$1.233b to US$1.250b is the clearest touchpoint for the catalyst debate. It ties the current investment case for Sotera Health to management execution on bringing new sterilization and testing capacity online while keeping EBITDA and net income aligned with earlier expectations.
That same guidance also frames the main watchpoints. Investors can track whether Sterigenics and Nelson Labs volumes, pricing, and mix offset Nordion lumpiness, higher emissions related spending, and any ethylene oxide related legal or regulatory outcomes that might pressure margins or limit ethylene oxide volumes. All of these factors feed directly into cash generation and leverage trends.
What Sotera Health's Long Range Forecasts Assume
Sotera Health's long range analyst model leans on a steady 5.8% yearly revenue growth rate over the next three years, paired with a sharp improvement in profitability from 13.4% margins today to 22.3% by 2029. That profit jump is anchored in consensus earnings moving from US$163.5 million today to US$321.4 million by the 2029 forecast horizon, with a wide spread between the most optimistic and most cautious estimates. The step up in earnings is material in absolute terms, more than US$150 million of extra profit, and implies that recent capital spending and emissions projects eventually support higher free cash conversion.
Those same assumptions also rely on a modest 0.45% annual increase in the share count, which means a larger earnings pool needs to clear only a slightly bigger base of shares to support per share metrics. Analysts are effectively underwriting a future where Sotera Health carries a P/E of 26.5x on those 2029 earnings rather than the current 31.8x multiple, and yet still see that setup as consistent with their existing price targets. The comparison with an industry P/E of 44.4x gives readers a reference point for how much earnings power the market might already be factoring into today’s share price.
On the top line, the consensus case calls for revenues of about US$1.4b and earnings of US$321.4 million by 2029. That endpoint links directly back to the 5.8% annualized growth rate built into the model. For Sotera Health, the key question is not whether a single quarter matches those numbers, but whether sterilization and lab testing volumes, pricing, and mix across Sterigenics, Nordion, and Nelson Labs can support that scale of earnings while the firm continues to deal with ethylene oxide regulation and litigation costs.
Sotera Health's narrative projects US$1.4b revenue and US$321.4 million earnings by 2029. This rests on 5.8% yearly revenue growth and an earnings increase of roughly US$158 million from current earnings of US$163.5 million.
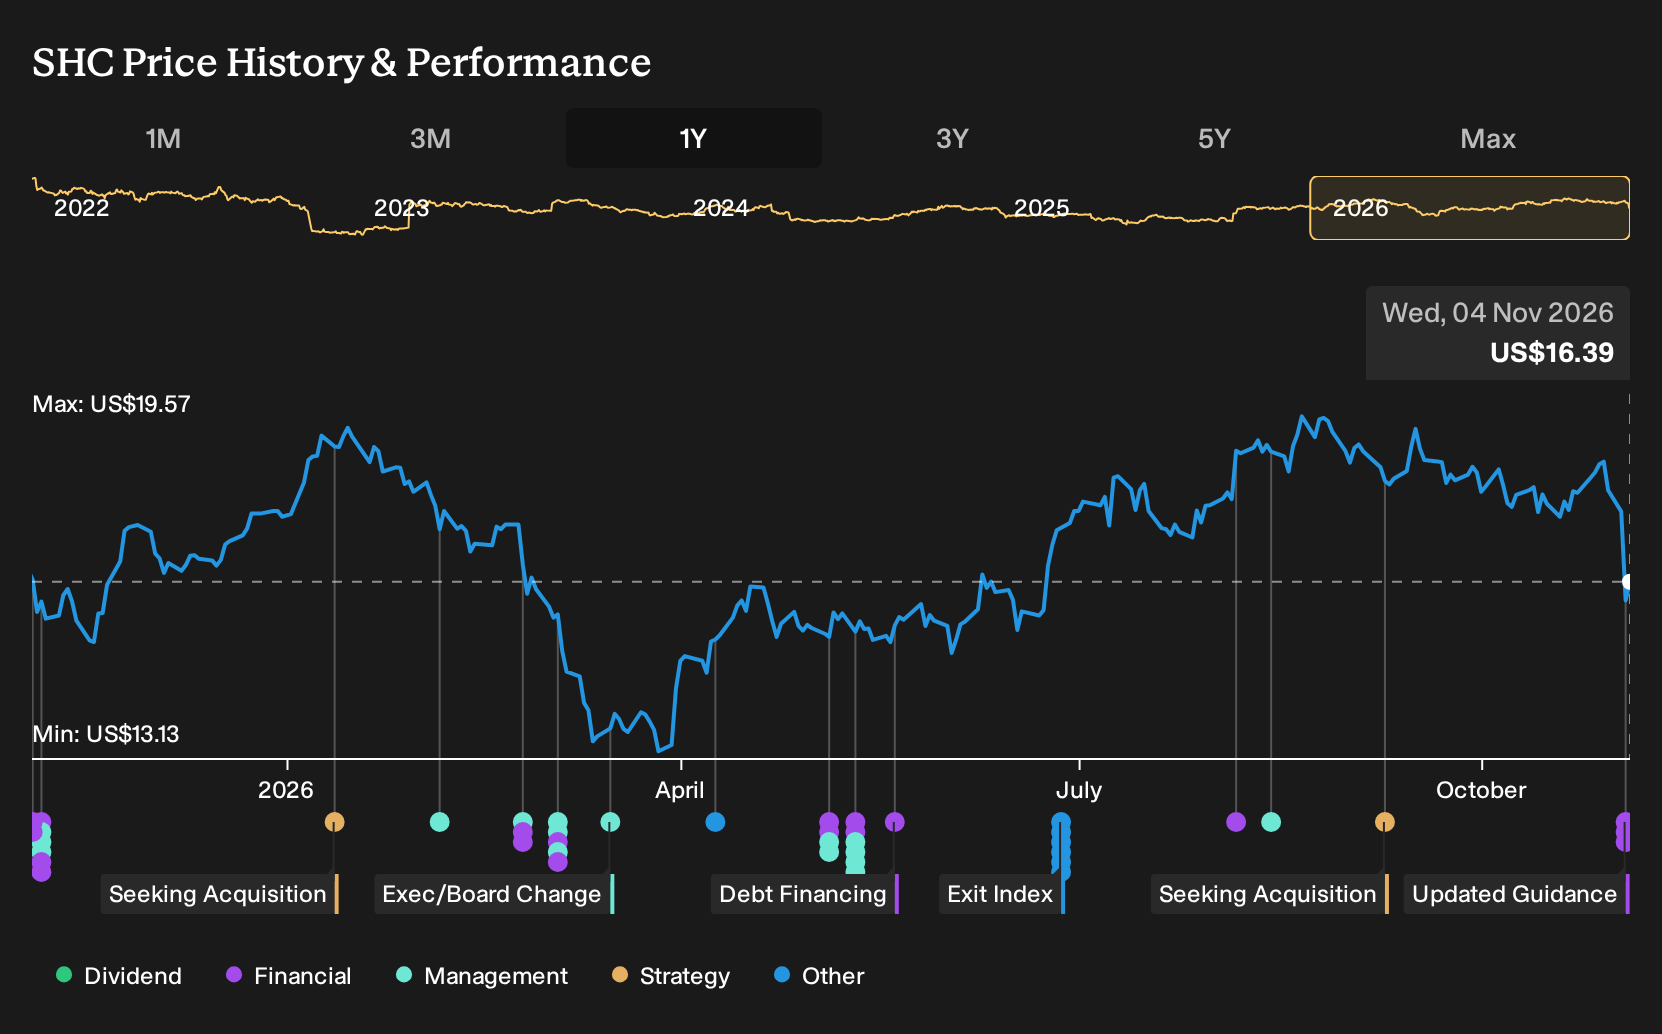
Uncover why Sotera Health's fair value indicates a 39% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on cash generation rather than just Sotera Health revenue growth. The most optimistic analysts were penciling in about US$1.5b of sales and US$370.2 million of earnings by 2029 before this Q3 beat and 6% Q4 guide. That outlook is more upbeat than consensus and could shift again as new information lands.
Explore another Sotera Health fair value estimate, including one that suggests as much as 145% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so rely on your own analysis.
- A great starting point for your Sotera Health research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Sotera Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sotera Health's overall financial health at a glance.
Looking for more Sotera Health style investment ideas?
If the Sotera Health story has sharpened your view on risk, cash flow, and balance sheet strength, you can apply that same perspective across the wider market using the Simply Wall St Screener. It is a practical way to surface other businesses that fit the kind of profile you are trying to build into your portfolio.
- For investors who want upside potential grounded in fundamentals, scan a curated 19 high quality undiscovered gems that may not yet be widely followed but already show solid financial quality.
- If resilience matters most to you, filter for a list of solid balance sheet and fundamentals (25 results) and focus on companies with cleaner leverage profiles and sturdier financial positions.
- Income focused readers can zero in on cash return potential by reviewing a hand picked 5 dividend fortresses that screens for higher yielding payouts backed by underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com