
Learn Why The Bull Case For Parker Hannifin Stock Could Change Following Air Dryer Market Growth
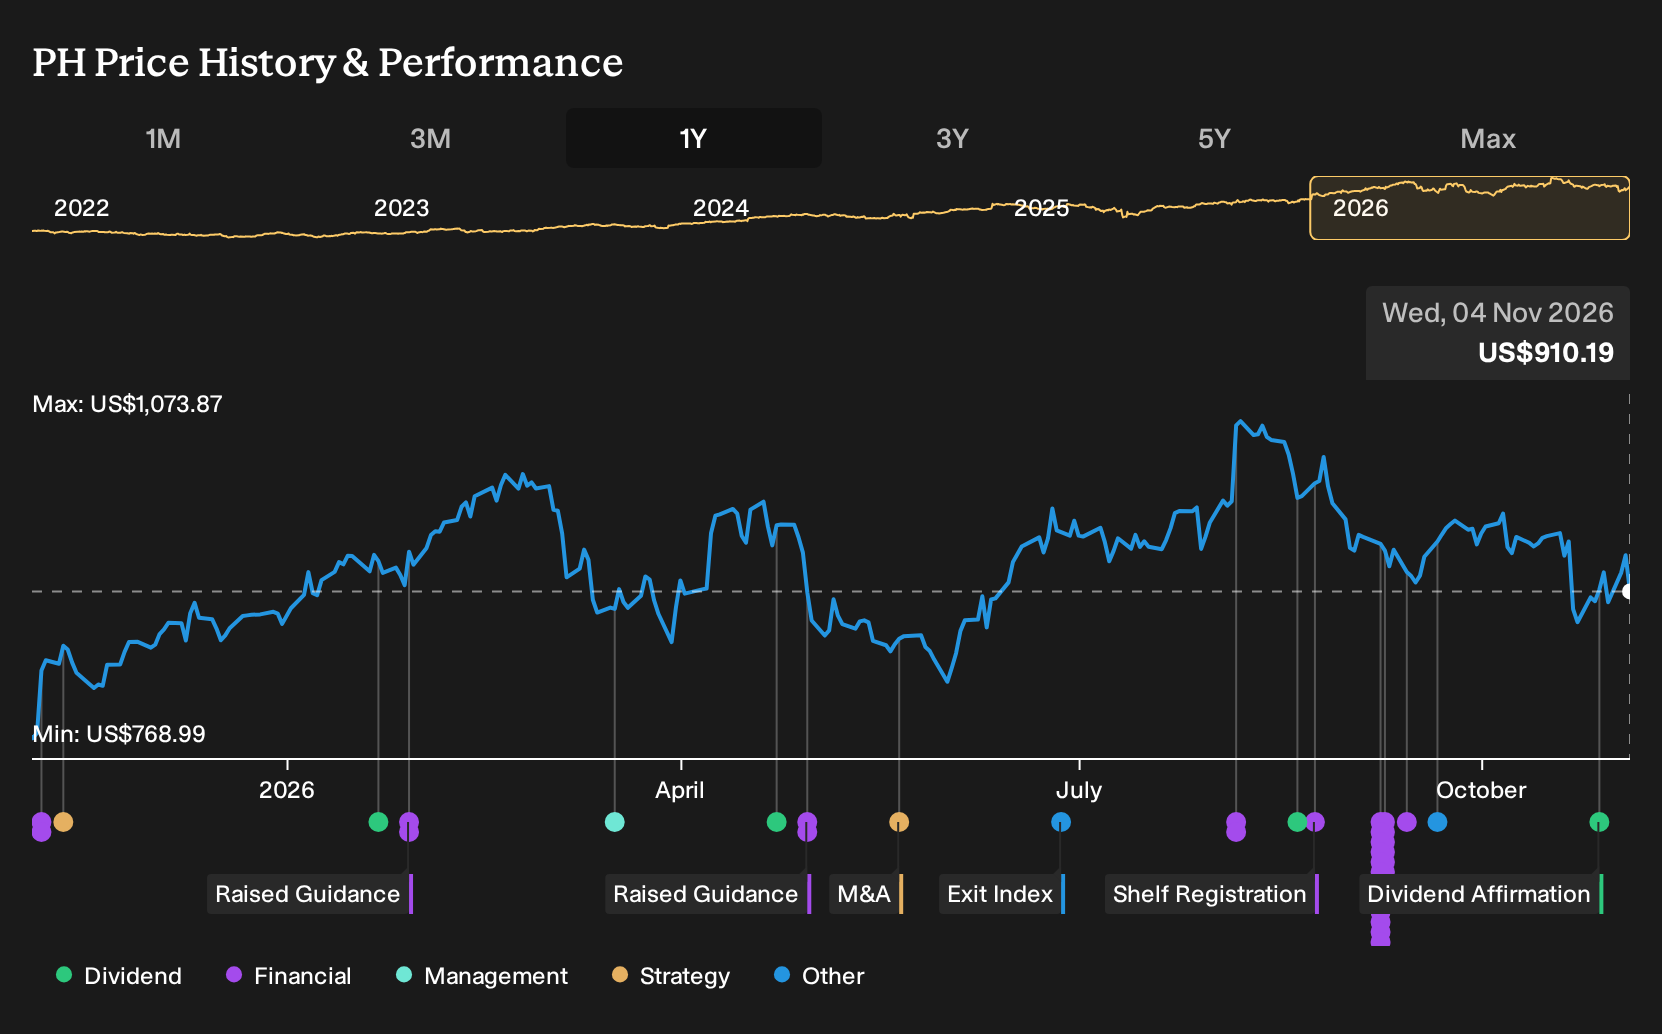
- Parker-Hannifin confirmed a regular quarterly cash dividend of US$2.00 per share, paid on 4 December 2026 to investors of record on 13 November, extending its pattern of returning cash to shareholders.
- The firm was also highlighted as a key player in the high-efficiency air dryer market, where smart monitoring and energy-optimized systems are becoming central to industrial spending decisions.
- We will now look at how Parker-Hannifin's investment narrative is shaped by its role in high efficiency air dryer technologies.
Scan 41 power grid technology and infrastructure stocks to find other industrial players tied into the same push for efficient, electrified infrastructure that is shaping Parker-Hannifin's air dryer and dividend story.
Parker-Hannifin Investment Narrative Recap
To own Parker-Hannifin, you need to believe its mix of motion control, aerospace and filtration can keep generating solid cash even if organic growth stays modest. The key near term swing factor is how well industrial orders hold up, because muted demand would weigh on revenue and make its premium P/E harder to justify.
The biggest risk is that expectations for earnings compounding stay high while net margins and free cash flow already reflect years of efficiency work. The fresh dividend affirmation is more a confirmation of balance sheet confidence than a real catalyst, and does not materially change near term upside or downside drivers.
The recent decision to maintain a regular US$2.00 quarterly dividend is the announcement most tied to this story. It signals Parker-Hannifin still prioritises consistent cash returns, even as it leans into areas like high efficiency air dryers, automation and electrification that are drawing capital across industrial markets.
For you as a shareholder, that payout sits alongside existing catalysts like The Win Strategy margin targets, aerospace backlog and smart manufacturing demand. The trade off is clear: ongoing dividends return cash today, while any slowdown in orders, insider selling or pressure on a high P/E multiple remains a live risk for future returns.
Parker-Hannifin's current analyst script points to revenues of US$28.2b and earnings of US$5.2b by 2029, built on assumed annual top line expansion of 9.4% and an earnings step up of about US$1.6b from US$3.6b today.
Uncover why Parker-Hannifin's fair value indicates a 28% potential upside to its current price, a gap that could narrow quickly if sentiment shifts.
Exploring Other Perspectives
Some of the lowest ranked analysts focus on industrial demand risk rather than the dividend. They assume Parker-Hannifin reaches about US$26.9b of revenue and US$4.9b of earnings by 2029, which is more cautious than consensus. Those views were set before this dividend decision, so you may see those narratives shift.
Explore 3 other Parker-Hannifin fair value estimates, including one that suggests it could be worth just $955.62.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Parker-Hannifin research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Parker-Hannifin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Parker-Hannifin's overall financial health at a glance.
Looking For More Investment Ideas Beyond Parker-Hannifin?
Once you have a view on Parker-Hannifin, it can help to line it up against other opportunities so you see what you might be missing. The Simply Wall St Screener lets you filter the market by quality, balance sheet strength and income potential in a few quick steps.
- If you want companies that combine quality metrics with room for re rating, compare Parker-Hannifin against a curated 19 high quality undiscovered gems that may not yet be widely followed.
- If capital preservation matters most to you, weigh this stock alongside a 31 resilient stocks with low risk scores that screens for resilient businesses with steadier risk profiles.
- If income is your focus, put the Parker-Hannifin dividend in context by scanning a 5 dividend fortresses that concentrates on higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com