
How Investors May Respond To Grand Canyon Education (LOPE) Lower Revenue Outlook
- Grand Canyon Education reported Q3 2026 net income of US$43.01 million and diluted EPS of US$1.67, alongside 2.4% revenue growth and a slight revenue shortfall versus consensus.
- Management paired modest top line progress with a lowered revenue outlook due to softer traditional campus enrollments, while continuing share repurchases and planning four new hybrid campuses for 2027.
- We will now examine how Grand Canyon Education's lowered revenue outlook could reshape the existing investment narrative that is built around enrollment expansion.
Contrast Grand Canyon Education's enrollment driven story with a curated set of financially solid peers by scanning the list of solid balance sheet and fundamentals (24 results), which may handle growth slowdowns differently.
Grand Canyon Education Investment Narrative Recap
To stay invested in Grand Canyon Education, you need to be comfortable with an enrollment centered story that leans heavily on online and hybrid offerings while traditional campus demand looks softer. The recent quarter delivered higher net income and EPS alongside only 2.4% revenue growth and a trimmed revenue outlook, so in the near term the key swing factor is how enrollment trends evolve across formats.
The biggest immediate risk sits in weaker traditional campus intake layered on top of already pressured revenue per student and rising cost buckets such as benefits and technology. Management is still leaning into expansion plans and investments, which supports the long term narrative but keeps execution risk and margin pressure significant in the short run.
The most relevant update for this earnings print is management's plan to open four new hybrid campuses in 2027 while targeting more than 10% ground campus enrollment growth that fall. Paired with current online enrollment growth expectations of 6% to 7% in Q4, this reflects Grand Canyon Education focusing on formats where demand and employer alignment have been more supportive.
These commitments matter for catalysts because they shape how the service platform scales and how diversified enrollment becomes if traditional four year degree interest keeps softening. They also raise the execution bar. New sites, more healthcare pathways, and continued technology investment require upfront spending, so any stumble in enrollment or retention would make the current cost and legal risk profile more uncomfortable for shareholders.
Grand Canyon Education's current earnings sit at US$236.5 million, with analysts forecasting US$306.2 million by 2028 on expected revenue growth of 6.7% a year and projected 2028 revenue of US$1.3b. This implies an earnings increase of about US$69.7 million from today.
Uncover why Grand Canyon Education's fair value signals a 29% potential upside to its current price, a discount that could narrow quickly as expectations reset.
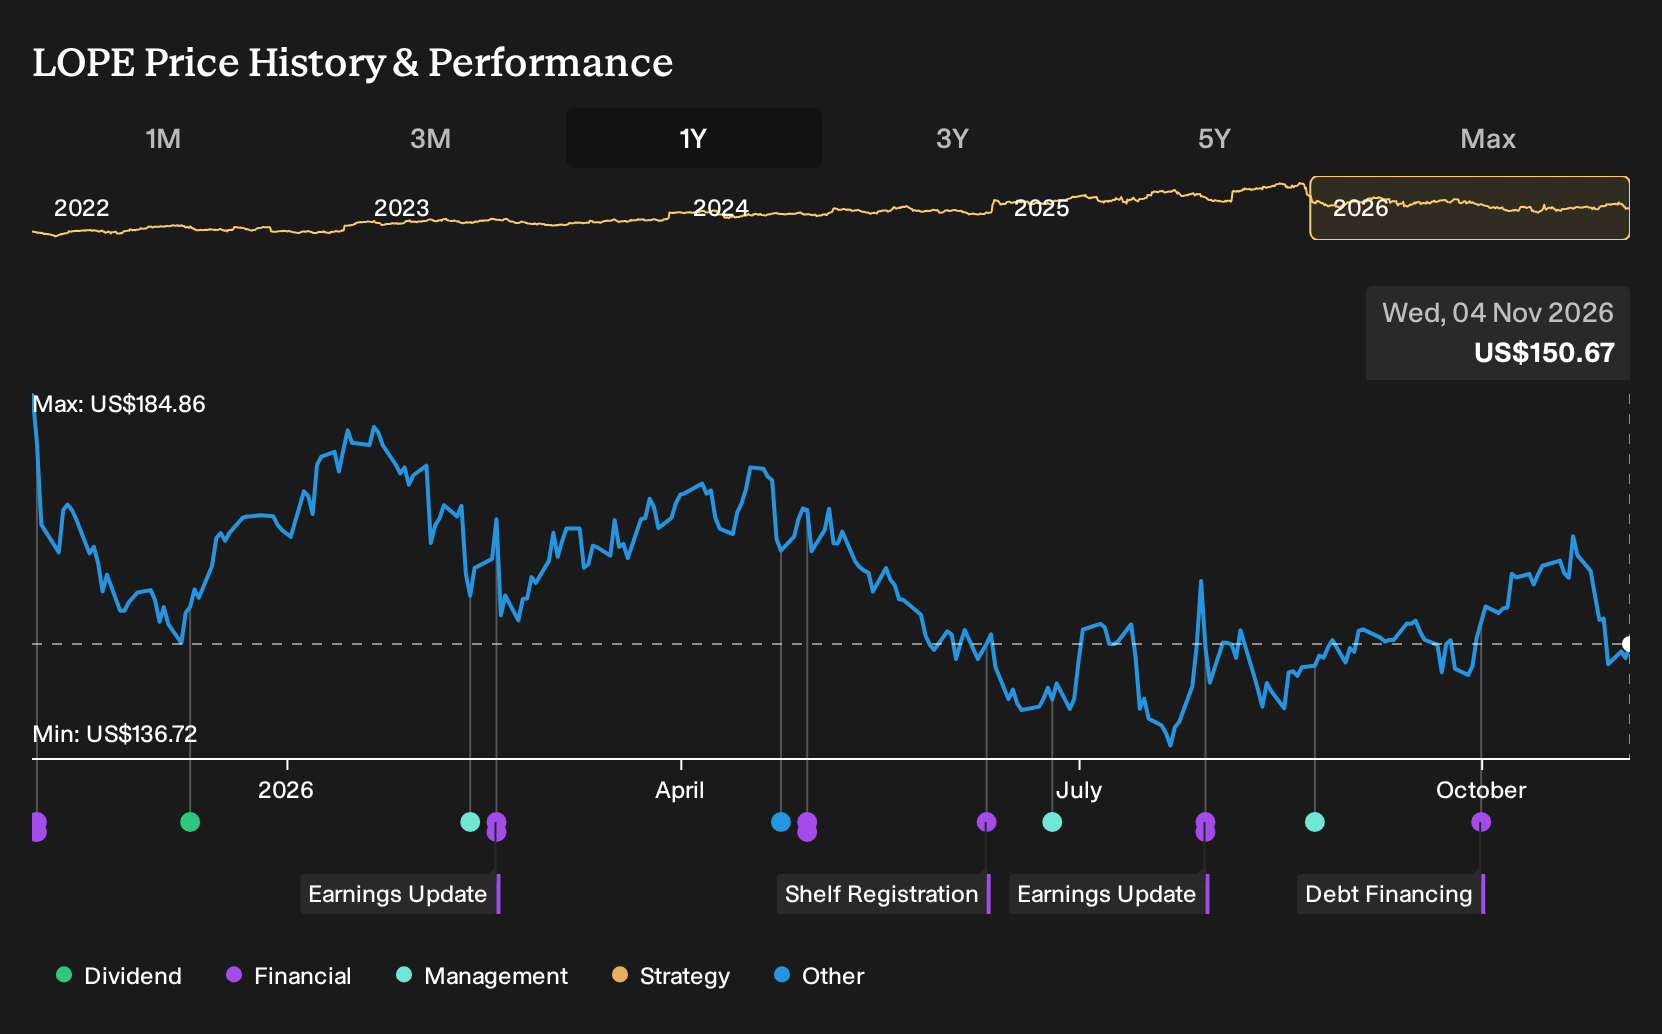
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$195 to about US$352 per share, so private investors are clearly split on Grand Canyon Education. Those views pre date the latest revenue miss, softer outlook and planned campus expansion, which could reshape sentiment and are worth weighing as you compare these competing perspectives.
Explore another Grand Canyon Education fair value estimate, including one that suggests as much as 134% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Grand Canyon Education research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Grand Canyon Education. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Grand Canyon Education's overall financial health at a glance.
Looking For More Investment Ideas Beyond Grand Canyon Education?
Once you have formed a view on Grand Canyon Education, it can help to compare that thesis with other listed businesses that share traits you care about, whether that is value, resilience, or balance sheet strength. The Simply Wall St Screener lets you move from one stock story to a full watchlist of ideas that fit your own criteria rather than someone else's hot list.
- If you want potential mispricing combined with quality fundamentals, scan a curated pool of companies through the 35 high quality undervalued stocks and see which ones line up with your return and risk expectations.
- For investors who put capital preservation first and prefer steadier profiles, filter the market using the 31 resilient stocks with low risk scores to spot businesses with more resilient characteristics.
- To emphasise financial strength and avoid stretched balance sheets, build a shortlist using the list of solid balance sheet and fundamentals (24 results) that highlights companies with stronger fundamentals backing their equity stories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com