
Olin (OLN) Shares Just Moved, So What Is Behind The Attention?
Olin (OLN) just paired a fresh earnings update with a major financing move, reporting mixed third quarter results while also lining up a large amended credit facility tied to its planned merger with Huntsman.
The short term picture shows momentum picking up, with a 1 week share price return of 9.78% and a 1 month share price gain of 11.12% to US$18.08. However, the longer view is still weak, with year to date share price performance down 16.10% and a 3 year total shareholder return that has declined 54.59%. This frames the latest earnings and financing news for Olin as a potential inflection point rather than a completed turnaround.
Scan how Olin's merger driven refinancing compares with other materials businesses that are reshaping their balance sheets by tracking the list of solid balance sheet and fundamentals (24 results) as potential case studies.
Bulls view Olin’s merger financing as a reset after a difficult earnings period. Bears highlight recent losses and substantial new credit lines. Which story do the current valuation signals support?
Most Popular Narrative: 9% Undervalued
Olin’s most followed valuation story currently pegs fair value at about $19.81 per share, modestly above the latest close at $18.08. This frames the merger and cost programs as the key swing factors.
The planned merger with Huntsman and formation of OlinHuntsman, with identified cost and integration synergies of more than US$400 million and pro forma 2025 revenue of about US$12.5b, is expected to create a more vertically integrated portfolio that can lift combined EBITDA and improve overall net margins.
See why 16 investors see Olin as 9% undervalued.
Result: Fair Value of $19.81 (UNDERVALUED)
Still, weak demand for chlor alkali and vinyls, or slower than planned Huntsman merger synergies, could quickly challenge the current Olin undervaluation story.
Find out about the key risks to this Olin narrative.
Another View: Cash Flow Says Olin Is Expensive
The popular story has Olin looking modestly undervalued against a US$19.81 fair value. A different lens tells a tougher story. Our DCF model puts future cash flows at about US$10.42 per share, well below the current US$18.08 price, which screens as overvalued on this approach. Which signal do you trust more?
To understand how sensitive that gap is to cash generation, integration progress and the new leverage profile, take a closer look at how the SWS DCF model works in practice. Start with the full calculation steps in the Look into how the SWS DCF model arrives at its fair value.
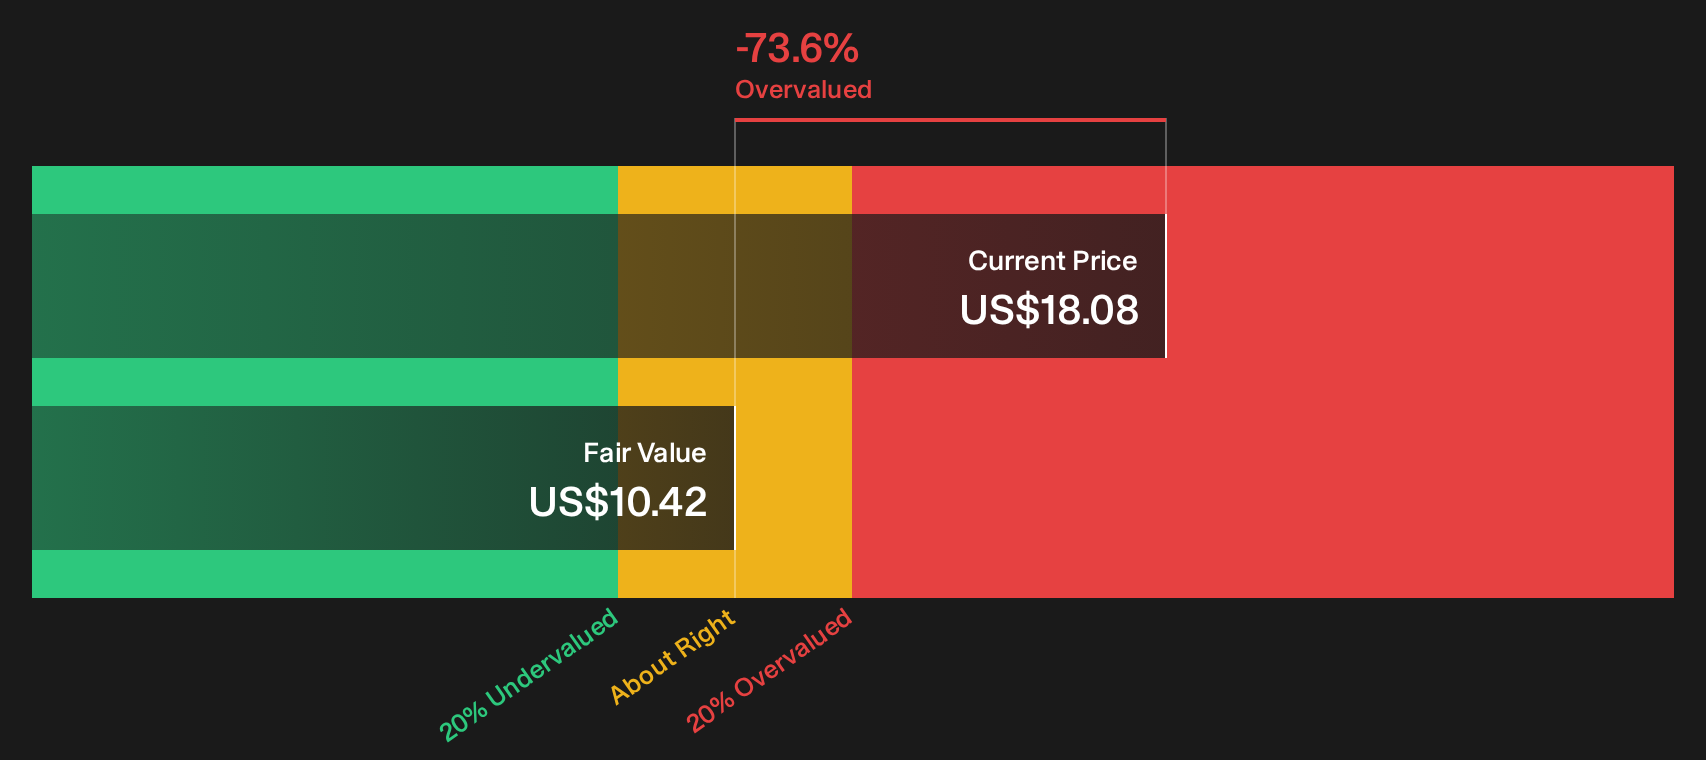
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Olin for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Olin’s value story are clear, so consider acting while sentiment is split and weigh both sides using the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Olin?
Do not stop at a single ticker when the opportunity set is much broader. Use focused screens to pressure test your thesis and surface fresh candidates fast.
- Target potential mispricings by scanning a curated pool of quality stocks that still look cheap on fundamentals through the 35 high quality undervalued stocks.
- Prioritise resilience and sort for businesses with sturdier finances and steadier profiles using the 31 resilient stocks with low risk scores.
- Hunt for under the radar opportunities by reviewing a focused 19 high quality undiscovered gems that most investors are not watching yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com