
CALB Group (SEHK:3931) Reports Stronger Nine Month Earnings, Is The Valuation Too Cheap?
CALB Group (SEHK:3931) just released nine month earnings to 30 September 2026, reporting revenue of CNY 45,949.27m and net income of CNY 1,366.06m, both higher than the prior year period.
Despite the strong nine month earnings update, CALB Group’s share price tells a different story. The stock is down 47.23% on a year to date share price return, and the 1 year total shareholder return has declined 58.6%, even after a 1.11% one day share price gain and a modest 1.63% seven day share price return.
Spot potential rebounds and under-the-radar peers to CALB Group by scanning our curated 601 high quality undiscovered gems that combine solid fundamentals with quieter share price performance.Bulls point to CALB Group’s rising revenue and profit, while bears focus on a share price that has more than halved. Which side does the current valuation actually support?
Price-to-Earnings of 9.6x: Is it justified?
VALB Group’s valuation story starts with a simple contrast. The shares last closed at HK$13.72, while the stock trades on a P/E of 9.6x that screens as inexpensive relative to both peers and the wider Asian Auto Components sector.
The P/E ratio compares what investors are paying today for each unit of current earnings. For CALB Group, this is a practical yardstick because the business is profitable, has reported net income of CN¥2,157.09m, and already generates earnings rather than just revenue growth.
Relative to direct peers on a P/E of 10x, the company trades slightly cheaper. Against the broader Asian Auto Components industry on 16.3x, the discount is far steeper. With an estimated fair P/E of 10.4x from the SWS fair ratio, the current 9.6x level sits below where the market could eventually settle if sentiment and fundamentals align.
Explore the SWS fair ratio for CALB Group.
Result: Price-to-Earnings of 9.6x (UNDERVALUED)
Still, the heavy 1 year total shareholder return decline of 58.6% and a revenue base concentrated in EV batteries and energy storage products leave CALB Group exposed if sector sentiment weakens.
Find out about the key risks to this CALB Group narrative.
Another View: DCF Says The Gap Is Even Wider
The P/E of CALB Group looks inexpensive, yet the SWS DCF model paints an even more aggressive picture. At a share price of HK$13.72, the stock is compared with an estimated future cash flow value of HK$120.56, which points to a very large gap that investors need to interpret for themselves.
The model result flags CALB Group as heavily undervalued on this framework, but every DCF relies on long term cash flow assumptions that can change. The key question is whether you think the market is correctly pricing risk around EV batteries and energy storage, or is instead overreacting to recent share price weakness.
Look into how the SWS DCF model arrives at its fair value.
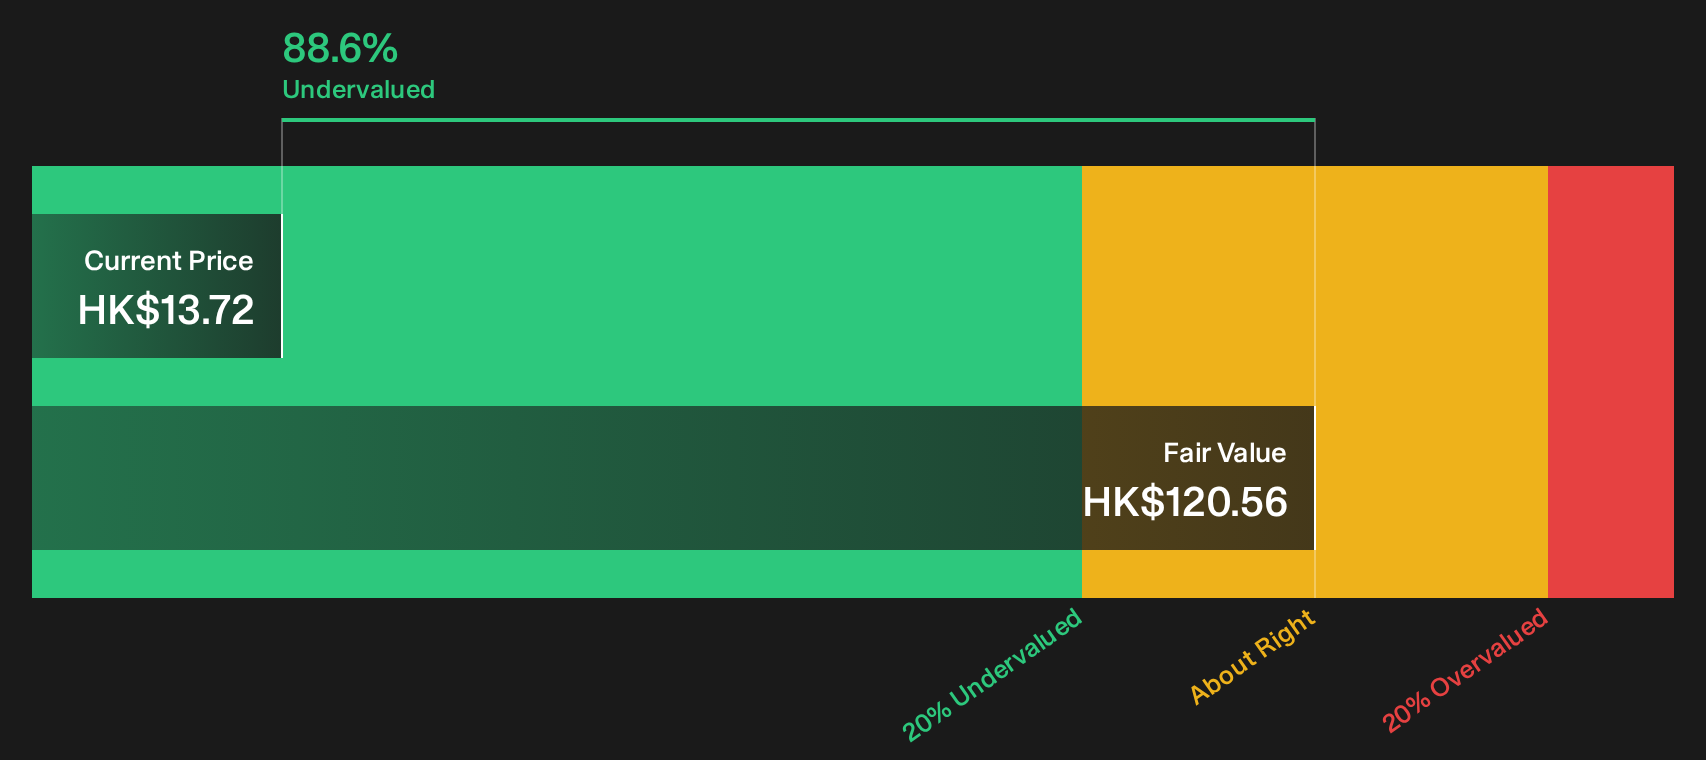
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out CALB Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 200 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on CALB Group so far, with strong earnings set against a weak share price, mean the next move comes down to your own read of the numbers. If you want to weigh both sides quickly and build your own call on the stock’s balance of potential upside and downside, start with the 4 key rewards and 1 important warning sign.
Looking for more investment ideas beyond CALB Group?
If CALB Group has your attention, do not stop here. Broaden your watchlist with fresh ideas that match different risk levels and income goals.
- Target potential mispricing by scanning a focused set of undervalued opportunities through the 200 high quality undervalued stocks.
- Prioritise capital preservation and steadier journeys by reviewing a curated pool of resilient companies in the 221 resilient stocks with low risk scores.
- Strengthen your watchlist with businesses backed by healthier finances using the list of solid balance sheet and fundamentals (197 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com