
Universal Health Services (UHS) Shares Just Moved, So What Is Driving Attention Now?
Universal Health Services (UHS) is back in focus after third quarter 2026 results showed higher sales alongside softer quarterly profit and earnings per share, while management continued to expand its behavioral health business and addressed liabilities related to Cumberland Hospital.
The earnings release has triggered a sharp move in Universal Health Services’ shares, with a 1 day share price return of 10.91% and a 7 day gain of 14.10%. However, the year to date share price return has declined 10.65% and the 1 year total shareholder return is down 13.44%. In contrast, the 3 and 5 year total shareholder returns of 53.59% and 55.83% indicate that the longer term record remains positive, even as recent momentum rebuilds around the latest behavioral health expansion plans and liability updates.
Compare how Universal Health Services stacks up against other hospital and healthcare operators by scanning a curated list of resilient balance sheet plays in our list of solid balance sheet and fundamentals (24 results).
After a double digit bounce in a week, but a weaker recent year for Universal Health Services and mixed earnings, are you now looking at early upside, or a rally that has already used up most of the easy gain?
Most Popular Narrative: 3% Overvalued
Universal Health Services last closed at $196.46, slightly above the most followed fair value estimate of $189.94. This estimate assumes a higher required return of 7.62% and incorporates softer long term earnings expectations.
The current valuation implies that investors are heavily discounting UHS’s ability to earn a return on the US$835 million Talkspace acquisition, to sustain acute care volume growth near recent guidance and to manage upcoming Medicaid supplemental payment cuts. This supports the view that Universal Health Services may be undervalued.
See why 18 investors see Universal Health Services as 3% overvalued.
Result: Fair Value of $189.94 (OVERVALUED)
Still, the narrative can crack if projected Medicaid supplemental payment cuts and rising liability expenses near US$175 million to US$200 million continue to eat into Universal Health Services’ profitability.
Find out about the key risks to this Universal Health Services narrative.
Another View: What Universal Health Services’ P/E Is Saying
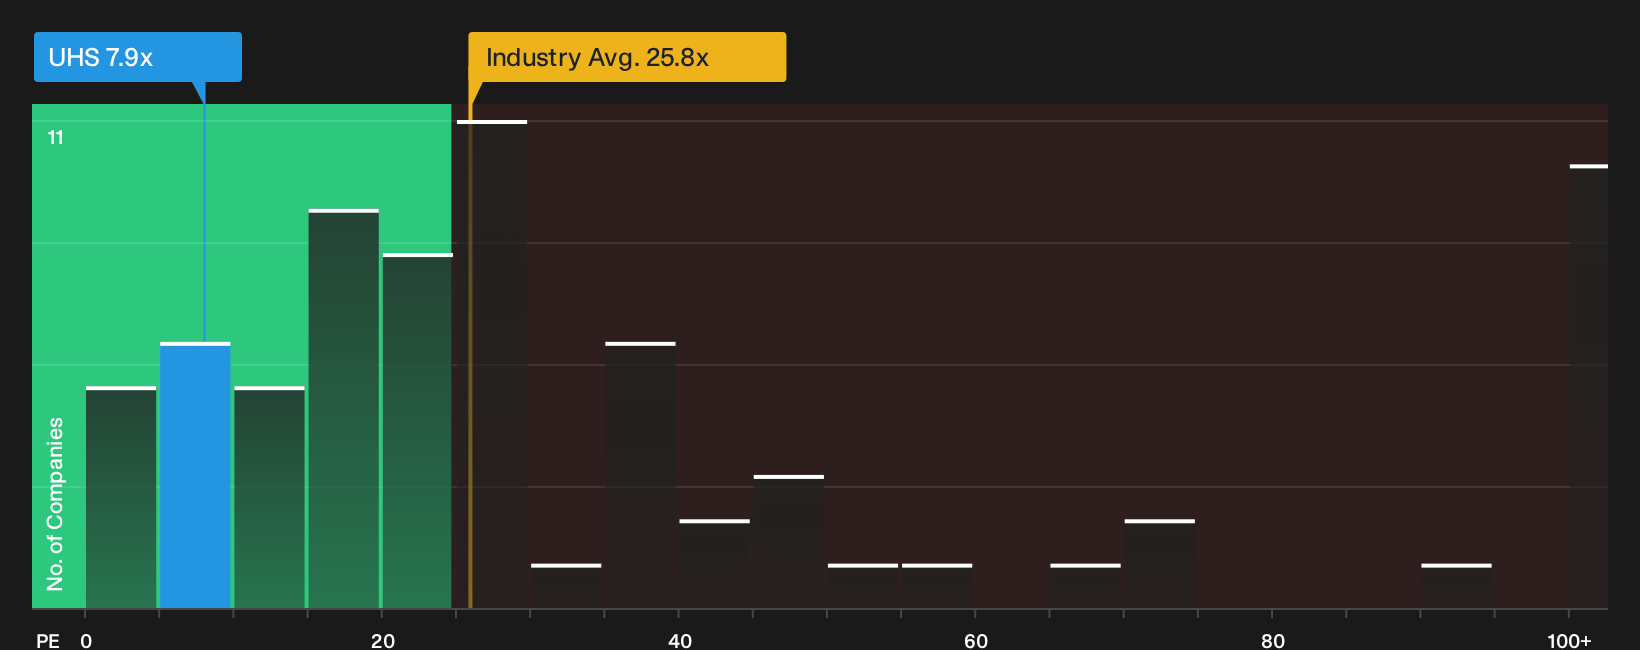
The DCF based fair value of $189.94 points to Universal Health Services trading about 3.4% above that estimate, yet the simple earnings multiple sends a different message. UHS trades on a P/E of 7.9x, while the wider US Healthcare industry sits around 24.8x and close peers average 21.5x.
The fair ratio for UHS is 22.5x, almost three times the current multiple. This suggests the gap between what investors pay for each dollar of earnings here and across the sector is wide. For you as a shareholder or potential buyer, the question is whether that discount reflects real risk around Medicaid cuts, liabilities and earnings forecasts, or an opportunity if those concerns ease.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Does the mixed mood on Universal Health Services leave you cautious or curious? If you want to move quickly and ground your own opinion in the numbers and narrative, weigh up the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Universal Health Services?
If Universal Health Services has sharpened your thinking, do not stop here. Broaden your watchlist now so tomorrow you are not wishing you had started today.
- Target potential value opportunities early by scanning a focused group of underappreciated businesses through the 35 high quality undervalued stocks.
- Build a steadier income stream by hunting for robust payout candidates with the 5 dividend fortresses.
- Prioritise resilience in tougher markets by zeroing in on companies that pass strict balance sheet and fundamentals filters using the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com