
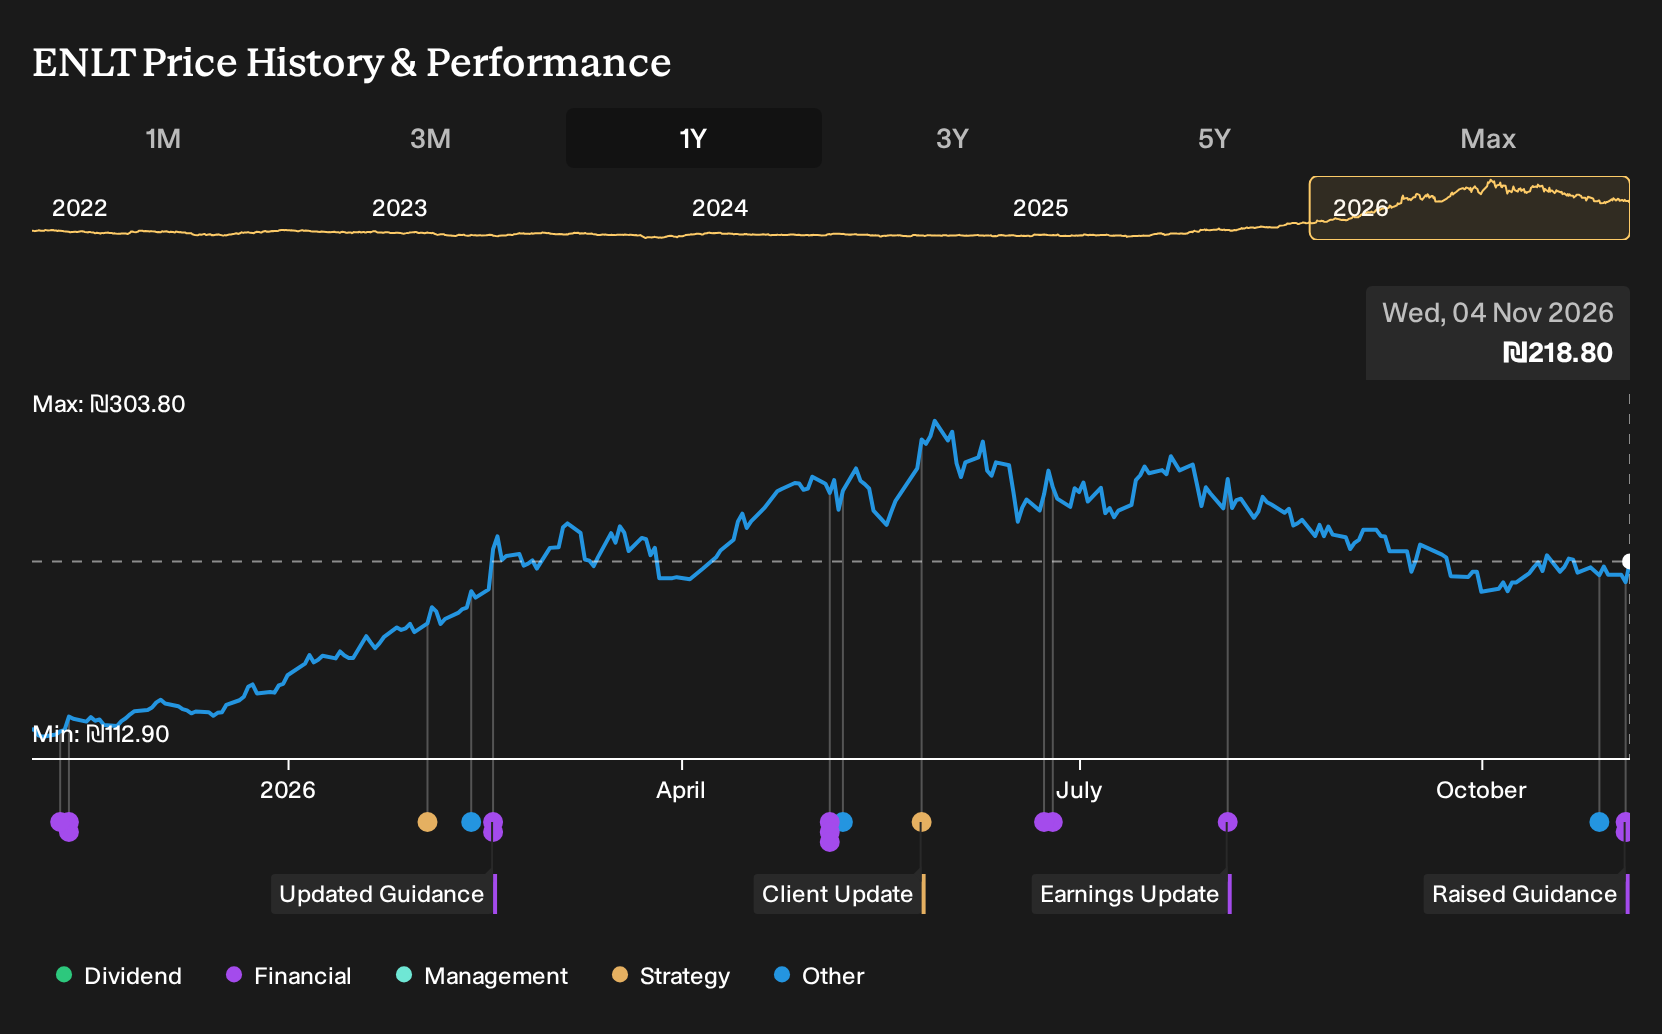
Why Enlight Renewable Energy Stock Is Up 6.1% And What's Next
- Enlight Renewable Energy reported third quarter 2026 revenue of US$231.37 million and net income of US$29.45 million, and raised full year 2026 revenue guidance to a range of US$810 million to US$830 million from US$790 million to US$820 million.
- The business is pairing higher reported revenue with a lower nine month net income of US$82.89 million versus US$117.84 million a year earlier. This highlights rising scale but also pressure on profitability as Enlight Renewable Energy advances a large pipeline of projects.
- Now the focus shifts to how Enlight Renewable Energy's raised 2026 revenue outlook reshapes the broader investment narrative around the company.
Scan how Enlight Renewable Energy compares to a handpicked group of resilient utilities and infrastructure plays by checking the 222 resilient stocks with low risk scores that have scored well on balance sheet strength and risk.
What Is Enlight Renewable Energy's Investment Narrative?
To own Enlight Renewable Energy, you need to be comfortable backing a capital intensive builder of utility scale projects where revenue can look strong while earnings lag. The raised 2026 guidance to US$810 million to US$830 million indicates that management sees enough contracted demand and pricing support across Israel, Europe and the U.S. to keep assets busy. The big near term swing factors are simple. Projects need to be finished on time, power sold at reasonable prices, and construction plus financing costs kept in check.
The latest quarter shows that scale is coming through in the top line, yet nine month profit and margin compression underline how execution and funding remain the real story. Interest costs are not well covered by earnings and the business leans heavily on external borrowing, so higher guidance only matters if future cash generation starts to track the accounting profit uplift. With the stock on a high P/E versus peers and recent insider selling flagged, the raised outlook sharpens, rather than softens, the questions around how much investors are already paying for Enlight Renewable Energy's growth path.
That said, there is a less comfortable angle to this whole setup that hinges on ...
There's only one way to know the right time to buy, sell or hold Enlight Renewable Energy. Head to Simply Wall St's company report for the latest analysis of Enlight Renewable Energy's Fair Value.
Reach Your Own Conclusion
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A useful starting point for your Enlight Renewable Energy research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Enlight Renewable Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to review Enlight Renewable Energy's overall financial position at a glance.
Looking For More Investment Ideas Beyond Enlight Renewable Energy?
If the Enlight Renewable Energy story has you thinking about position sizing, sector exposure, or simply whether there are cleaner balance sheets or different risk profiles out there, it can help to scan a wider field of stocks that share some of the traits you care about most.
- For investors who want potential mispricing combined with quality fundamentals, check out a curated set of businesses trading on appealing valuations through the 195 high quality undervalued stocks.
- If you care about income and want payouts that aim to match stronger financial footing, review a group of higher yielding payers via the 208 dividend fortresses.
- When capital preservation sits near the top of your checklist, start with companies that screen well on balance sheet resilience and risk using the 222 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com