
Should Strong Half Year Earnings Require Action From Nippon Sanso Holdings (TSE:4091) Investors?
- Nippon Sanso Holdings reported half year results to September 30, 2026, with sales of ¥737,147 million and net income of ¥79,591 million, alongside basic EPS from continuing operations of ¥183.88.
- The latest figures show higher sales, net income and earnings per share than the prior half year, indicating improved execution in the core gas operations.
- This report also considers how Nippon Sanso Holdings' stronger half year net income performance could relate to the existing long term investment narrative.
Scan how Nippon Sanso Holdings’ earnings story compares with other industrials by reviewing the hand picked list of solid balance sheet and fundamentals (22 results) that may offer similar resilience in their latest results.
Nippon Sanso Holdings Investment Narrative Recap
For a shareholder in Nippon Sanso Holdings, the core belief is that demand for industrial, electronic and medical gases, together with disciplined pricing and operations, can support steady earnings through different cycles. The latest half year report, with higher sales, net income and EPS than a year ago, points to solid execution rather than a dramatic shift.
The key short term swing factor is how volumes and pricing hold up in regions where hard goods and packaged gases have been soft, while inflation and logistics costs still affect margins. Currency moves and the existing high debt load remain the clearest risks. The recent earnings update does not materially change those pressure points.
Among recent information, the half year earnings report itself carries the most weight for the current story. Sales reached ¥737,147 million, net income came in at ¥79,591 million and basic EPS from continuing operations was ¥183.88. Each line item was higher than the prior period, which is notable in a context where analysts already expect only moderate future earnings expansion.
This step up in profitability intersects directly with the main catalysts investors are watching, such as potential volume recovery in electronics gases, better pricing and ongoing efficiency work in Japan and Europe. The report also provides more context to judge whether forecasts of mid single digit revenue growth and roughly stable margins appear sensible when set against real world cost pressures, FX swings and project delays highlighted in the risk list.
Nippon Sanso Holdings' current analyst narrative points to revenues of ¥1,558.0b and earnings of ¥154.5b by 2029, based on expected yearly revenue growth of 3.5% and an earnings increase of about ¥15.3b from ¥139.2b today.
Uncover how Nippon Sanso Holdings' fair value indicates a 6% potential upside to its current price that may not last much longer.
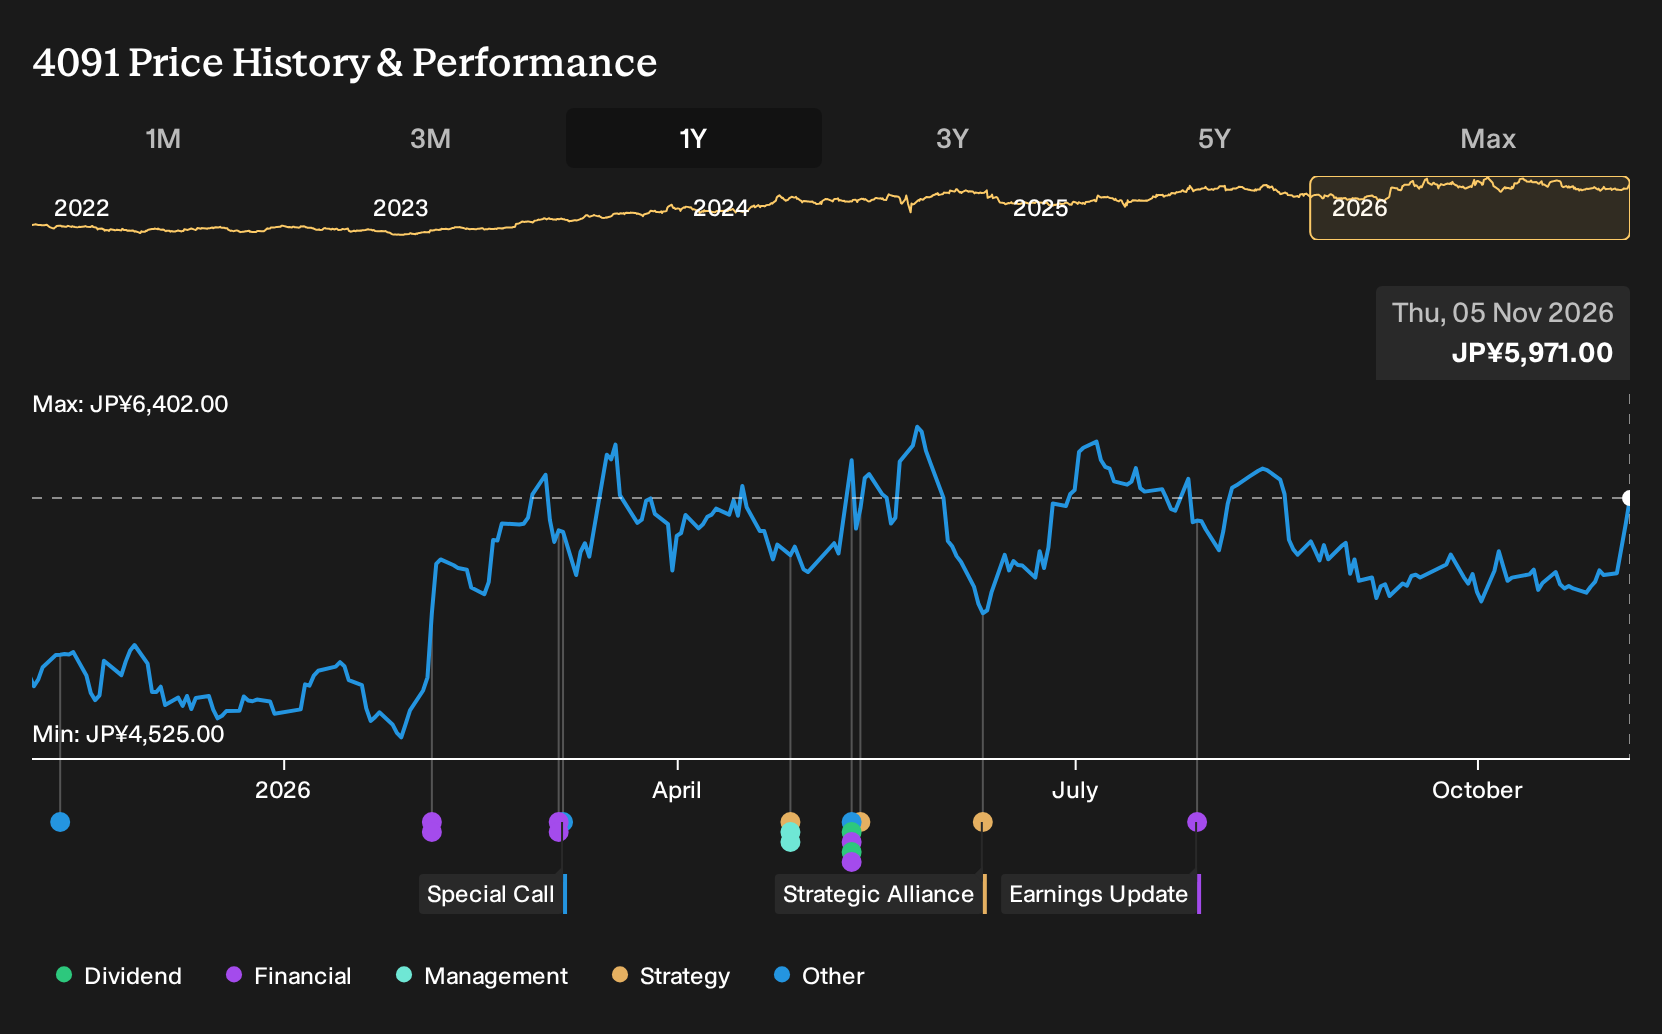
Exploring Other Perspectives
Some of the most optimistic analysts focus on Nippon Sanso Holdings’ roughly ¥150b capex backlog as a key catalyst. Before this latest half year report, they were pencilling in revenues of about ¥1,646.1b and earnings of ¥168.9b by 2029. Those estimates reflect a far more upbeat story. Use this earnings beat to test which narrative you find more convincing, since both were set before these fresh numbers arrived.
Explore another Nippon Sanso Holdings fair value estimate, including one that suggests up to 6% upside from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippon Sanso Holdings research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nippon Sanso Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Sanso Holdings' overall financial health at a glance.
Looking for more investment ideas beyond Nippon Sanso Holdings?
Once you have a handle on Nippon Sanso Holdings, it can help to broaden your watchlist with other companies that match the kind of balance sheet strength, income potential or valuation profile you are aiming for. The Simply Wall St Screener surfaces groups of stocks that share those traits so you can compare Nippon Sanso Holdings against a wider opportunity set.
- If you want to keep risk in check while still hunting for opportunities, start with a 22 resilient stocks with low risk scores that may align with a more defensive approach.
- For readers who focus on quality at a reasonable entry point, review a carefully filtered 19 high quality undervalued stocks that could merit a closer look beside Nippon Sanso Holdings.
- Income focused investors can scan for reliable cash returns by using a 28 dividend fortresses that might complement or contrast with Nippon Sanso Holdings' profile.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com