
Earnings Beat Might Change The Case For Investing In Littelfuse (LFUS)
- Littelfuse reported third quarter 2026 sales of US$766.73 million and net income of US$115.38 million, together with a reaffirmed quarterly dividend of US$0.80 per share payable on December 3, 2026.
- The earnings release highlighted stronger profitability across electronics, transportation and industrial operations, with higher basic and diluted earnings per share from continuing operations for both the quarter and the first nine months of 2026.
- We will now look at how Littelfuse's stronger earnings and affirmed dividend may influence the investment narrative investors have been using.
Scan how Littelfuse's earnings and dividend story compares with other potential opportunities by reviewing curated 35 high quality undervalued stocks across similar quality and cash flow profiles.
Littelfuse Investment Narrative Recap
Owning Littelfuse means buying into a story where high voltage projects, data center builds and grid work keep pulling more of its components into each system. The recent Q3 results show that earnings and sales across electronics, transportation and industrial are currently supporting that idea. The near term upside still leans on converting design wins and bookings into steady orders and cash generation.
The biggest operational risk remains uneven performance in transportation, where weaker segment margins and slower passenger vehicle demand can dilute group progress. The latest quarter does not remove that issue. It shows instead that Littelfuse can offset it for now with stronger electronics demand and ongoing portfolio and footprint adjustments.
The reaffirmed US$0.80 quarterly dividend is the clearest operational signal in this news cycle. Management is effectively saying current cash flow, even after a large one off loss in the last 12 months, comfortably covers regular shareholder payouts. For you as an investor, that dividend decision sits alongside earnings as a check on balance sheet strain.
That payout also ties directly into the main catalyst. High voltage and data center projects need to keep scaling so free cash flow can fund both capital needs and returns to investors without leaning too hard on external borrowing. If order momentum slows or transportation drags more heavily, maintaining the dividend at this level could crowd out reinvestment and weaken the longer term narrative around Littelfuse.
Littelfuse's current analyst script points to forecast revenues of US$3.8b and earnings of US$619.9 million by 2029, anchored on a 13.2% yearly revenue growth rate and an earnings swing of roughly US$628 million, from a loss of US$8.1 million today to that 2029 consensus figure.
Uncover why Littelfuse's fair value indicates a 26% potential upside to its current price that could narrow quickly.
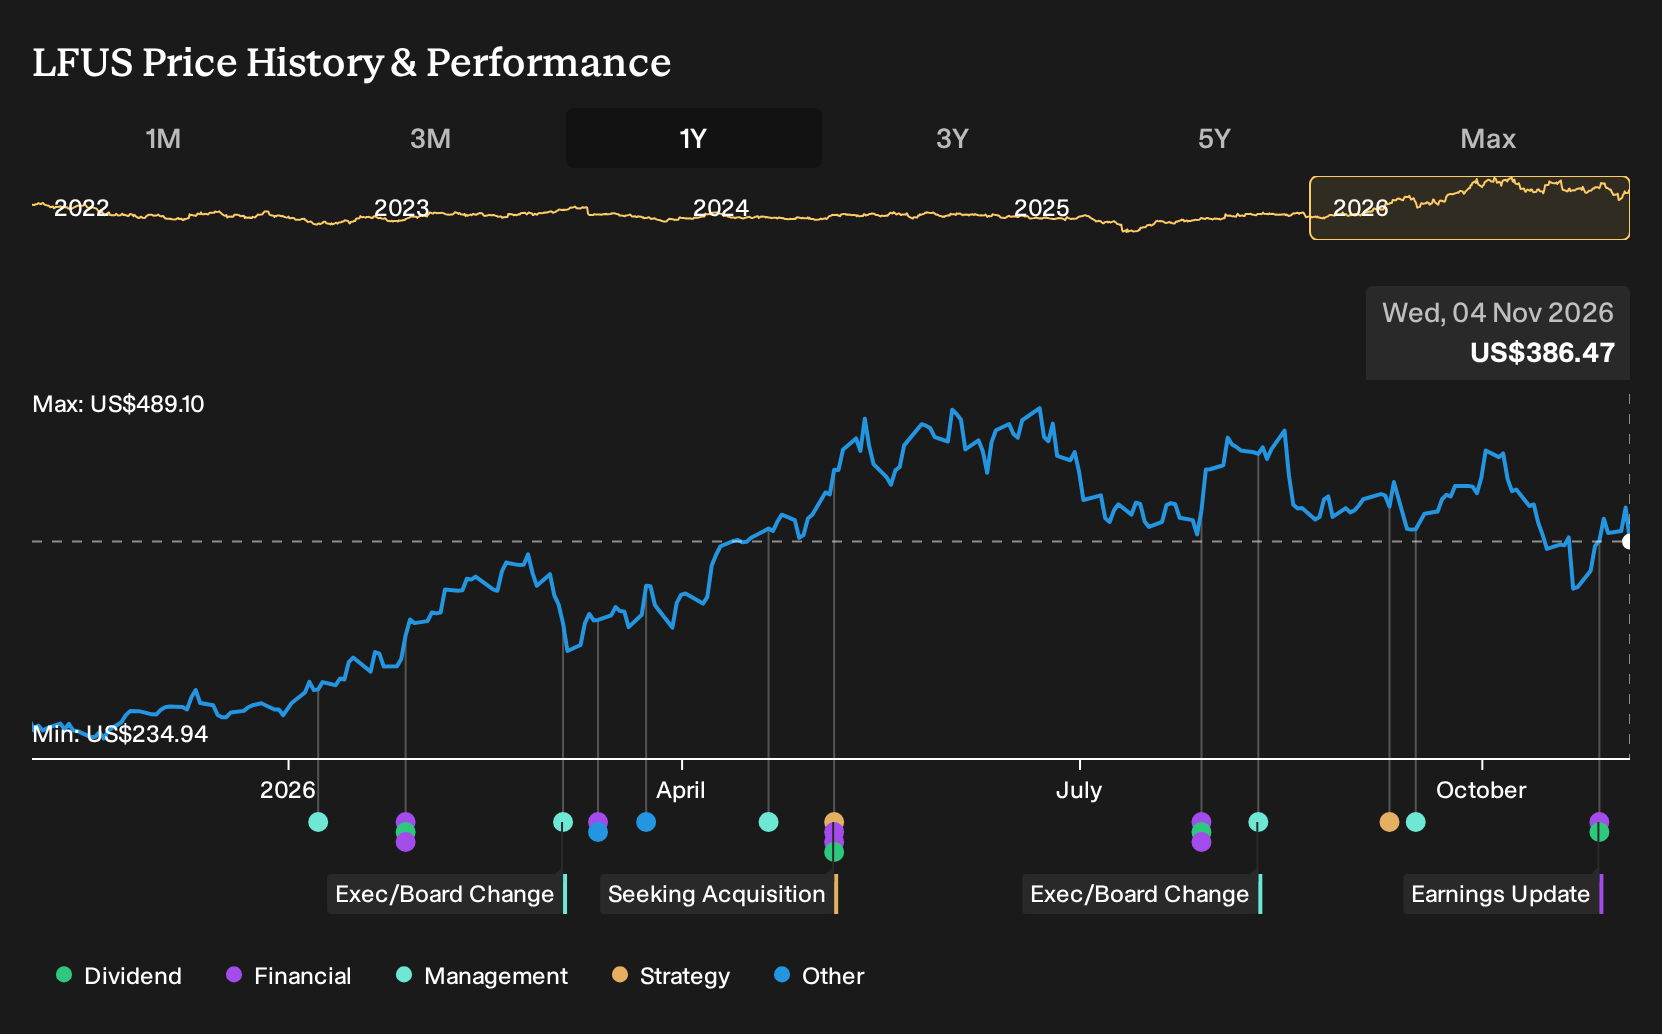
Exploring Other Perspectives
One alternative view on Littelfuse focuses less on the latest dividend affirmation and more on how much future success is already baked into the story. The most cautious analysts were expecting about US$3.8b of revenue and roughly US$706.5 million of earnings by 2029 even before this Q3 update, so their US$415.0 price target reflects a much tougher bar. That gap in expectations shows how far opinions can stretch. Use it as a prompt to explore several narratives before deciding how this new earnings and dividend news might shift the picture.
Explore another Littelfuse fair value estimate, including one that suggests it could be worth just $488.75!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider doing your own research.
- A great starting point for your Littelfuse research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Littelfuse. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Littelfuse's overall financial health at a glance.
Looking For More Ideas Beyond Littelfuse?
If this Littelfuse update has sharpened your view on earnings quality, dividends and balance sheet resilience, it can be useful to stack it against other candidates using the same lens. The Simply Wall St Screener lets you filter for the type of profile you want, then compare fundamentals in a consistent, side by side way.
- Prefer potential upside with quality filters already in place? Start with a curated set of 19 high quality undiscovered gems that share strong fundamentals but attract less market attention.
- If capital protection matters most to you, focus on a pool of 31 resilient stocks with low risk scores that screen well on financial strength and volatility checks.
- For investors who care about robust finances first, anchor your watchlist around a list of solid balance sheet and fundamentals (24 results) where debt, liquidity and cash generation are doing more of the heavy lifting.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com