
AtriCure (ATRC) Shares Just Moved, So What Is Going On?
AtriCure (ATRC) just put fresh numbers on the table. Third quarter 2026 earnings showed higher revenue and a move to profit, and management lifted full year revenue and adjusted EBITDA guidance.
The market has reacted strongly to these updates, with AtriCure’s share price logging a 1-day gain of 8.48% and a 30-day share price return of 22.08%, contributing to a 90-day move of 58.32% and a 1-year total shareholder return of 108.03%. This pattern points to building momentum over the short term, while the 5-year total shareholder return of a 16.34% decline reminds you that the longer journey has been more volatile and that recent enthusiasm is being shaped by the earnings turnaround and higher 2026 guidance.
Scan how AtriCure’s earnings swing compares with other medical stocks showing resilient balance sheets in our hand picked list of solid balance sheet and fundamentals (24 results).
AtriCure’s sharp rerating after the earnings swing forces a timing call. Is this the moment to lean into the new profitability story, or does the recent surge suggest waiting until valuation cools?
Most Popular Narrative: 4% Undervalued
AtriCure’s most followed valuation story pegs fair value at $68, slightly above the last close of $65.53. This frames the recent rally as largely aligned with that thesis rather than disconnected exuberance.
The pain business already contributes a higher margin mix through cryoSPHERE MAX and other products. Continued expansion across thoracic, sternotomy and extremity procedures can steadily raise the proportion of higher margin revenue within AtriCure, supporting gross margin and operating income.
See why 0 investors see AtriCure as 4% undervalued.
Result: Fair Value of $68 (UNDERVALUED)
Still, the bullish AtriCure story leans heavily on clean BoxX-NoAF data and on MIS weakness not deepening; either of these developments could quickly cool today’s enthusiasm.
Find out about the key risks to this AtriCure narrative.
Another View: AtriCure Looks Expensive On Sales
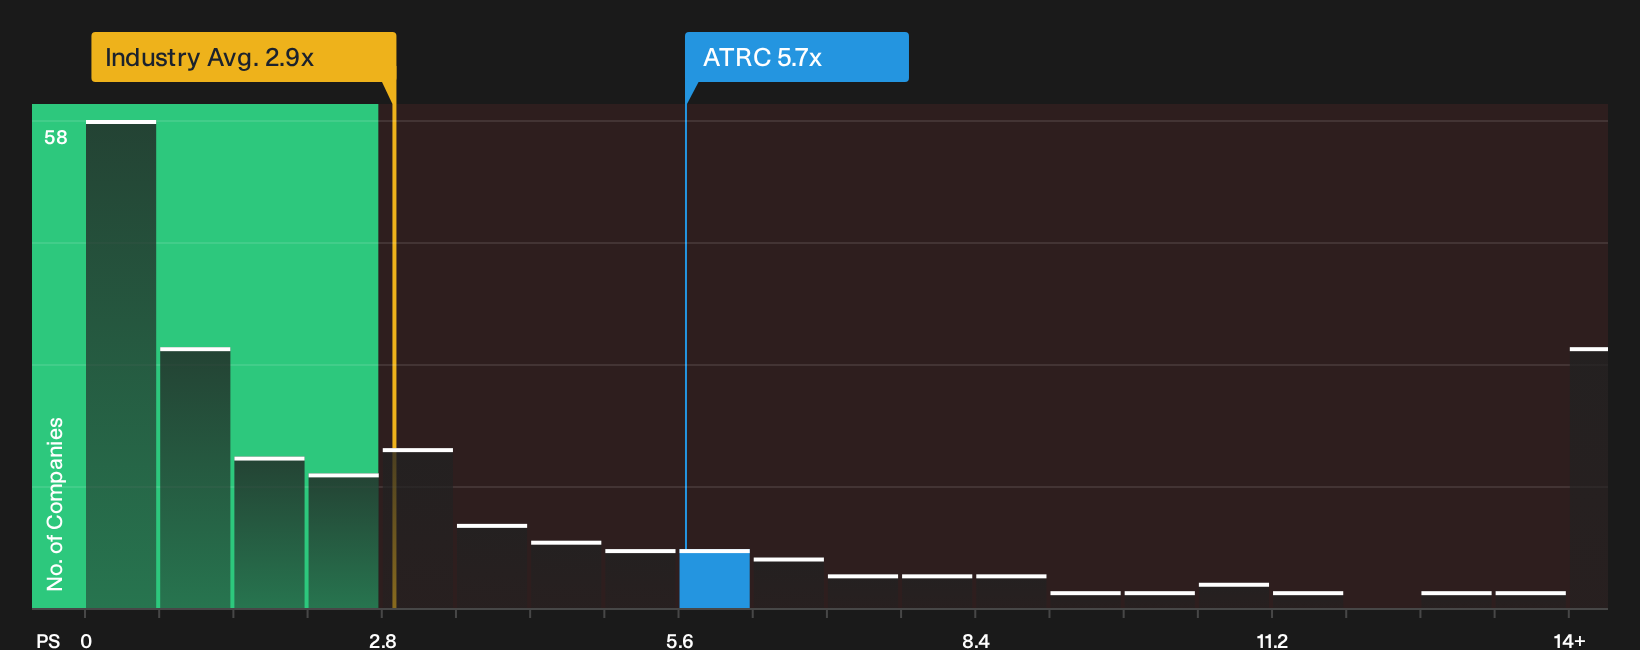
The fair value story around AtriCure leans on earnings and analyst targets, yet the price tag on revenue tells a different story. The stock trades on a P/S of 5.7x. That is higher than both the peer average of 5.5x and a fair ratio of 4.5x that the market could move toward, which raises a simple question for you. Is this a quality premium you are comfortable paying, or a valuation risk you would rather avoid?
To see what the numbers say about this price and how they stack up to peers and the fair ratio, find out in our valuation breakdown, See what the numbers say about this price — find out in our valuation breakdown.
For a visual sense of how AtriCure’s valuation compares with the rest of the sector, review the current P/S snapshot in
Next Steps
Sentiment around AtriCure is split, with strong recent returns on one side and valuation questions on the other, so consider reviewing the data promptly and stress testing it yourself, then weigh up the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond AtriCure?
If you want to keep building your watchlist with fresh opportunities, do not stop at AtriCure. Use the tools available and keep your options wide.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (24 results).
- Seek mispriced quality by running through the 35 high quality undervalued stocks before the wider market catches on.
- Hunt for future market leaders with solid track records using the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com