
Does Private Banking Expansion Change The Bull Case For JPMorgan Chase (JPM)?
- Recent news shows JPMorgan Chase issuing a series of long dated fixed income notes, expanding private banking in Dubai and the Middle East, and hiring senior wealth advisors and data leadership to support growth in payments, technology and high net worth client services.
- The mix of new callable bonds, the Dubai private bank build out and blockchain based payments tools points to JPMorgan Chase leaning into fee based businesses, balance sheet funding flexibility and transaction processing scale rather than relying only on traditional lending.
- We will now look at how this push into private banking and payment technology could reshape JPMorgan Chase's investment narrative.
Scan how JPMorgan Chase's push into long dated funding, private banking expansion, and payments tech compares with a curated list of solid balance sheet and fundamentals (24 results) targeting similar quality focused business models.
JPMorgan Chase Investment Narrative Recap
To own JPMorgan Chase, you need to be comfortable with a large, diversified bank leaning heavily on fee income, payments technology and wealth management to balance a still very credit sensitive core. The flurry of long dated callable notes mainly affects how the balance sheet is funded rather than the near term story around client activity, card volumes or payments adoption.
The key short term swing factor remains how long today’s strong Markets, Investment Banking and card trends hold against rising expenses tied to technology and AI. A real risk is that higher structural costs meet softer capital markets or consumer credit, which would squeeze margins more than the bond activity suggests.
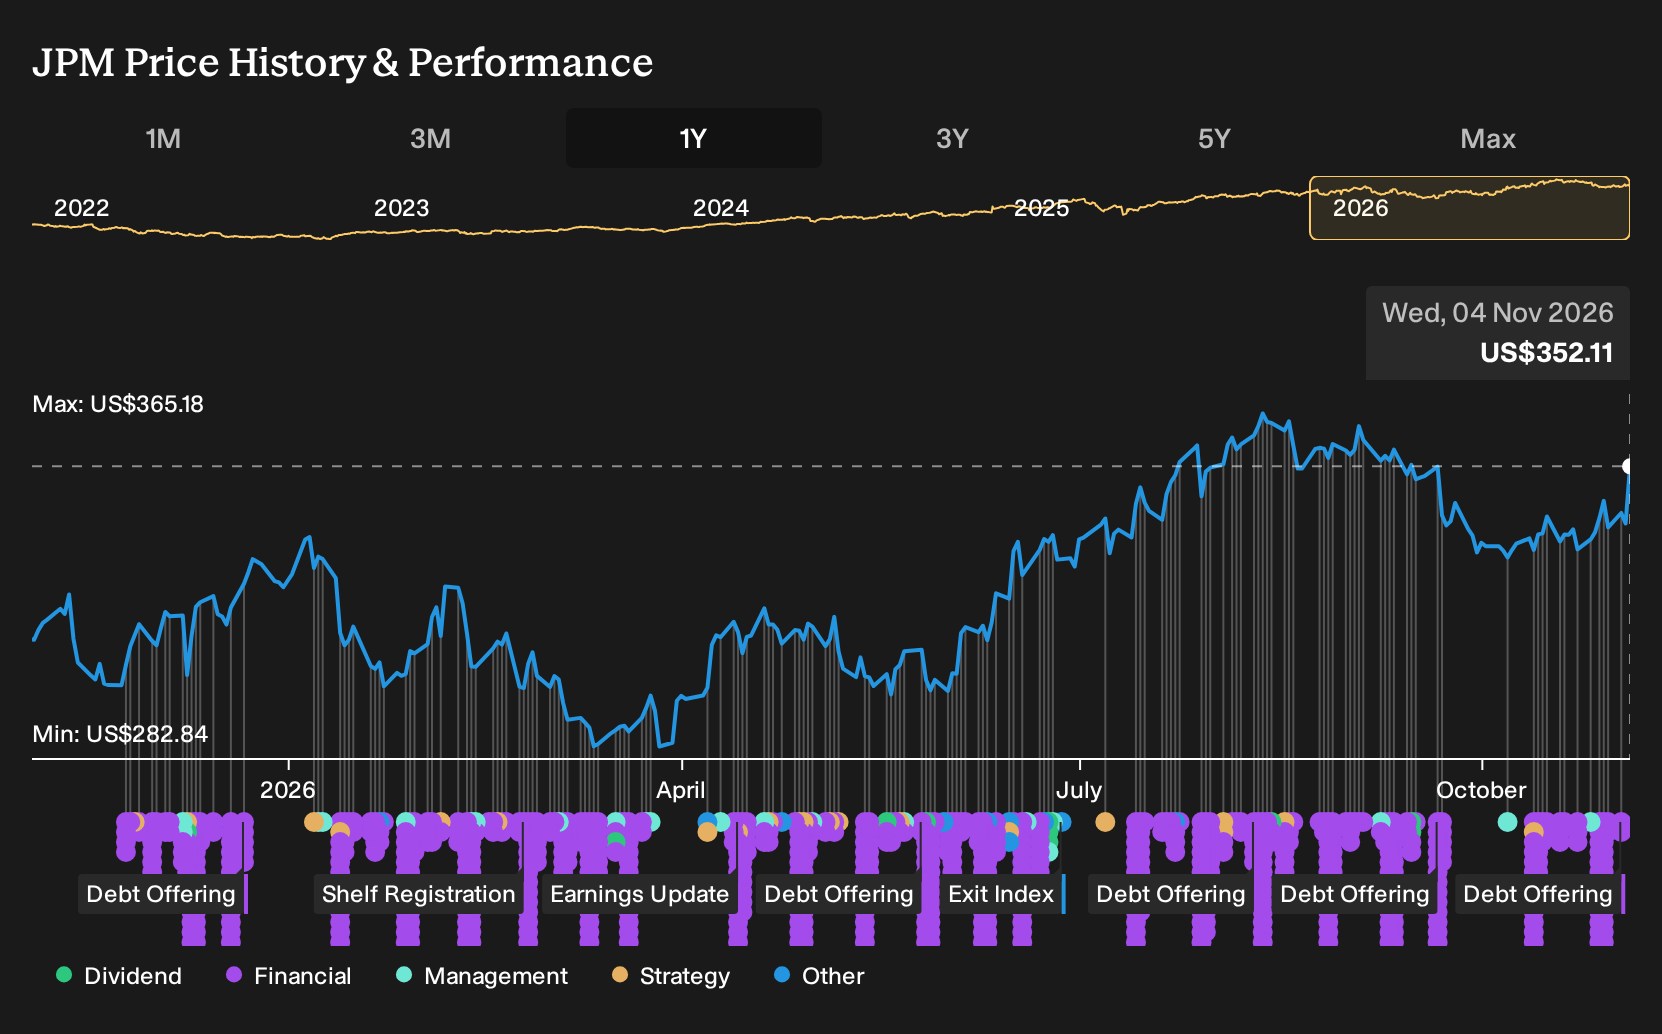
The most relevant recent announcement here is the wave of fixed income offerings, including 6.40% Notes due 2056, 6.30% Notes due 2056 and multiple callable issues out to the 2040s. This cluster of long dated, unsecured, largely senior notes gives JPMorgan Chase flexibility in how it funds cards, payments, trading and private banking build outs.
For you as a shareholder, the link back to catalysts is straightforward. A thick layer of term funding can support ongoing spending on deposits, payments tokenization work and wealth expansion without depending only on short term markets. The trade off is interest cost. If revenue growth or fee momentum softens while these coupons run, earnings and returns on equity could feel tighter than analyst models currently assume.
JPMorgan Chase's current analyst narrative points to revenues of US$227.1b and earnings of US$68.8b by 2029, based on an assumed 6.8% yearly revenue growth rate and a move from earnings today of US$63.6b to that 2029 consensus level, an increase of about US$5.2b.
Uncover why JPMorgan Chase's fair value indicates a 7% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate take focuses squarely on margin pressure. Before this new wave of long dated JPMorgan Chase bond deals, the most cautious analysts were already working off 2029 earnings of about US$65.6b on revenue of roughly US$225.1b, with a lower 15.5x P/E. That is a much more pessimistic story on how rising funding and technology costs might reshape the narrative. These views were set before the latest callable notes, so you should expect opinions to shift and to see how different analysts update their assumptions from here.
Explore 9 other JPMorgan Chase fair value estimates, including one that suggests as much as 7% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your JPMorgan Chase research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for JPMorgan Chase. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate JPMorgan Chase's overall financial health at a glance.
Looking for more investment ideas beyond JPMorgan Chase?
Once you have formed a view on JPMorgan Chase, it helps to line that thesis up against other high quality businesses with different risk and income profiles. The Simply Wall St Screener lets you scan for stocks that match the kind of balance sheet strength, income potential or lower volatility you want to target next.
- If resilience matters most, start with companies that pair sturdy finances with conservative risk profiles through the 31 resilient stocks with low risk scores.
- For investors who want income on top of stability, focus on businesses offering robust yields and consistent shareholder payouts using the 5 dividend fortresses.
- If the goal is to find quality that is not yet widely followed, scan for underappreciated businesses with solid fundamentals via the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com