
Arcus Biosciences (RCUS) Stock May Be Fully Priced For Its Sales Potential
Arcus Biosciences has seen a mixed share price journey, and that raises a straightforward question for investors who care about fundamentals. Is the current valuation of Arcus Biosciences stock adequately supported by the revenue the business is generating today and what its sales could reasonably support over time?
- Over the past 5 years, the share price has declined 50.4%, which puts the spotlight firmly on whether the company’s existing and potential sales justify where the stock trades now.
- For a clinical-stage biotech like Arcus Biosciences, future revenue often depends on progressing its pipeline and securing partnerships. These factors can influence how steadily sales might build and how long the business may rely on external funding.
- Your read on Arcus Biosciences is one view; the desks covering it have another. See what analysts think Arcus Biosciences's shares could be worth.
The issue now is whether Arcus Biosciences' current share price is well supported by its sales when weighed against the Fair Ratio benchmark.
If you want to cross-check Arcus Biosciences against other ideas where valuation is grounded in current fundamentals, a focused stock screen built around solid balance sheet and fundamentals stocks screener (24 results).
Does Arcus Biosciences Look Pricey on Sales?
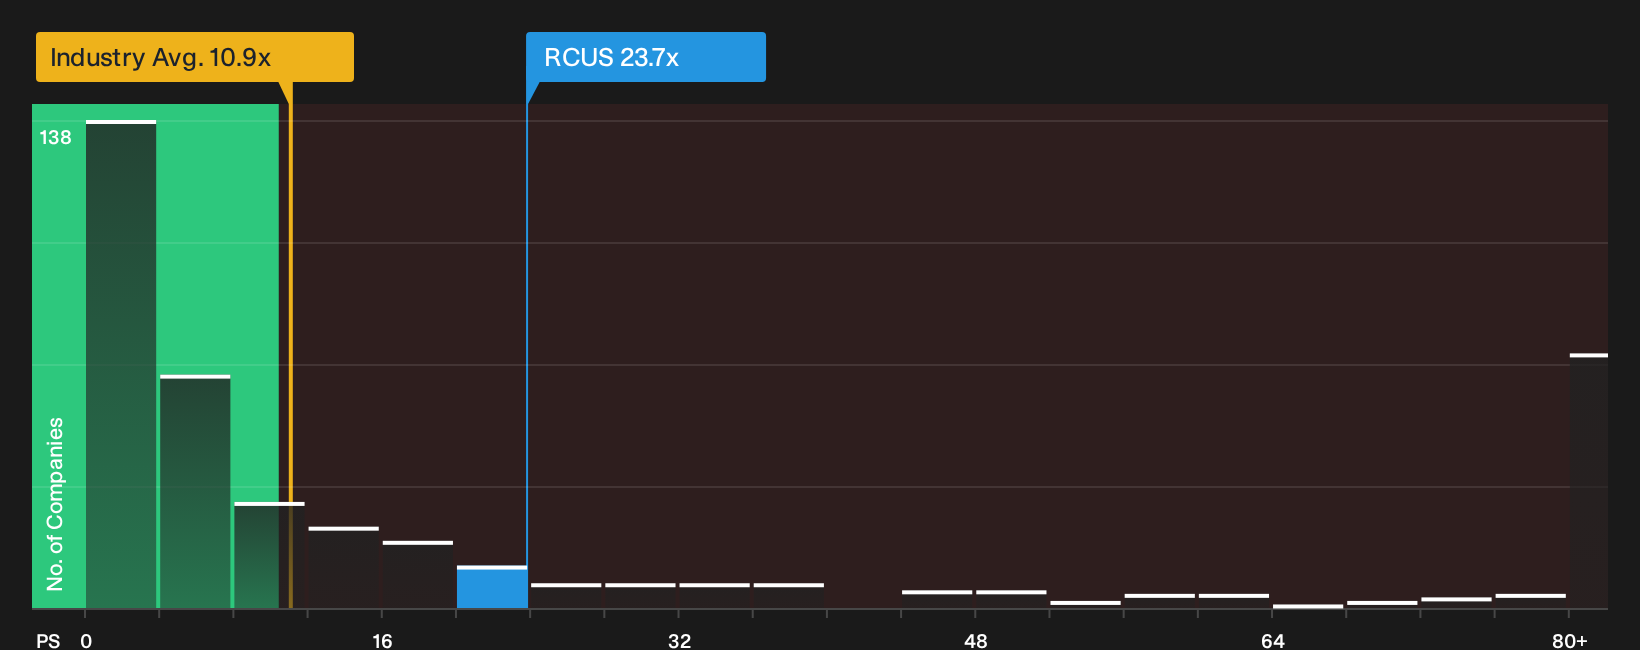
P/S works well for Arcus Biosciences because investors are mainly judging the value of its current and potential future drug commercialisation against the revenue it already records. On this lens, the stock trades on a P/S of 23.7x, which is higher than both the broader biotech industry average of 10.9x and the peer group average of 19.2x.
The Fair Ratio model, which adjusts for Arcus Biosciences' growth profile, margins, scale and risk, points to a far lower multiple than the one the market is paying. The gap is wide enough that the framework is effectively flagging that losses and risk are heavily penalising the shares, so the current P/S should be read as pricing in a rich set of expectations rather than as a small premium. That leaves you weighing how comfortable you are with paying this kind of sales multiple for Arcus Biosciences' pipeline and future execution. Explore the numbers behind Arcus Biosciences's P/S valuation.
The Arcus Biosciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Arcus Biosciences valuation puzzle leaves off and spell out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price, all hosted on the Community page. Each narrative treats Arcus Biosciences' implied fair value as a thesis about the business that can be revisited over time rather than a one-off snapshot.
One of the top community narratives on Arcus Biosciences: 61% undervalued
"Arcus Biosciences is positioning casdatifan as a backbone therapy in clear cell renal cell carcinoma across first, second and late lines..."
Discover why this Narrative puts Arcus Biosciences at 61% undervalued.
One more piece of the Arcus Biosciences puzzle worth checking
Valuation only tells part of the Arcus Biosciences story, since the research checks also highlight specific risk flags that could influence how you weigh the opportunity. Take a closer look at 2 warning signs before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com