
Lumo Kodit Oyj (HLSE:LUMO) Could Be 15% Undervalued On Q3 Sales Growth And Loss Swing
Lumo Kodit Oyj (HLSE:LUMO) just released third quarter figures, reporting higher sales but a swing from profit to loss that sharply changes the earnings picture for shareholders watching the stock today.
Lumo Kodit Oyj’s latest figures land against a tricky backdrop where the share price has risen about 4% over the past week and month, yet is still down 27.5% year to date and the 1 year total shareholder return has declined 28.5%, pointing to fading longer term momentum despite the recent bounce.
Scan beyond Lumo Kodit Oyj’s earnings swing and compare it with a hand picked 217 resilient stocks with low risk scores that may better fit a lower volatility, capital preservation mindset.
Lumo Kodit Oyj’s quick rebound has barely dented the heavy 1 year and multi year losses, so the real puzzle now is whether the valuation still leaves meaningful upside ahead or if the easy part of the recovery is already gone.
Most Popular Narrative: 15% Undervalued
The most followed valuation storyline for Lumo Kodit Oyj points to a fair value of €8.55, above the last close of €7.31, which puts the recent share rebound in a different light for anyone focused on upside versus risk.
The persistent low level of new housing starts, currently less than 20,000 per year compared to estimated demand of 35,000, combined with sustained population growth in Finland's largest cities (driven by both domestic and immigration trends), is expected to keep rental supply tight relative to demand, which should enhance Kojamo's long-term pricing power and support revenue and earnings growth.
See why 5 investors see Lumo Kodit Oyj as 15% undervalued.
Result: Fair Value of €8.55 (UNDERVALUED)
Still, that upside story for Lumo Kodit Oyj runs into real friction if rental oversupply lingers, or if high leverage and interest costs keep squeezing profitability.
Find out about the key risks to this Lumo Kodit Oyj narrative.
Another View: What Lumo Kodit Oyj’s P/E Is Telling You
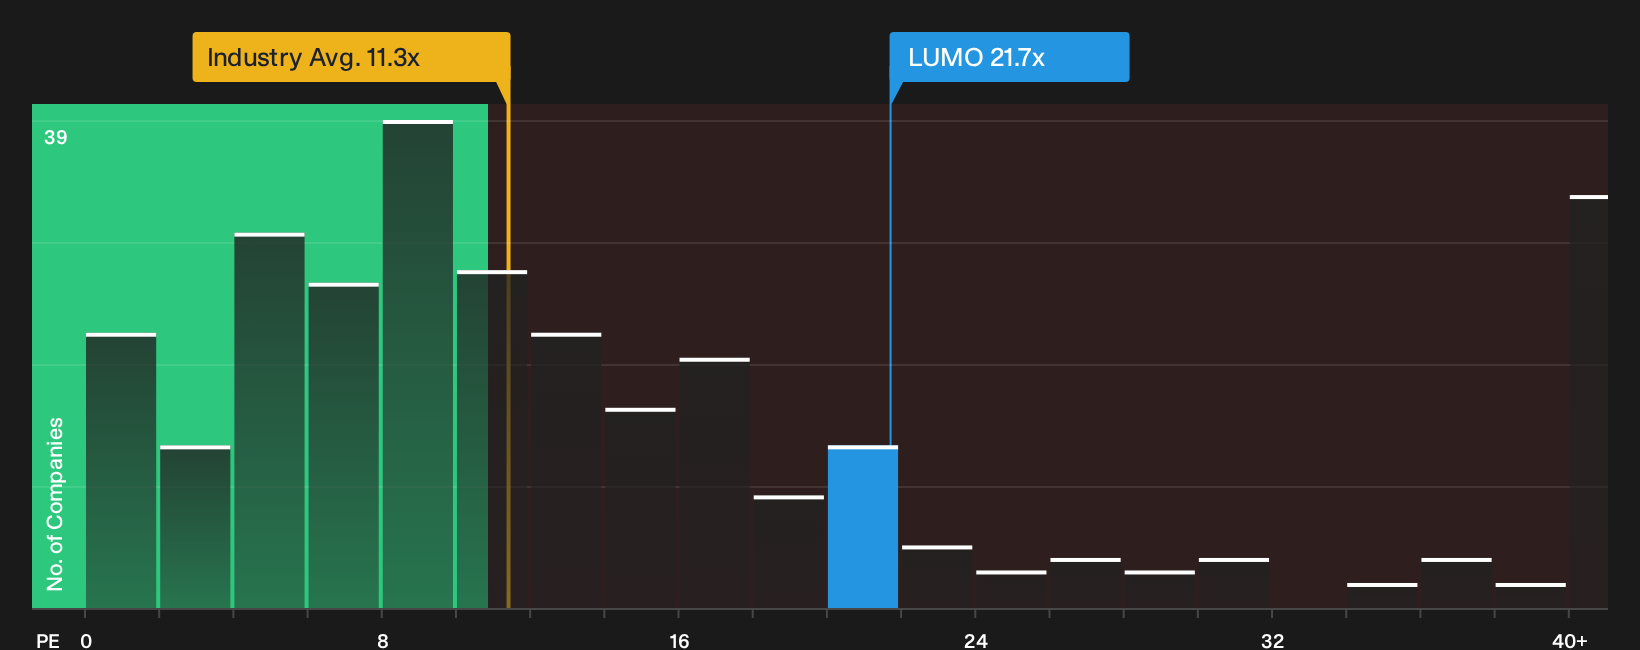
The story looks different once the focus shifts to the P/E ratio. Lumo Kodit Oyj trades on 21.7x earnings, which is richer than the European real estate sector at 11.3x and above its peer average of 19.5x, yet below a fair ratio estimate of 31.5x that the market could move towards. That blend of premium versus peers and discount to the fair ratio leaves you weighing more valuation risk in the near term against a possible catch up if sentiment improves.
To see how those earnings multiples stack up in more detail, and what they might imply for future pricing, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on Lumo Kodit Oyj is clearly mixed, so treat this as your cue to move fast, review the numbers, and decide where you stand. To weigh both sides of the story in one place, take a look at the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Lumo Kodit Oyj?
If Lumo Kodit Oyj no longer feels like the only place to focus your attention, you can broaden your watchlist and let high quality filters surface fresh opportunities.
- Target potential mispricing by scanning companies that combine quality fundamentals with appealing valuations through the 193 high quality undervalued stocks.
- Strengthen your income stream by focusing on resilient businesses offering higher yields with the 210 dividend fortresses.
- Prioritise resilience and capital protection by filtering for financially robust businesses using the list of solid balance sheet and fundamentals (195 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com