
Black Hills (BKH) Could Be 3% Undervalued As Q3 Earnings Improve
Black Hills (BKH) drew fresh attention after reporting third quarter 2026 results, with higher sales, net income and earnings per share compared with the same period a year earlier.
Black Hills shares have been climbing, with a 1 month share price return of 19.45% and a year to date share price gain of 20.88%, while total shareholder return over 1 year of 35.09% and 3 years of 92.49% signals strong longer term momentum, building off the latest earnings and the recent quarterly dividend affirmation.
Scan how Black Hills compares to other utility players showing strong recent momentum and fundamentals by reviewing the hand picked list of solid balance sheet and fundamentals (24 results).
After a 1 month jump of 19.45% and a share price near the latest analyst target, the easy win on Black Hills may not be the obvious call. Does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 3% Undervalued
On the numbers, the most followed narrative pegs Black Hills at a fair value of $86.64, a touch above the recent $84.19 close, which keeps the focus firmly on what could reshape earnings over the next few years.
The prospective 1.8 GW Cheyenne data center project has advanced, with the hyperscale customer now providing up to US$377 million of refundable construction contributions to fund long lead generation equipment, which creates a clearer route to additional rate base and future earnings once assets are in service and begin contributing to revenue.
See why 19 investors see Black Hills as 3% undervalued.
The narrative uses a 7.24% discount rate and incorporates the Google data center agreement, the US$4.7b capital plan and the pending NorthWestern Energy merger to reach that $86.64 figure. It assumes revenue rising from $2.3b today to $4.9b by 2029 and net income moving from $299.1m to $821.4m, with the valuation anchored on a future P/E of 10.2x rather than the current 20.0x.
For you as a shareholder or prospective investor, the key question is whether those building blocks feel realistic. That means testing your own view on regulators approving cost recovery on projects like Ready Wyoming and the Colorado battery facility, the timing and shape of Montana approval for the NorthWestern merger and how much of the Wyoming data center pipeline eventually lands in rate base on schedule.
Analysts behind this story also tie their pricing to meaningful assumed earnings growth, with revenue forecast to grow 28.6% a year and profit margins modeled to widen from 13.0% to 16.8%. Those inputs feed directly into the fair value, so if you think growth or margins land lower than that, your own estimate of what Black Hills is worth today may be below $86.64 even before factoring in any different discount rate.
Result: Fair Value of $86.64 (UNDERVALUED)
Still, the story around Black Hills can shift quickly if regulators take a tougher line on future rate cases or if data center projects are delayed in timing or reduced in scale.
Find out about the key risks to this Black Hills narrative.
Another View: SWS DCF Paints A Tougher Picture
The analyst narrative has Black Hills trading about 3% below an $86.64 fair value. A second lens tells a different story. The SWS DCF model estimates the future cash flow value at $66.88 per share versus the current $84.19 price, which implies the stock screens as expensive on this approach.
That gap is wide enough to matter. It suggests that if cash generation tracks the DCF assumptions rather than the more optimistic earnings path, investors could be paying up for growth that does not fully come through. Which version of Black Hills do you think is closer to reality, the earnings driven target or the cash flow model?
Look into how the SWS DCF model arrives at its fair value.
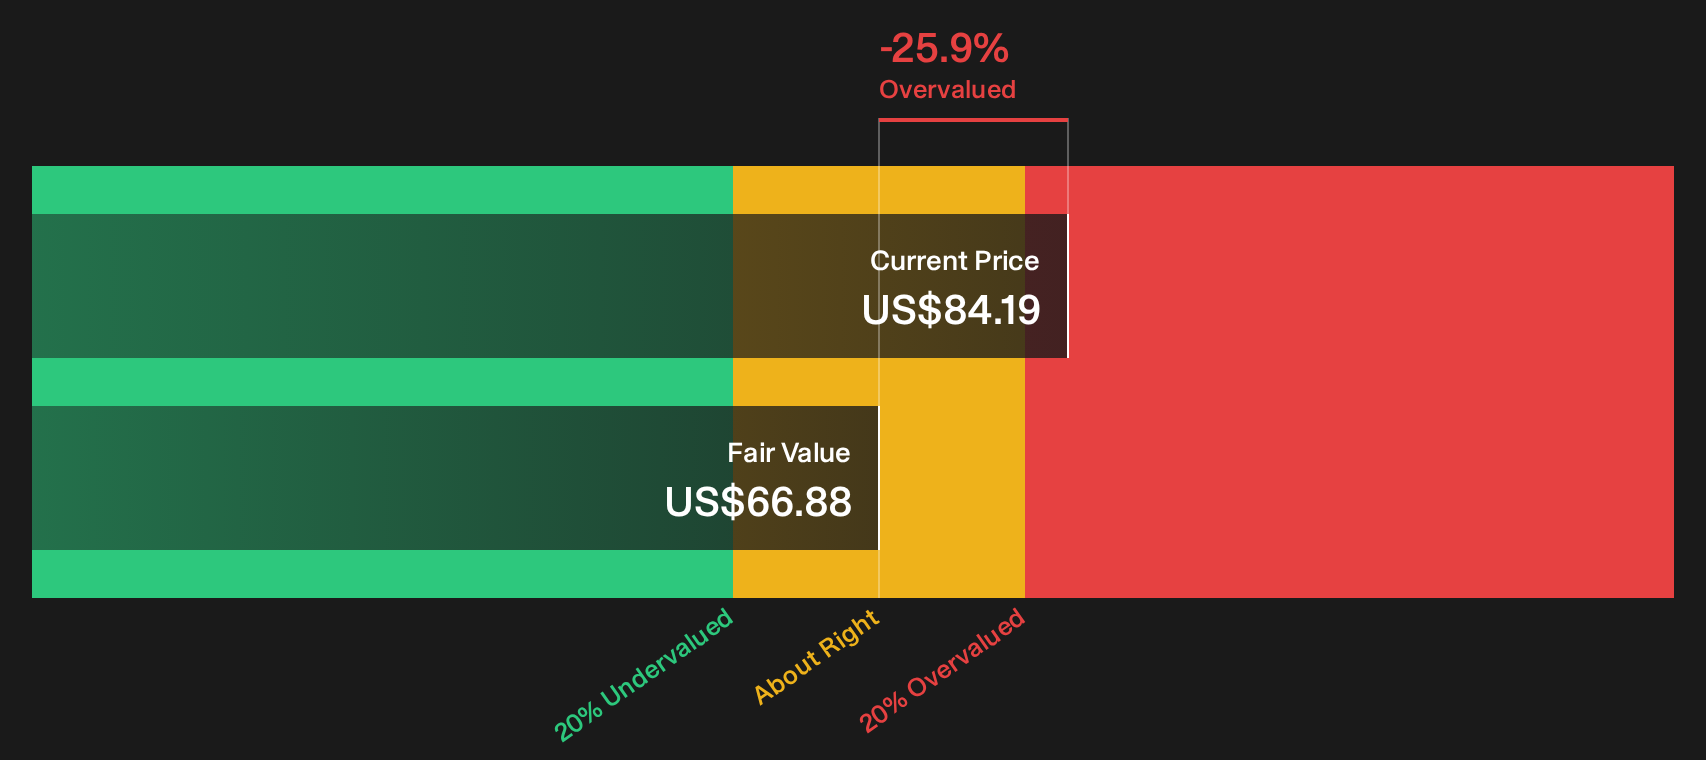
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Black Hills for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Black Hills so far. If you want a clear personal stance before sentiment shifts again, weigh both sides of the story and start with the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Black Hills?
If Black Hills has sharpened your thinking, use that momentum. Scan fresh opportunities, compare quality, and pressure test your own thesis pipeline before the next move.
- Target resilient balance sheets that can carry earnings stories through surprises with the list of solid balance sheet and fundamentals (24 results).
- Hunt for mispriced quality where fundamentals and valuation still line up using the 35 high quality undervalued stocks.
- Build a cash flow sleep-at-night backbone for your portfolio by screening for potential income workhorses via the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com