
DSM-Firmenich (ENXTAM:DSFIR) Just Gave Investors Something To Think About
DSM-Firmenich (ENXTAM:DSFIR) is back in focus after its Q3 2026 sales and trading update, which combined 5% like-for-like revenue growth, margin expansion and a completed multi million share buyback.
The recent Q3 update and share buyback seem to have fed into a strong run in DSM-Firmenich, with a 30 day share price return of 10.49% helping lift the year to date share price gain to 56.01% and the 1 year total shareholder return to 59.26%. This suggests that momentum has been building as investors reassess both growth prospects and perceived risk.
Seize the momentum around DSM-Firmenich and see how it compares with a hand picked group of potential breakout ideas in our 194 high quality undervalued stocks.DSM-Firmenich has already rewarded investors who were in before this latest leg higher. The real tension now sits in the valuation and whether the recent re rating still leaves enough upside for new buyers.
Most Popular Narrative: 11% Overvalued
DSM-Firmenich last closed at €107.40, while the most followed narrative points to a fair value of €96.47 based on a €9.1b revenue base and premium margin profile. That gap frames the current rally as a market that is already paying up for a lot of expected execution.
The current valuation implies a share price that already reflects successful execution on margin uplift, cash conversion targets and growth platforms such as Bovaer. This leaves limited room for disappointment if DSM-Firmenich underdelivers, so this narrative views the stock as overvalued and leans bearish.
See why 30 investors see DSM-Firmenich as 11% overvalued.
Result: Fair Value of €96.47 (OVERVALUED)
Still, if DSM-Firmenich maintains EBITDA margins around 20% and FX headwinds and free cash flow metrics continue to improve, that bearish valuation story could weaken quickly.
Find out about the key risks to this DSM-Firmenich narrative.
Another View: What Our DCF Model Says About DSM-Firmenich
The earlier narrative leans on analyst targets and earnings multiples to argue DSM-Firmenich looks 11% overvalued around €107.40. A different lens tells a very different story. The SWS DCF model values the shares at €144.85, around 25.9% above the current price, which frames the recent rally as still leaving room according to that cash flow view. Which yardstick do you trust more when those signals disagree this sharply?
To see how that cash flow approach is built and where the key assumptions sit, take a closer look at the SWS DCF model for DSM-Firmenich, starting with Look into how the SWS DCF model arrives at its fair value..
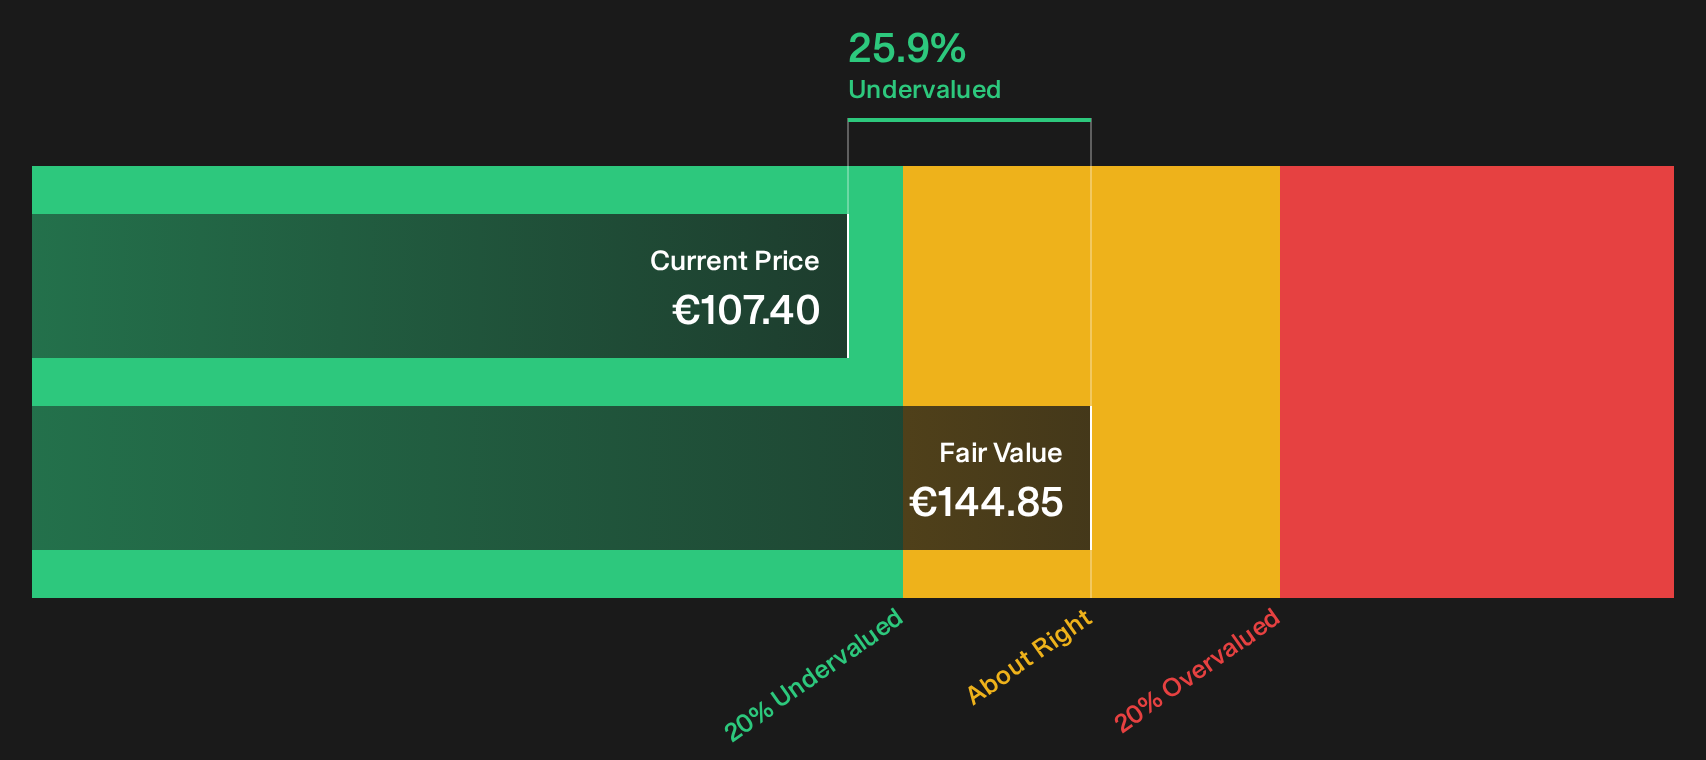
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out DSM-Firmenich for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment around DSM-Firmenich is split, with clear risks on one side and attractive rewards on the other. Move quickly, review the data, weigh both angles carefully, and then drill into the 2 key rewards and 1 important warning sign
Looking for more DSM-Firmenich sized ideas?
Do not stop at DSM-Firmenich. Broaden your watchlist with fresh candidates that match your style so you always have a pipeline of potential opportunities ready.
- Target potential mispricings by scanning a curated pool of quality companies through the 194 high quality undervalued stocks.
- Prioritise resilience and sleep better at night by focusing on businesses highlighted in the 217 resilient stocks with low risk scores.
- Hunt for less crowded opportunities by uncovering underfollowed stocks surfaced by the 588 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com