
How Improved Earnings At Rogers (ROG) Has Changed Its Investment Story
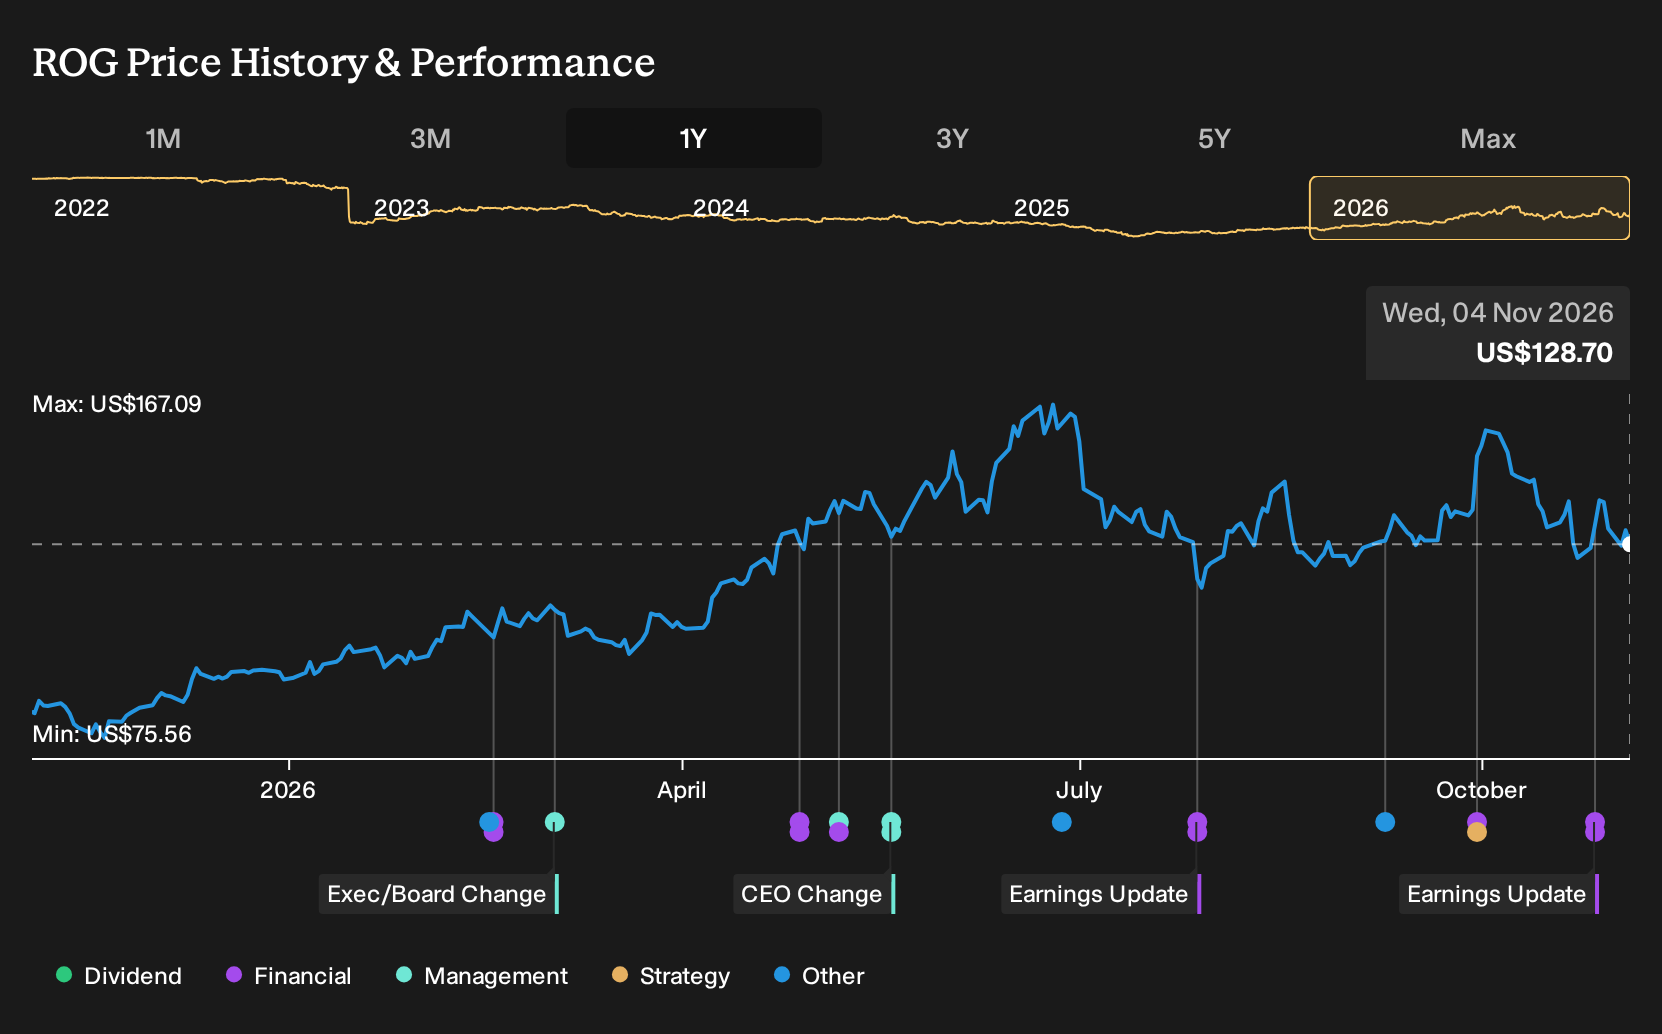
- Rogers Corporation reported third quarter 2026 basic earnings per share from continuing operations of US$1.27, compared with US$0.48 a year earlier, and issued fourth quarter guidance calling for net sales between US$215 million and US$225 million.
- The shift from a basic loss per share of US$3.63 over the first nine months of 2025 to basic earnings per share of US$2.29 over the same 2026 period reflects a significant change in Rogers Corporation’s underlying profitability from continuing operations.
- This raises the question of how Rogers Corporation’s improving earnings from continuing operations may influence the longer term investment narrative around the business.
Scan beyond Rogers and identify other companies showing meaningful shifts in profitability using the curated 35 high quality undervalued stocks as a starting point for your next round of ideas.
Rogers Investment Narrative Recap
To stay invested in Rogers, you need to be comfortable with a story built on higher value materials for EVs, AI data centers and advanced electronics, while the business continues to adjust its cost base. The latest quarter points to firmer earnings from continuing operations. However, the short term picture is still shaped by how quickly newer capacity and restructuring actions translate into steadier margins.
The key near term swing factor remains execution around the ceramic substrate ramp in China and broader manufacturing efficiency. Underutilization, supply chain disruptions or restructuring charges could reappear and affect profitability. The updated guidance for fourth quarter net sales in the US$215 million to US$225 million range does not fundamentally change those core risks or the main earnings catalyst.
The most relevant recent information for this narrative is Rogers’ third quarter and nine month earnings from continuing operations. Basic earnings per share of US$1.27 in the quarter and US$2.29 for the year to date, compared with losses a year earlier, indicate that recent restructuring and mix shifts are already flowing through the income statement, at least for now.
For an investor tracking catalysts, this matters because the thesis around AI connectivity, EV content and margin improvement depends on that profit base holding up while capacity ramps. The risk side of the story, including underutilized plants and the potential for further write offs if demand is weaker than expected, is still very much present, so execution on operations and cost control remains central to how this earnings path develops from here.
Analyst Forecasts And What They Assume For Rogers
Consensus expectations for Rogers matter because they frame how much of the recent earnings improvement is already embedded in the share price. Analysts are currently modeling revenue growth of 9.2% per year over the next three years, which they describe as a step up from the slower top line that investors have been working with through the restructuring phase. On the profit side, the forecasts include a move from roughly 3.7% net margin today to 10.8% in three years. This effectively assumes cleaner execution at the ceramic substrate facility and steadier manufacturing efficiency across the broader footprint.
On earnings, the gap between today and the outer year target is large in absolute terms. Analysts expect Rogers to move from current earnings of about US$31.3 million to US$117.0 million by 2029, which implies earnings rising by roughly US$85.7 million as the cost base resets and higher value programs scale. That earnings bridge is being underwritten by an expected earnings per share of US$5.59 by 2029, so the story is not only about revenue growth but also about margin expansion and a slightly lower share count, with analysts modeling a 0.65% annual reduction in shares outstanding over the next three years.
Valuation work in the consensus set connects those operating assumptions to a specific earnings multiple. Analysts flag that, for their targets to hold, Rogers would need to be valued on a P/E of 37.3x on those 2029 earnings, compared with about 76.1x today and against roughly 29.2x for the broader US electronic industry. That would still leave the stock on a higher multiple than sector peers if everything plays out in line with the consensus pathway. This is why the report explicitly encourages investors to compare the implied growth, margin profile, and discount rate of roughly 8.7% to 8.75% with their own expectations.
Rogers' narrative projects US$1.1b revenue and US$117.0 million earnings by 2029. This assumes 9.2% yearly revenue growth and requires earnings to rise by about US$85.7 million from current earnings of roughly US$31.3 million.
Uncover why Rogers' fair value indicates a 50% potential upside to its current price, which could narrow quickly if sentiment around Rogers shifts.
Exploring Other Perspectives
One alternate storyline for Rogers leans hard into the China curamik ramp as a positive catalyst, with the most optimistic analysts penciling in about US$1.1b of revenue and US$125.7 million of earnings by 2029 before this latest earnings surprise. You can treat those richer margin and share buyback assumptions as one end of a wide opinion range that may shift as analysts update their models after the new results.
Explore another Rogers fair value estimate, including one that suggests as much as 50% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Rogers research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Rogers. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Rogers' overall financial health at a glance.
Looking For More Investment Ideas Beyond Rogers?
Once you have a handle on Rogers, it can be useful to widen the lens and compare its profile with other businesses that fit different risk and income preferences using the Simply Wall St Screener.
- For investors who want income resilience before anything else, start with companies that look built to keep paying through thick and thin using the 5 dividend fortresses.
- If capital preservation matters more than chasing every opportunity, tilt your search toward steadier businesses through the 31 resilient stocks with low risk scores.
- When you want balance sheet strength and solid fundamentals to set the foundation for your research, use the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com