
Dear Oklo Stock Fans, Mark Your Calendars for November 6
Artificial intelligence (AI) is driving a surge in electricity demand, putting nuclear energy in the spotlight as a potential solution. That certainly appeared to be the market's expectation last year, judging by the impressive rally in nuclear power stocks. However, the mood has changed considerably in 2026. Despite the ongoing expansion of AI infrastructure, nuclear energy stocks have struggled to maintain their momentum.
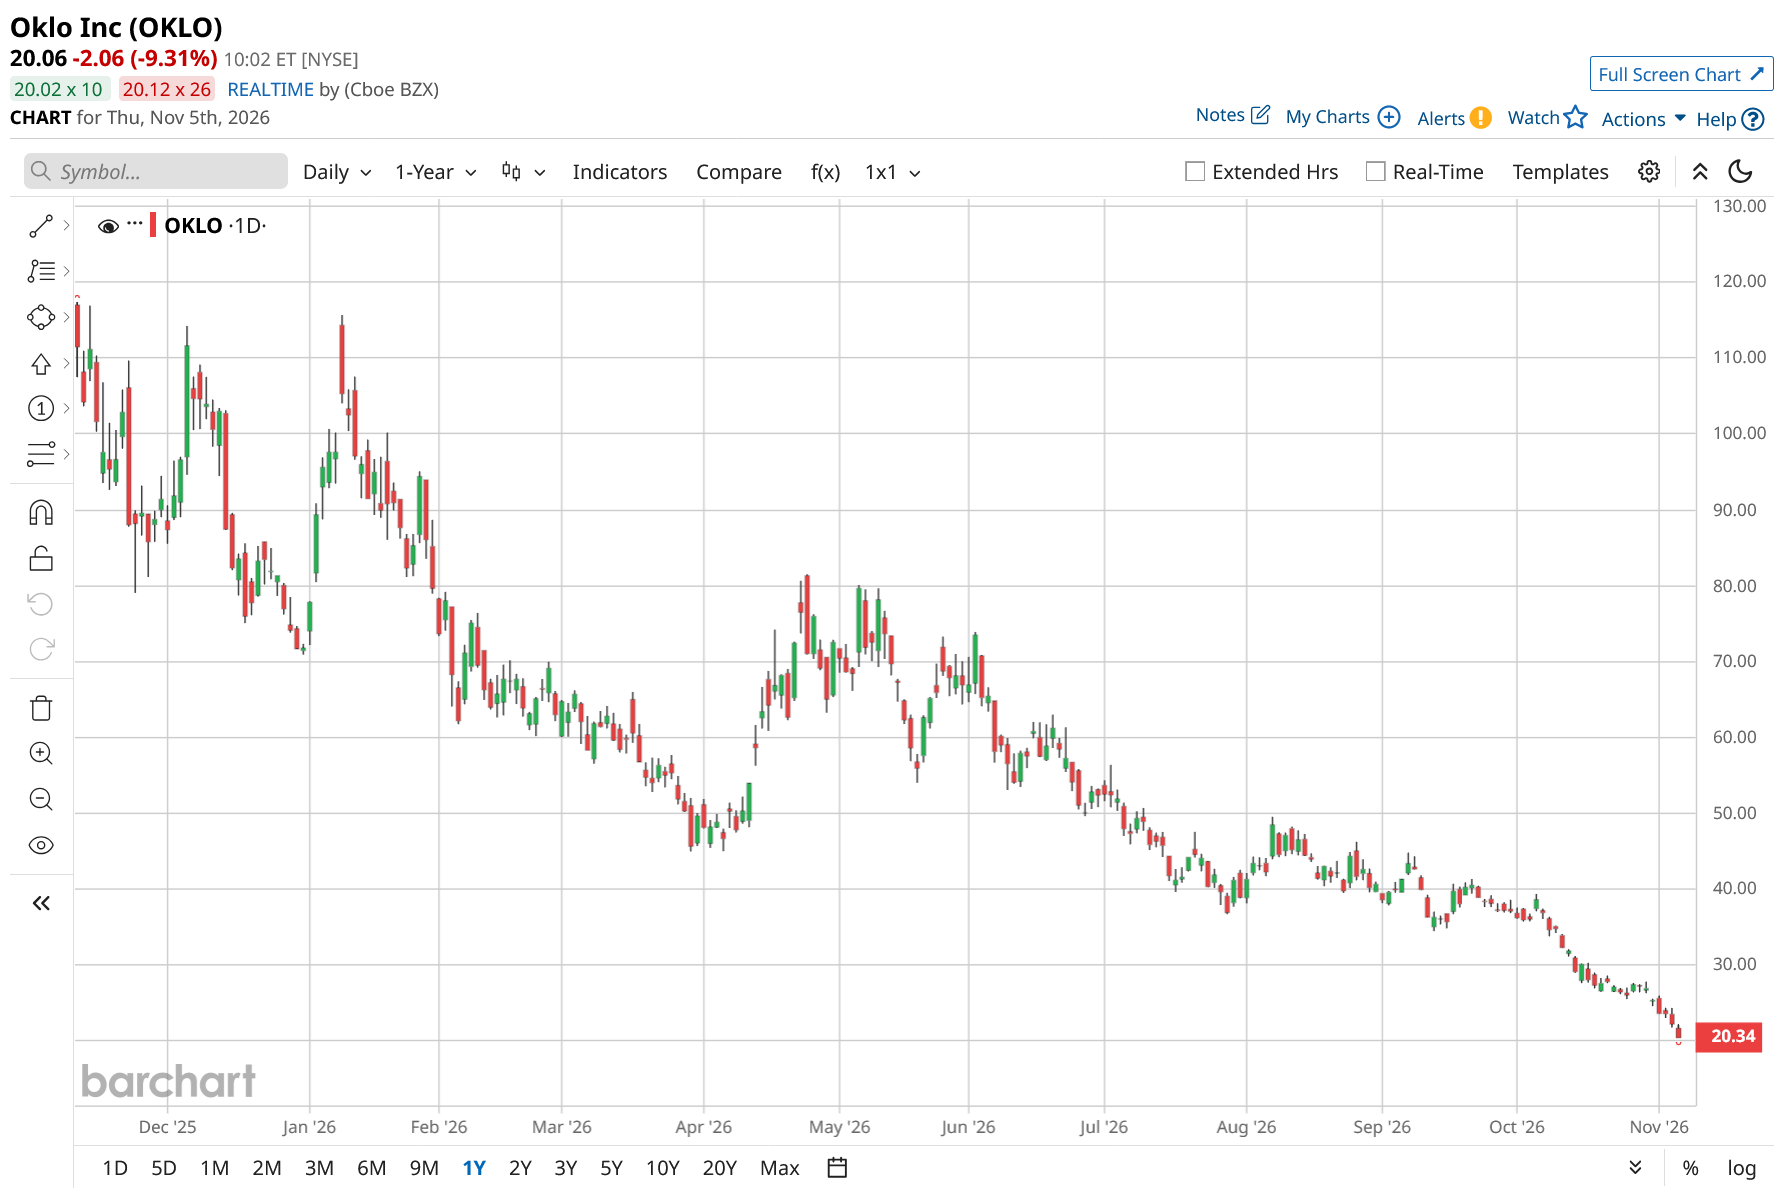
Oklo (OKLO) has been among the hardest-hit names, with its shares falling 71% year-to-date (YTD). The company is an emerging player in the small modular reactor (SMR) industry, seeking to establish a next-generation nuclear business spanning electricity generation, fuel, and isotopes.
Its ambitious strategy includes developing nuclear facilities specifically to power AI data centers. To support these plans, Oklo has even raised billions of dollars. Yet its commercial ambitions remain a work in progress.
Now, investors can assess how far the company has progressed when Oklo releases its Q3 FY2026 financial results before the market opens on Friday, Nov. 6. Management's commentary will also be important for understanding the company's development timeline and growth strategies.
About Oklo Stock
Based in Santa Clara, California, Oklo develops advanced nuclear fission power plants designed to deliver dependable, scalable electricity. With a market cap of nearly $4.1 billion, the company is developing its Aurora Powerhouse, which is designed to generate 15–75 megawatts of electricity.
Oklo's ambitions extend beyond reactor construction. It is also investing in nuclear fuel recycling and fabrication technologies designed to transform used nuclear fuel into usable fuel for its reactors.
The stock's recent performance, however, tells a tale of struggle. Oklo’s shares have declined 83% over the past 52 weeks. The weakness has continued over shorter periods, with OKLO stock losing 51% in the past three months. Over just the past five trading sessions, shares plunged another 22%.
From a valuation standpoint, OKLO stock is currently trading at 1,334.36 times sales, significantly above the industry average. Such a steep premium highlights the lofty expectations priced into the company, despite its early-stage commercial operations.
A Closer Look at Oklo’s Q2 Earnings
On Aug. 7, Oklo’s shares climbed 14.8% intraday after it reported a notable improvement in its financial position during Q2 FY2026. Revenue reached $1.21 million, up from zero in the same quarter last year. Although still modest, the figure marked an initial step toward commercialization.
The bigger story was the acceleration in operating expenses. Research and development (R&D) costs surged 244.2% year-over-year (YoY) to $39.5 million as Oklo continued investing in reactor design, engineering, fuel development, and deployment. General and administrative (G&A) expenses also climbed 106.7% to $34.2 million, reflecting factors including workforce expansion, acquisitions, and increased stock-based compensation.
These higher costs pushed total operating expenses up 165.6% from the year-ago value to $74.4 million, expanding the operating loss to $73.2 million. Net loss nearly doubled to $48.5 million. Meanwhile, net loss per share came in at $0.28, widening 55.6% YoY.
Oklo finished the quarter with $3 billion in cash and marketable securities, giving it a substantial financial reserve to support its development plans. Nevertheless, cash consumption remains an important consideration. Operating cash outflow increased to $65.5 million, while capital expenditure reached $126.9 million.
Looking ahead, management expects operating cash usage of $120–$150 million in 2026, alongside capital expenditure of $400–$500 million.
Meanwhile, analyst estimates suggest profitability will remain a distant goal. For Q3 FY2026, analysts expect loss per share to widen 40% YoY to $0.28. For the full FY2026, the projected loss per share is expected to widen 38.9% from the previous year to $1. They anticipate a further 12% widening in the loss per share to $1.12 in FY2027.
What Do Analysts Expect for OKLO Stock?
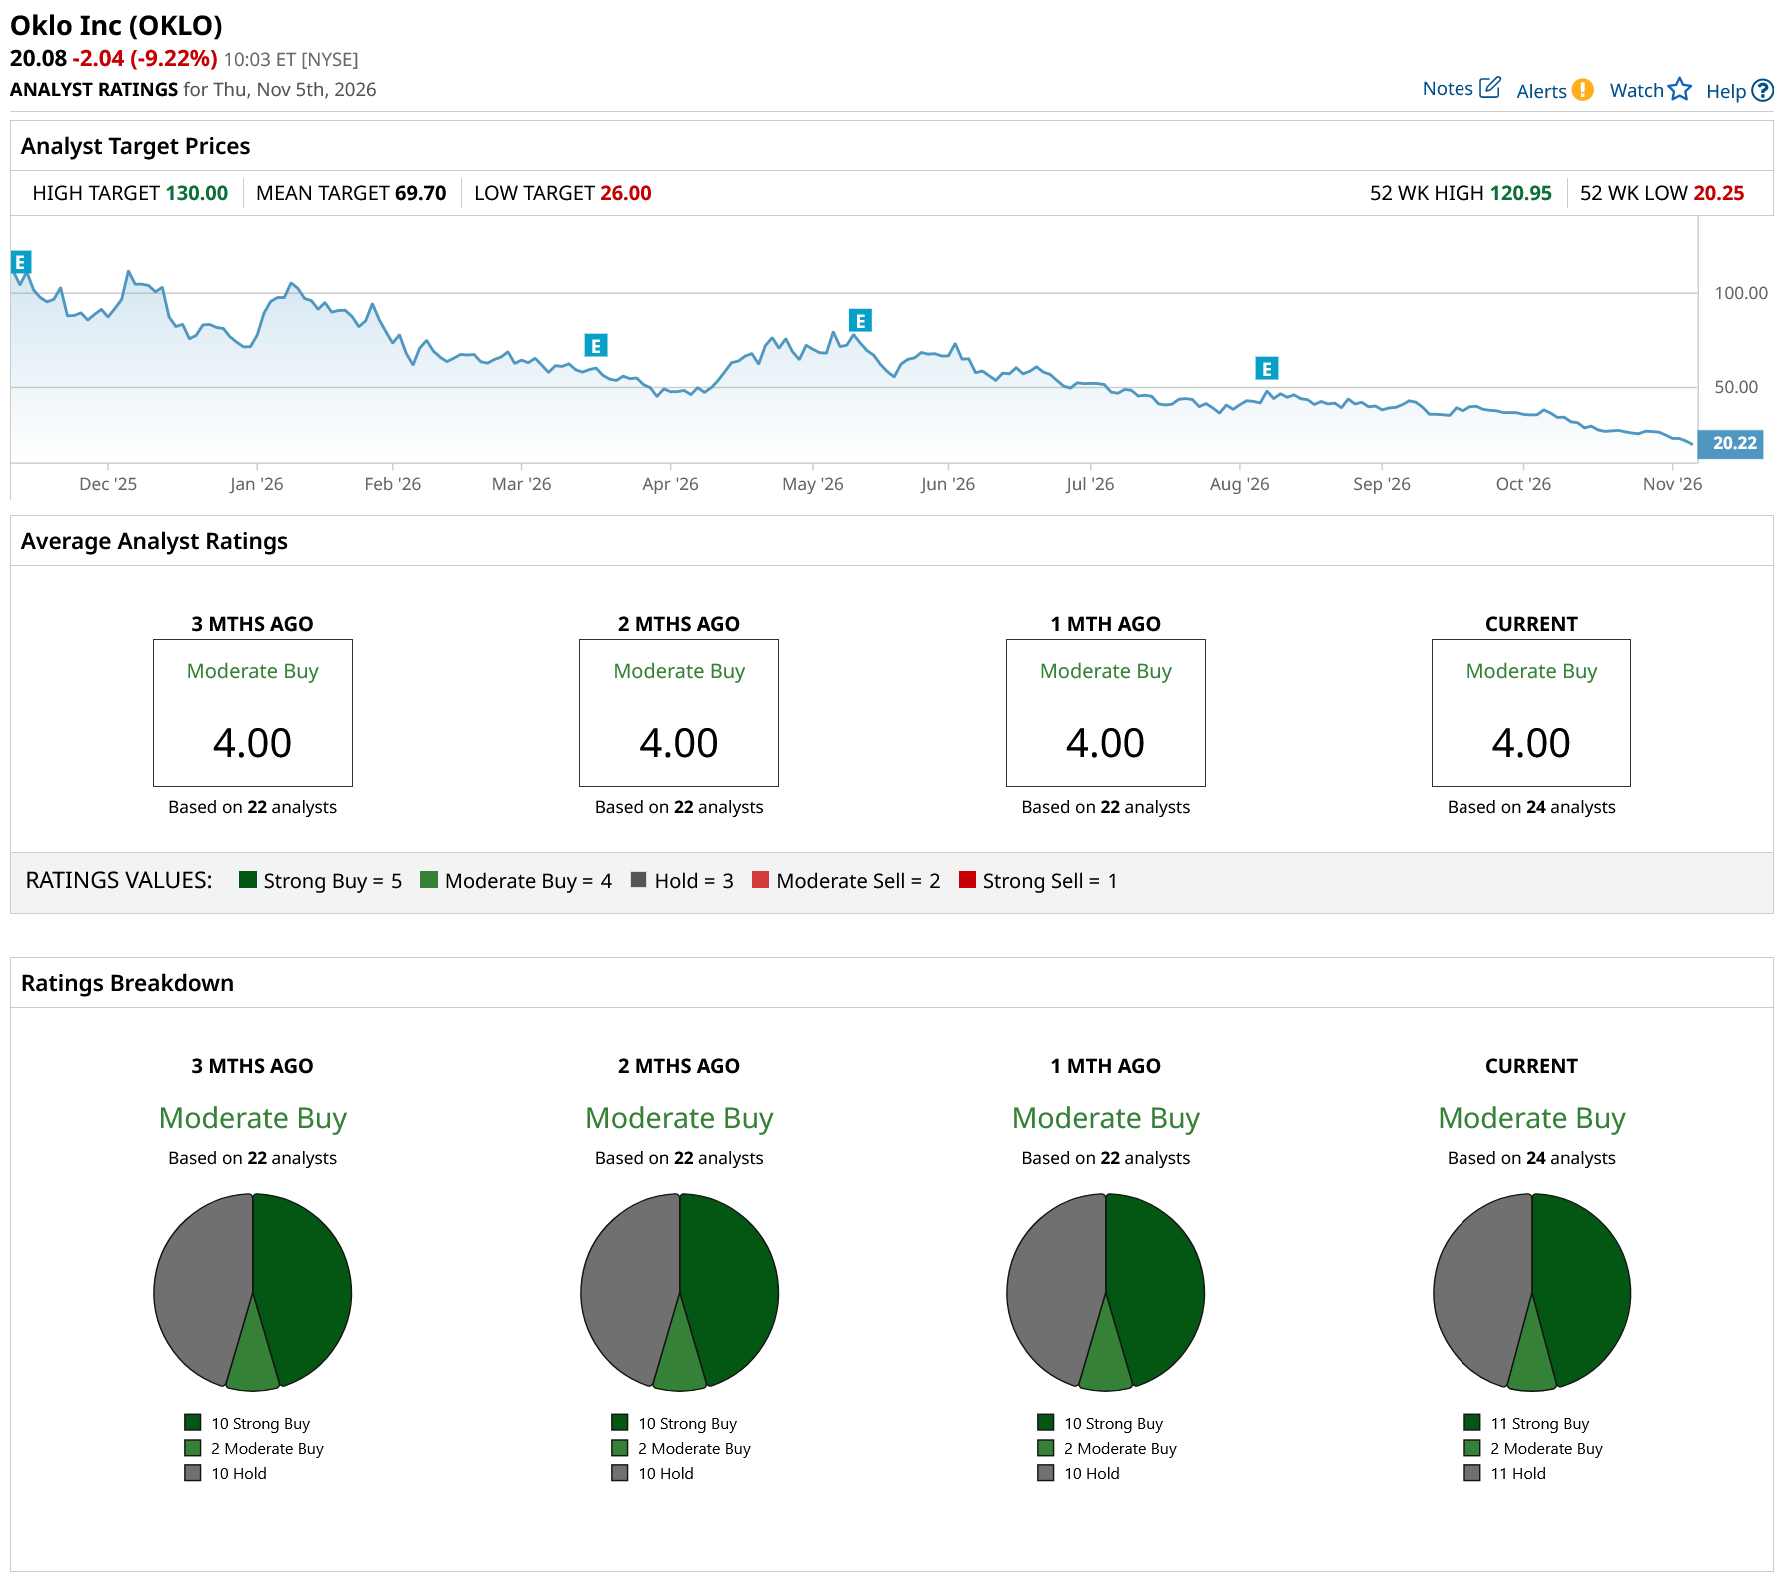
Despite the stock's steep decline, Wall Street's overall assessment of OKLO remains cautiously positive, assigning it an consensus rating of “Moderate Buy.” Among 24 analysts tracking OKLO stock, 11 recommend a “Strong Buy,” two maintain a “Moderate Buy” rating, and the remaining 11 advise to “Hold” the stock.
Even the average price target is $69.70, suggesting a potential upside of 247%. At the more optimistic end of the forecast range, the Street-high target stands at $130, indicating a potential gain of 547% from current levels.
On the date of publication, Aanchal Sugandh did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.