
Viva Energy Group (ASX:VEA) Trials Self Service, Is The Stock Cheap?
Viva Energy Group (ASX:VEA) has drawn fresh attention after management highlighted early results from its unattended self-service trial, a change in operating model that investors are watching closely.
Recent trading tells a mixed story for Viva Energy Group. The share price has slipped around 15% over the past month and is slightly higher over 90 days. However, the year to date share price return of 28.23% and 1 year total shareholder return of 55.85% point to stronger longer term momentum that recent operational updates, including the self service trial, may now be testing in the short term.
Scan other fuel and energy retailers that could be setting up for similar shifts in returns on capital with our curated list of solid balance sheet and fundamentals (12 results).
Viva Energy Group is now trading well below its recent peak, yet still carries strong 1 year and year to date gains. Do you lean into this pullback, or wait for proof that the self service shift really earns its keep before paying up again?
Most Popular Narrative: 15% Undervalued
The most followed valuation storyline on Viva Energy Group pegs fair value around A$3.16 per share, compared with the last close at A$2.68. It links that gap to execution at Geelong and the shift toward higher margin convenience and commercial earnings under a 7.53% discount rate.
Government fuel security programs, including the updated Fuel Security Services Payment, work on a longer term refining retention scheme and funded storage obligations. Together with the Geelong Energy Hub initiatives such as the hydrogen refuelling station and preparation for biogenic feedstocks, these factors are expected to influence Viva Energy Group refining economics and long run margin mix.
See why 26 investors see Viva Energy Group as 15% undervalued.
Result: Fair Value of A$3.16 (UNDERVALUED)
Still, Viva Energy Group faces two ongoing pressure points that could challenge this fair value story: the Geelong refinery is running below optimal capacity, and the company is dealing with persistent illicit tobacco headwinds in its convenience segment.
Find out about the key risks to this Viva Energy Group narrative.
Another View: Viva Energy Group On Earnings Multiples
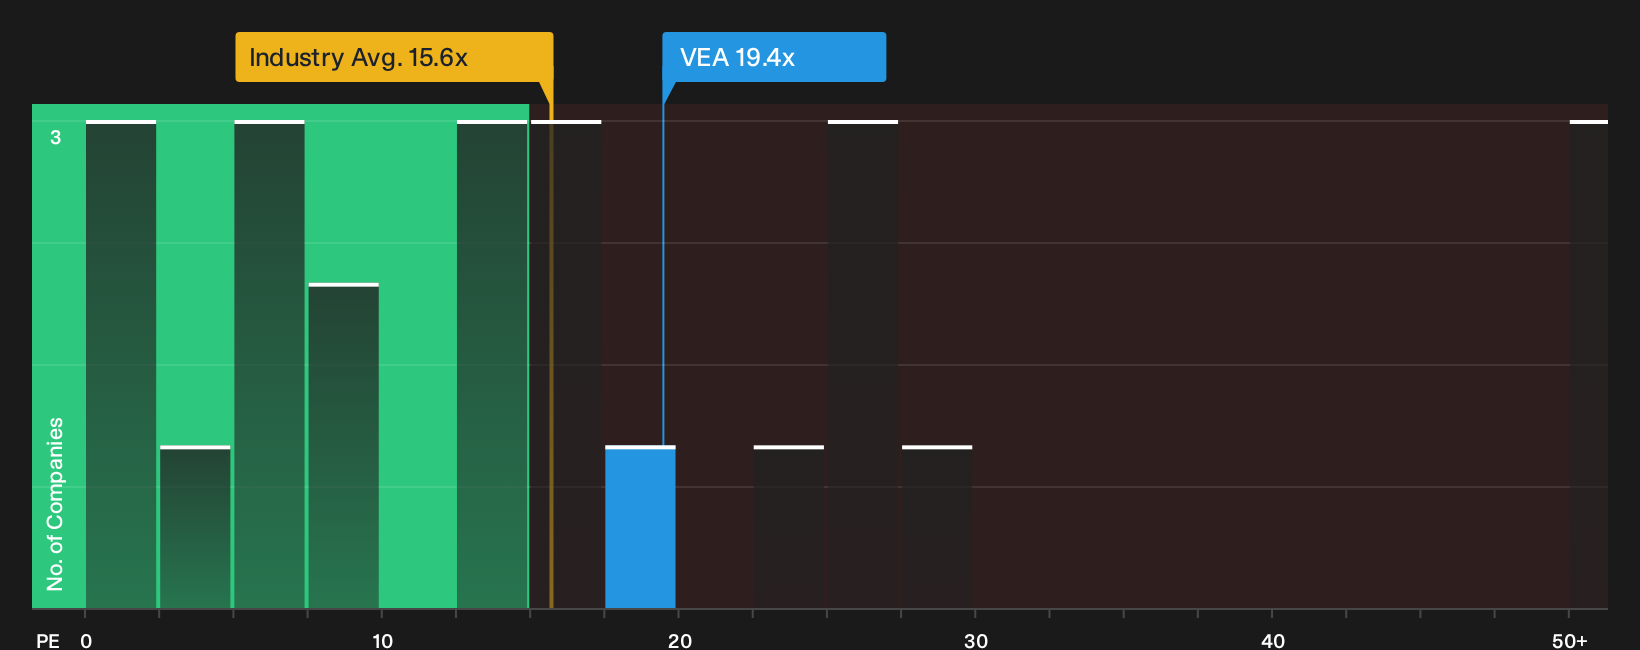
The self service trial sits against a different message from the valuation ratios. On a P/E of 19.4x, Viva Energy Group trades well above the Australian Oil and Gas industry at 15.6x and above its peer average of 14.2x. The fair ratio of 14.5x suggests less room for error if earnings disappoint.
For investors who anchor decisions around earnings multiples, that gap raises a simple question. Is Viva Energy Group priced for a smoother transition in refining and convenience than the risks around Geelong and illicit tobacco might allow, or is the market already braced for bumps ahead? See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Viva Energy Group is split, which is exactly when fresh data matters most. Move quickly and stress test the story yourself with the 1 key reward and 3 important warning signs.
Looking for more Viva Energy Group style ideas?
If you like stress testing Viva Energy Group, do not stop here. Broaden your watchlist now or risk missing other opportunities hiding in plain sight.
- Target potential mispricing by scanning companies that screen as financially strong yet unloved through our 5 high quality undervalued stocks.
- Build a steadier income stream by focusing on businesses that pay higher yields and look more resilient using the 5 dividend fortresses.
- Protect your downside first by filtering for robust balance sheets and healthier fundamentals with the curated 6 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com