
Pulse Biosciences (PLSE) Stock Still Looks Expensive Against Its Equity Base
Pulse Biosciences has seen its share price reshape the story around the company, and that kind of move naturally puts the focus on whether the current valuation still lines up with the balance sheet. With the stock now well above where it traded a few years ago, the open question is how comfortably that market value sits against its book value.
- Over the past 3 years, Pulse Biosciences has delivered a very large share price gain, which puts real weight on the question of how much underlying net assets can support the current level.
- For a business still working to convert its technology into consistent cash flows, investors are effectively leaning on the strength and flexibility of the balance sheet, since that equity cushion can influence both funding options and how much risk is priced into the stock.
- Your read on Pulse Biosciences is one view; the desks covering it have another. See what analysts think Pulse Biosciences's shares could be worth.
The issue now is whether Pulse Biosciences' recent share price is adequately backed by its book value when compared with the industry average.
If you are weighing whether Pulse Biosciences' share price is well supported by its equity base, it can help to compare it with solid balance sheet and fundamentals stocks screener (24 results).
Does Pulse Biosciences Look Pricey on Book Value?
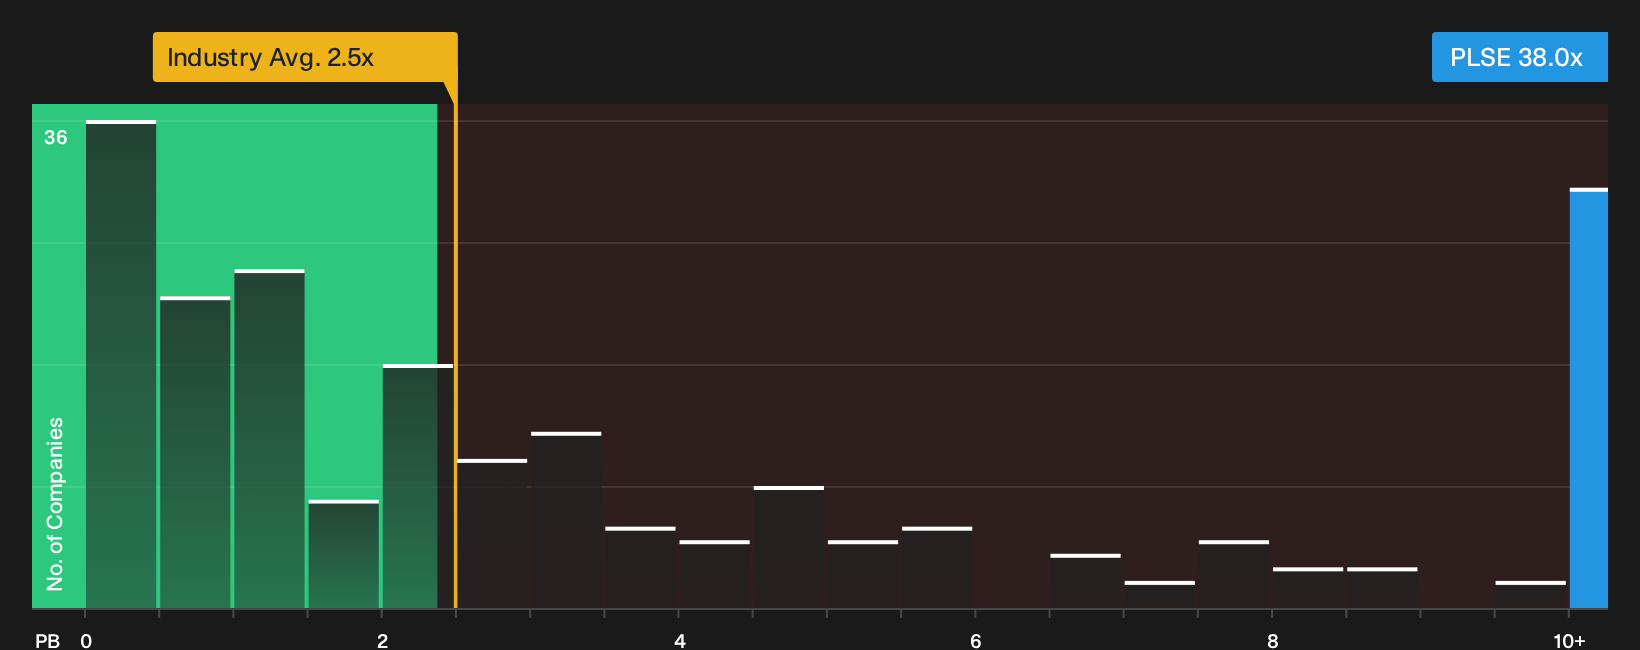
P/B tends to matter most for asset heavy or early stage healthcare businesses where hard equity is a key backstop. Pulse Biosciences trades on a P/B of about 38.0x, which is far above the Medical Equipment sector average of roughly 2.5x and also well ahead of peers around 9.3x. That gap implies the market is placing a high value on the company relative to the net assets on its balance sheet.
Such a steep premium screens as overvalued against the industry benchmark, and the valuation model flags the gap as extreme because it is heavily penalising the firm’s current losses and risk profile. For an investor, that means the present share price already bakes in strong expectations around how effectively Pulse Biosciences can turn its technology and equity base into future cash flows. Explore the numbers behind Pulse Biosciences's P/B valuation.
The Pulse Biosciences Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Pulse Biosciences valuation puzzle leaves off. They spell out which combinations of future growth, profitability and earnings outcomes would need to occur for the shares to appear meaningfully higher or lower than they do today on the screen. Each one treats fair value as a specific, testable idea about how the business might develop over time, so you can watch how that view holds up on the Community page.
One of the top community narratives on Pulse Biosciences: 15% undervalued
"Early commercial traction of the nPulse Vybrance system in benign thyroid nodule ablation, supported by growing procedure volumes and positive physician feedback..."
Discover why this Narrative puts Pulse Biosciences at 15% undervalued.
Pulse Biosciences: the share price is only one piece of the decision
Before you decide how to treat Pulse Biosciences in your portfolio, it is worth asking who is steering the business, how their pay is structured, and whether those incentives align with your capital. See who runs Pulse Biosciences and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com