
TE Connectivity Stock In Focus After Strong Results And Upbeat Outlook
- TE Connectivity reported fourth quarter 2026 sales of US$5.31b and full year revenue of US$19.89b, with net income of US$900m for the quarter and US$3.25b for the year.
- The company paired these results with guidance calling for approximately US$5.35b in first quarter 2027 sales and double digit full year revenue growth, which reflects management’s stated confidence in current demand trends.
- Next, the focus shifts to what this combination of reported earnings and guidance could mean for TE Connectivity’s broader investment narrative.
Scan beyond TE Connectivity and see which other power grid and electrification players are gaining momentum with a curated list of 40 power grid technology and infrastructure stocks in one place.
TE Connectivity Investment Narrative Recap
To own TE Connectivity, you need to be comfortable with a story built around AI driven data infrastructure, energy grid work and rising electronic content in vehicles and industrial gear. The recent earnings and guidance keep that thesis intact. The main near term swing factor still looks like how quickly AI and Energy orders convert from backlog into revenue.
The big risk remains that the recent surge in digital data networks and Energy demand cools, which could make current growth look front loaded. The legal leadership transition announced for 2027 reads as planned succession rather than a disruption, so it does not materially change either the catalyst or the key risk.
The most relevant announcement here is the updated outlook that pairs with TE Connectivity’s results. Management is calling for about US$5.35b of first quarter 2027 sales and double digit full year revenue growth, with GAAP EPS from continuing operations of roughly US$3.04 in the first quarter.
For investors, the link to potential catalysts is direct. That guidance leans on strong AI related orders, Energy demand and transportation content gains actually turning into sustained sales and earnings. Execution against that guide, while integrating acquisitions and funding programs like RAM Photonics, is where both upside and the main operational risks sit today.
TE Connectivity Consensus Assumptions In Focus
Analysts are effectively asking you to underwrite a bigger TE Connectivity by the back half of the decade, and the numbers around that story are specific. The current analyst framework starts with revenue rising at 8.9% a year over the next 3 years and profit margins edging from 16.4% today to 17.0% in that same window. That model also leans on earnings climbing from US$3.3b today to US$4.4b by 2029, which is about a US$1.1b increase in profit on the current base.
The shift in earnings power is central because it underpins the P/E multiple that analysts are using. To get to their price target, the stock would need to trade on about 20.7x those 2029 earnings, up from 19.7x today, while still below the current 30.0x P/E quoted for the broader US Electronic industry. The structure of the forecast also assumes a 2.27% yearly reduction in share count over the next 3 years, which supports earnings per share growth even before any change in the operating line.
TE Connectivity's narrative projects US$25.7b revenue and US$4.4b earnings by 2029. This setup implies 8.9% yearly revenue growth and an earnings increase of roughly US$1.1b from US$3.3b today.
What The TE Connectivity Valuation Implies For Investors
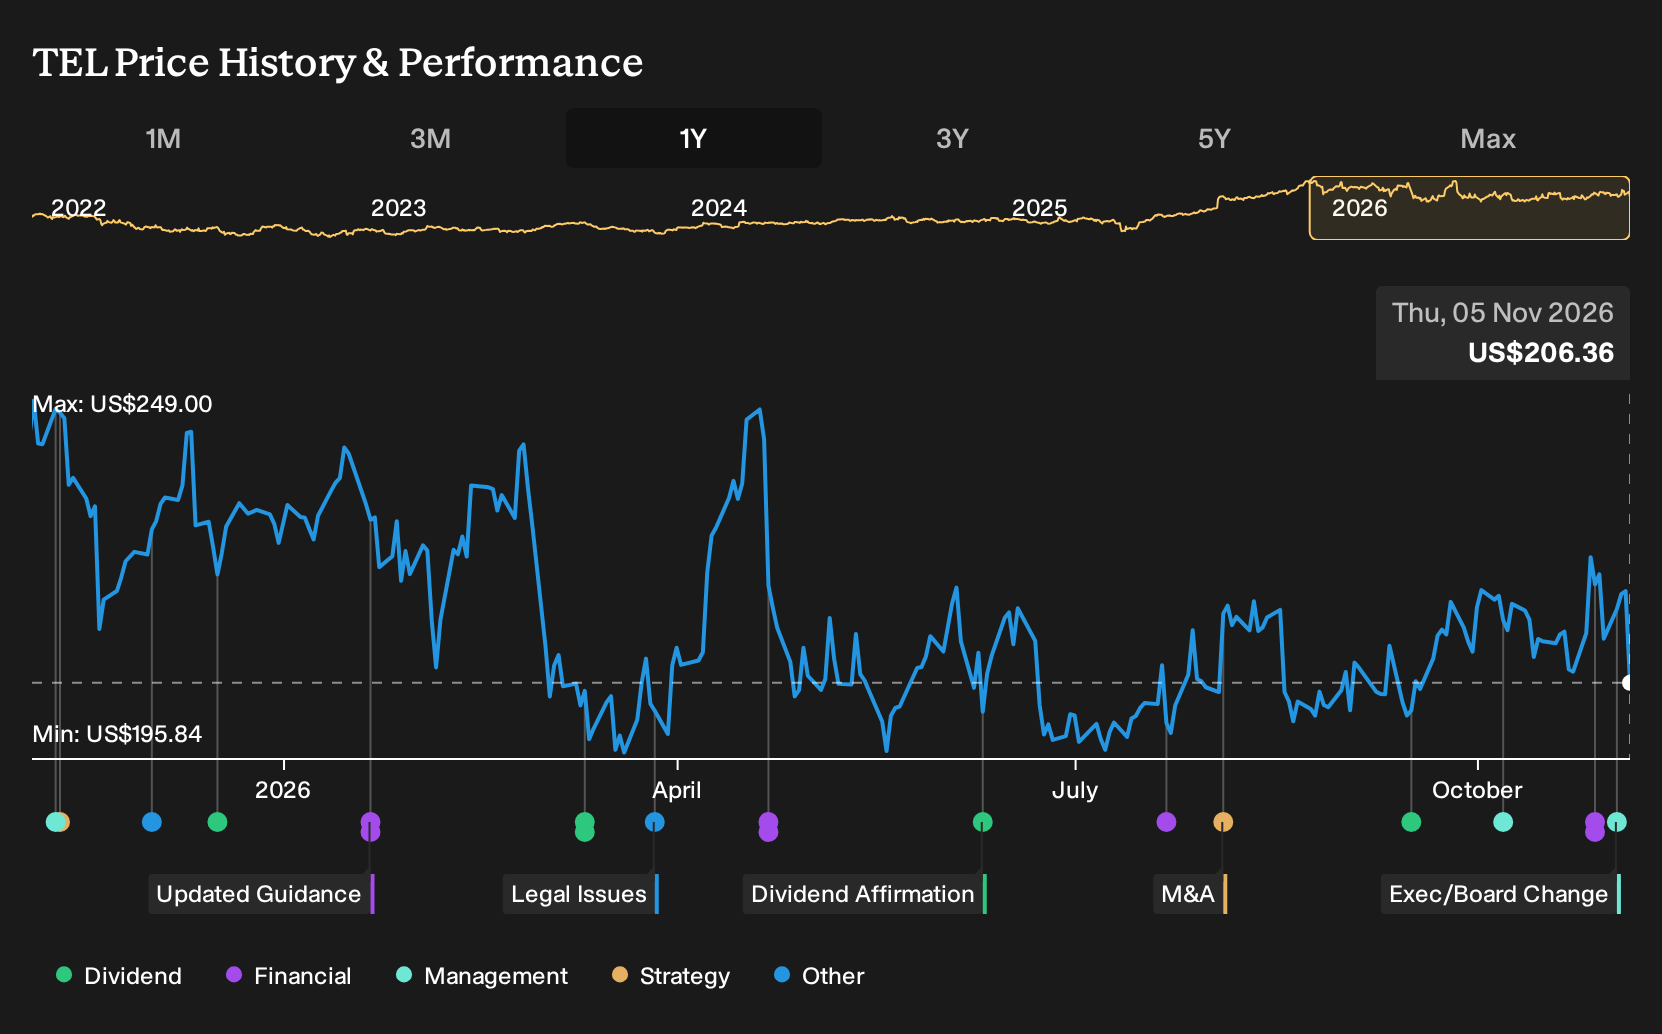
Price targets wrap all of these moving parts into a single number, but the range around that single number matters. The analyst group has landed on a consensus target of US$256.21 for TE Connectivity, with the most optimistic forecast at US$306.00 and the most cautious at US$225.00. With the shares around US$222.76 as of early November 2026, that central target sits 13.1% higher, which gives you a sense of how much of the earnings and margin story is already embedded in expectations.
The homework here is straightforward but important. To line up with the analyst view, you would need to believe that by 2029 TE Connectivity can reach roughly US$25.7b in annual revenue, earn about US$4.4b in profit, and support a P/E of 20.7x on those earnings using a 9.6% discount rate as a hurdle in your own models. The key question for any prospective shareholder is whether those revenue, margin and multiple assumptions fit with your own reading of TE Connectivity's AI, energy and transportation exposure, or whether your bar is set higher or lower than the current consensus.
Discover why TE Connectivity's fair value indicates a 24% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
The lowest analysts focus on a different concern for TE Connectivity. They worry that heavy AI and energy spending today meets softer AI demand later, which could leave new capacity underused. Their October 2029 view sat closer to US$24.6b revenue and US$4.2b earnings. Those forecasts, set before this leadership change and guidance, may now shift meaningfully.
Explore 4 other TE Connectivity fair value estimates, including one that suggests it could be worth just $225.00.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your TE Connectivity research is our analysis highlighting 6 key rewards that could impact your investment decision.
- See our latest analysis for TE Connectivity. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TE Connectivity's overall financial health at a glance.
Looking For More Investment Ideas Beyond TE Connectivity?
If the TE Connectivity story has sharpened your sense of what you want in a business, use that filter across a wider universe. The Simply Wall St Screener lets you move from narrative to numbers and quickly surface other opportunities that better match your risk tolerance, time horizon, and income needs.
- If you prefer steadier profiles over drama and surprises, with an emphasis on balance sheet strength and durable fundamentals, then start with a list of solid balance sheet and fundamentals (24 results) and see which businesses clear your quality bar.
- If you are hunting for potential mispricings where quality and valuation meet, use the 42 high quality undervalued stocks to surface companies that analysts and models flag as priced below their estimated worth.
- If you want income to do more of the work for you over time, scan a curated set of 6 dividend fortresses and focus on businesses where cash returns to shareholders are front and center in the thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com