
Is Centuri Holdings (CTRI) A Bargain As Earnings Rebound?
Centuri Holdings (CTRI) just posted third quarter and nine month results that showed higher revenue, a move back into net profitability, and meaningfully higher earnings per share compared with the same periods last year.
Despite the stronger third quarter, Centuri Holdings’ share price has come under pressure, with the stock down 9.2% on a 1 day share price return and 27.77% on a year to date share price return. The 1 year total shareholder return has fallen 12.69%, pointing to fading momentum as investors reassess the balance between improving profitability and perceived risks around the story at the current US$18.65 level.
Compare Centuri Holdings’ earnings rebound with utility peers by scanning curated 40 power grid technology and infrastructure stocks that could be setting up for their own turning points after recent pressure.
Centuri Holdings now trades at a steep discount to both analyst targets and some intrinsic value estimates after this rebound in earnings. Is that gap a genuine opportunity, or a fair reflection of the risks investors see?
Most Popular Narrative: 35% Undervalued
Centuri Holdings is trading at $18.65, while the most widely followed narrative framework points to a fair value near $28.50 based on its cash flow and earnings potential under a 10.08% discount rate.
Record backlog of approximately $5.9 billion and a robust $13 billion opportunity pipeline, including over 600 strategic bids, supports sustained revenue growth by converting awarded work into a higher, more stable top line.
See why 4 investors see Centuri Holdings as 35% undervalued.
Result: Fair Value of $28.50 (UNDERVALUED)
Still, the Centuri Holdings story carries real tension, with ongoing margin pressure and analyst concern about valuation multiples. Both are capable of undermining this undervalued narrative.
Find out about the key risks to this Centuri Holdings narrative.
Another View: Centuri Holdings Through The P/E Lens
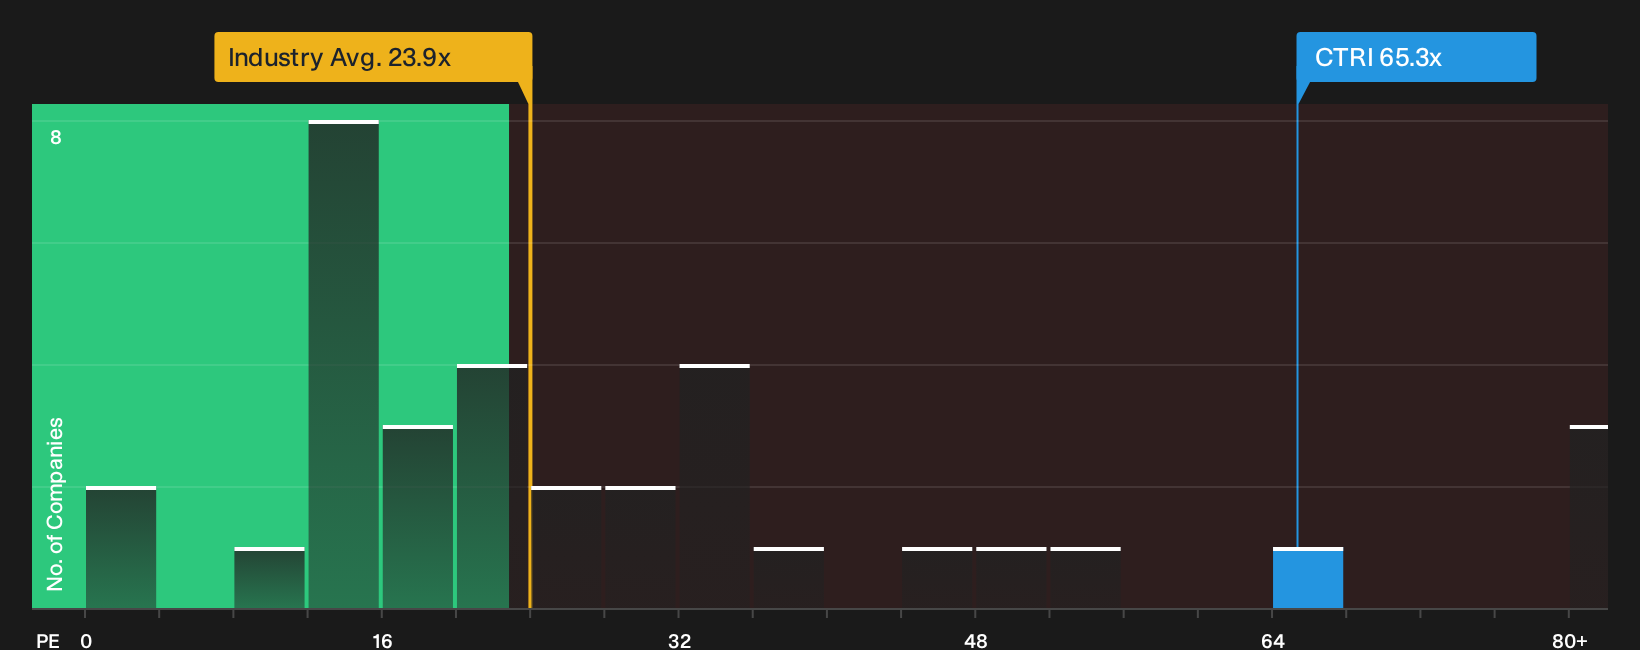
The cash flow fair value suggests Centuri Holdings looks cheap, yet the earnings multiple tells a different story. At a P/E of 65.3x, the stock trades at more than double the US Construction industry on 23.5x and well above its own fair ratio of 40.3x. That gap points to meaningful valuation risk if sentiment shifts, so which signal should you put more weight on?
To pressure test this earnings based view against your own expectations for Centuri Holdings, it helps to see how the numbers stack up in detail, especially versus peers and that fair ratio the market could move towards, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Centuri Holdings so far. This is exactly why you should move quickly, test the underlying data yourself, and weigh both the 1 or more risks and 1 or more rewards identified in our breakdown through 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Centuri Holdings?
If you only stop at Centuri Holdings, you risk missing other setups where price, quality, and risk come together in a way that fits your plan.
- Target resilient balance sheets and consistent fundamentals through a curated list of solid balance sheet and fundamentals (24 results) that filters for financial strength first.
- Zero in on quality at a discount with a focused 42 high quality undervalued stocks that highlights companies where fundamentals and price may be out of sync.
- Build a watchlist of potential outperformers before the crowd catches on by scanning a 21 high quality undiscovered gems that narrows in on under-the-radar quality.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com