
How Stronger Quarterly Earnings At CRA International (CRAI) Has Changed Its Investment Story
- CRA International reported third quarter 2026 results with sales of US$214.92 million and net income of US$13.91 million, with both figures above the levels reported a year earlier.
- The nine month figures show higher sales of US$626.71 million but lower net income of US$38.55 million compared with the prior period, which highlights pressure on profitability even as the business handles more client work.
- The focus now turns to how CRA International's higher quarterly earnings per share might influence its existing investment narrative for investors.
CRA International Investment Narrative Recap
For CRA International, the core belief as a shareholder is that complex regulation, M&A and litigation keep feeding high value consulting work, and that specialist talent turns that demand into consistent earnings. The latest quarter supports that story, with higher sales and higher quarterly earnings per share despite a softer nine month profit line.
The key short term swing factor is whether utilization and pricing stay firm enough to offset a heavier cost base and existing debt obligations. Nine month net income sitting below the prior period keeps pressure on margins in focus. That gap is important, although this single update does not radically change the thesis.
Among recent developments, the most relevant item is the detailed earnings release itself for the quarter and nine months to October 3, 2026. It shows CRA International producing US$214.92 million of quarterly sales and US$13.91 million of net income, with EPS from continuing operations higher than a year earlier on both a basic and diluted basis.
For catalysts, this report matters because it connects the earlier growth investments in experts and international build out with current profitability. It also flags that nine month net income of US$38.55 million trails the prior year. That mix keeps execution risk around talent spending and debt coverage front and center for anyone tracking CRA International through the next few quarters.
Analysts see CRA International reaching US$902.9 million in revenue and US$72.1 million in earnings by 2029, which implies revenue growing at 4.3% a year and an earnings increase of about US$22.9 million from the current US$49.2 million level.
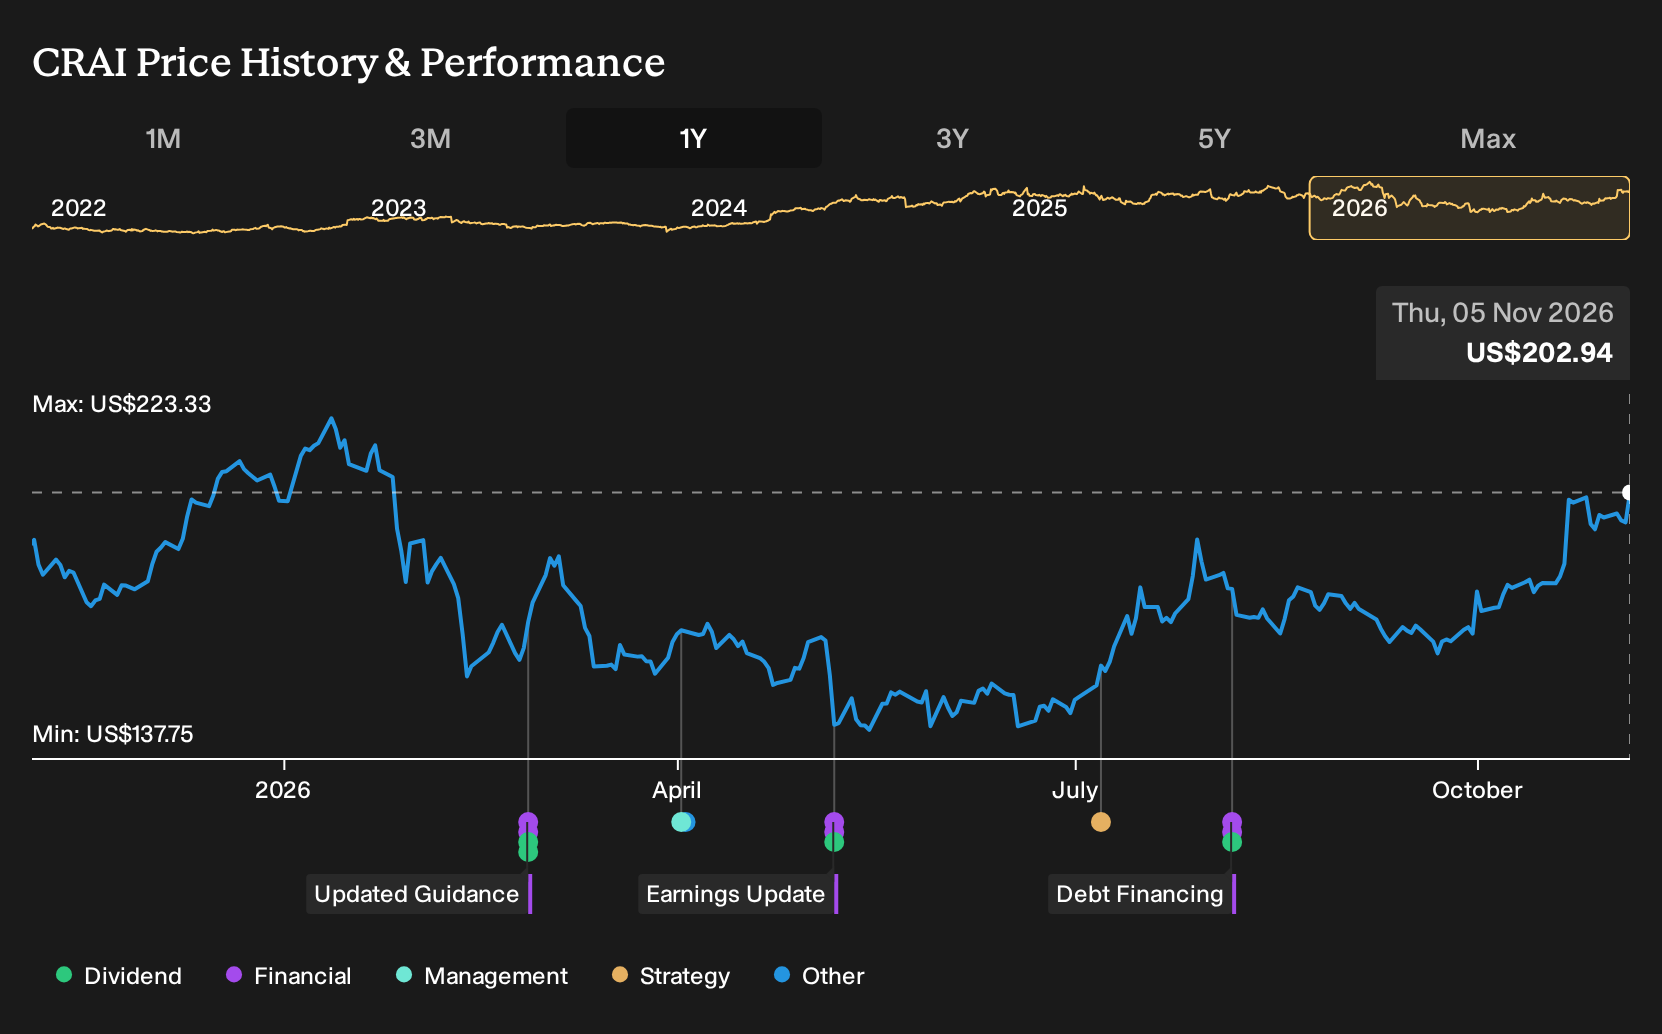
Discover how CRA International's fair value indicates a 23% potential upside to its current price, which could narrow quickly as sentiment catches up.
Exploring Other Perspectives
Two fair value submissions from the Simply Wall St Community bracket CRA International between roughly US$250 and US$348 per share, a wide spread for such a small sample. That gap sits beside live risks around M&A volumes, enforcement activity and debt usage, which can all swing future earnings power. Explore the full set of community views before anchoring on any single number.
Explore another CRA International fair value estimate, including one that suggests as much as 71% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CRA International research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CRA International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CRA International's overall financial health at a glance.
Looking For More Ideas Beyond CRA International?
If the CRA International story has sharpened your sense for earnings quality and balance sheet strength, it can be useful to line it up next to other listed businesses. The Simply Wall St screener helps you filter the market so you can focus on a shortlist that fits your own risk tolerance and return objectives.
- If capital preservation matters most to you, start with sturdier profiles through a 32 resilient stocks with low risk scores that filters for resilience over excitement.
- If you prefer strong finances as your foundation, sort companies by balance sheet strength using a list of solid balance sheet and fundamentals (24 results) that highlights robust fundamentals and cleaner debt positions.
- If value is your north star, focus on pricing versus quality through a 42 high quality undervalued stocks that surfaces candidates where fundamentals and market expectations diverge.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com