
Taiyo Holdings And 2 More Japanese Quality Stocks
Japan’s stock market just felt the shock from a global sell off in AI and chip companies, as the Nikkei 225 slid alongside the worst US chip drop since 2020. When big funds rush to exit crowded trades, quieter Japanese small caps with solid balance sheets can attract fresh attention. This article highlights three underfollowed quality stocks that screen well on fundamentals and remain off most institutional radars.
The three Japanese small caps highlighted below are only a sample. The full high quality screen surfaced 71 more companies with equally compelling stories that are not covered in this article.
To go deeper, head straight into the High-Quality Undiscovered Gems screener and use it to identify, filter, and analyze the high conviction ideas that best match your own criteria.
Taiyo Holdings (TSE:4626)
Overview: Taiyo Holdings supplies high performance electronics materials for printed circuit boards and advanced packaging, while also operating smaller pharmaceutical and chemical businesses.
Operations: The group generates most of its revenue from Electronics at ¥101,102 million, with Medical and Pharmaceuticals at ¥36,274 million and Others at ¥6,767 million.
Market Cap: ¥510.6 billion
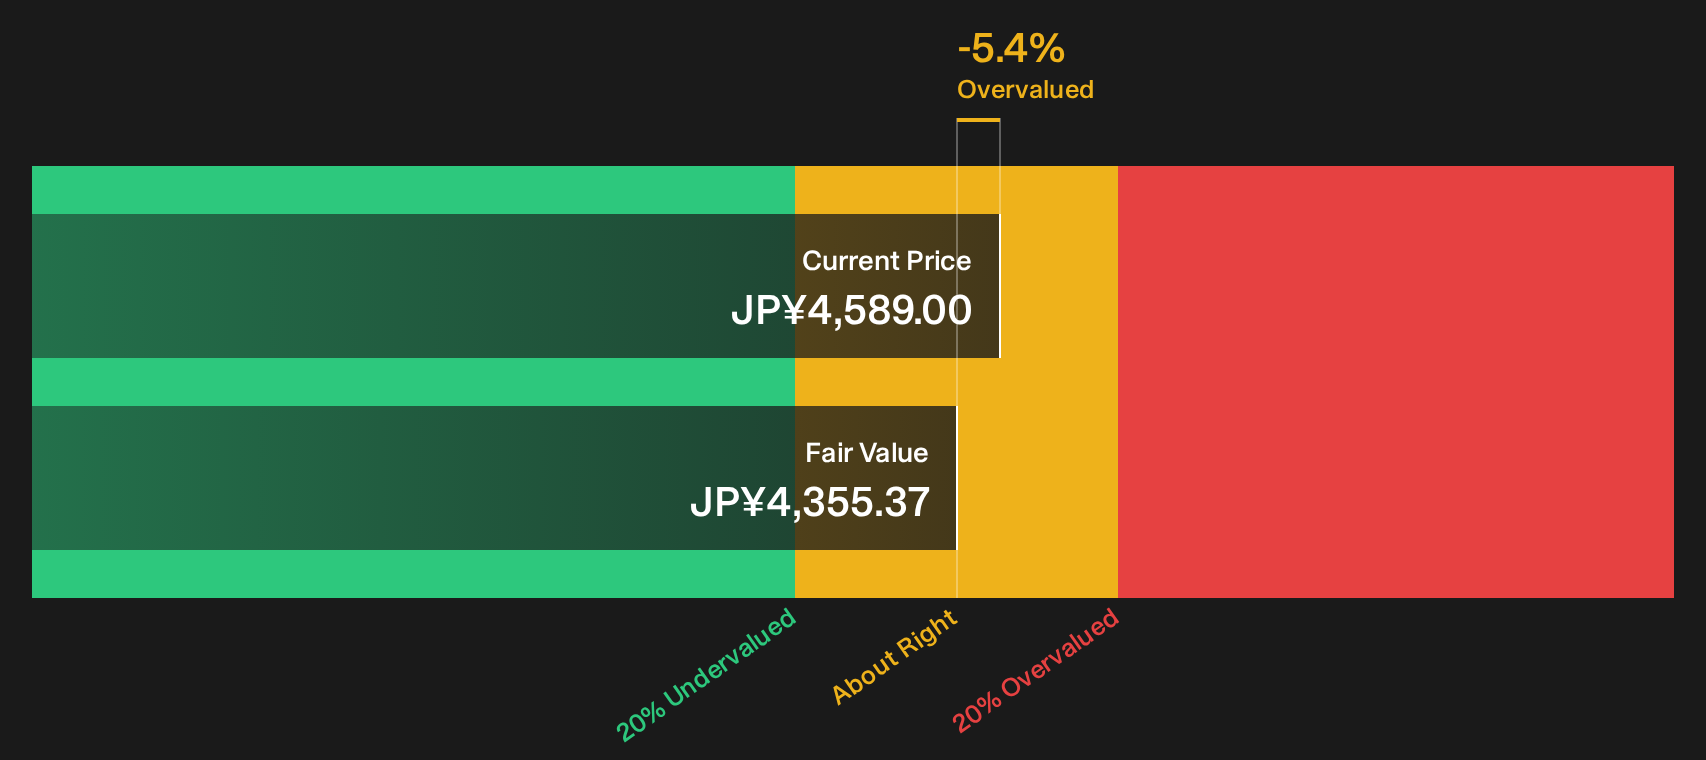
Taiyo Holdings fits into the High-Quality Undiscovered Gems theme, combining 148.7% earnings growth with a 21.3% ROE and 18.7% net margins from its electronics materials franchise. The stock still trades at about 19x P/E and has underperformed the Chemicals sector. Any potential upside or strain will depend on how a single pressure point affects that margin profile.
That single pressure point is exactly what the DCF valuation analysis for Taiyo Holdings unpacks, helping you see whether Taiyo Holdings’ margin profile is masking deeper upside or fragility.
SEIKOH GIKEN (TSE:6834)
Overview: SEIKOH GIKEN manufactures precision optical components and equipment for fiber optic networks, telecom infrastructure, and related high accuracy molding applications.
Operations: SEIKOH GIKEN generates about ¥23,023 million from optical products and ¥10,236 million from precision equipment, with a small unallocated adjustment.
Market Cap: ¥186.6 billion
SEIKOH GIKEN plugs directly into the High-Quality Undiscovered Gems theme through its fiber optic connectors, ferrules, and other precision parts that feed telecom upgrades. Q1 FY2027 delivered ¥8,608 million in sales and ¥2,207 million in net income, indicating that the core business is earning solid returns while still under most institutional radars, depending on how one unseen pressure on fiber related demand develops.
If that hidden demand swing matters to you, review the 2 key rewards and 1 important major warning sign to examine how SEIKOH GIKEN’s potential upside could diverge from its risk profile.

PAL GROUP Holdings (TSE:2726)
Overview: PAL GROUP Holdings is a Japan based apparel retailer that designs, manufactures, and sells clothing and daily goods through multiple brands.
Operations: PAL GROUP Holdings generates about ¥148,743 million from Clothing, ¥90,639 million from Miscellaneous Goods, and ¥373 million from Others, almost entirely in Japan.
Market Cap: ¥248.8 billion
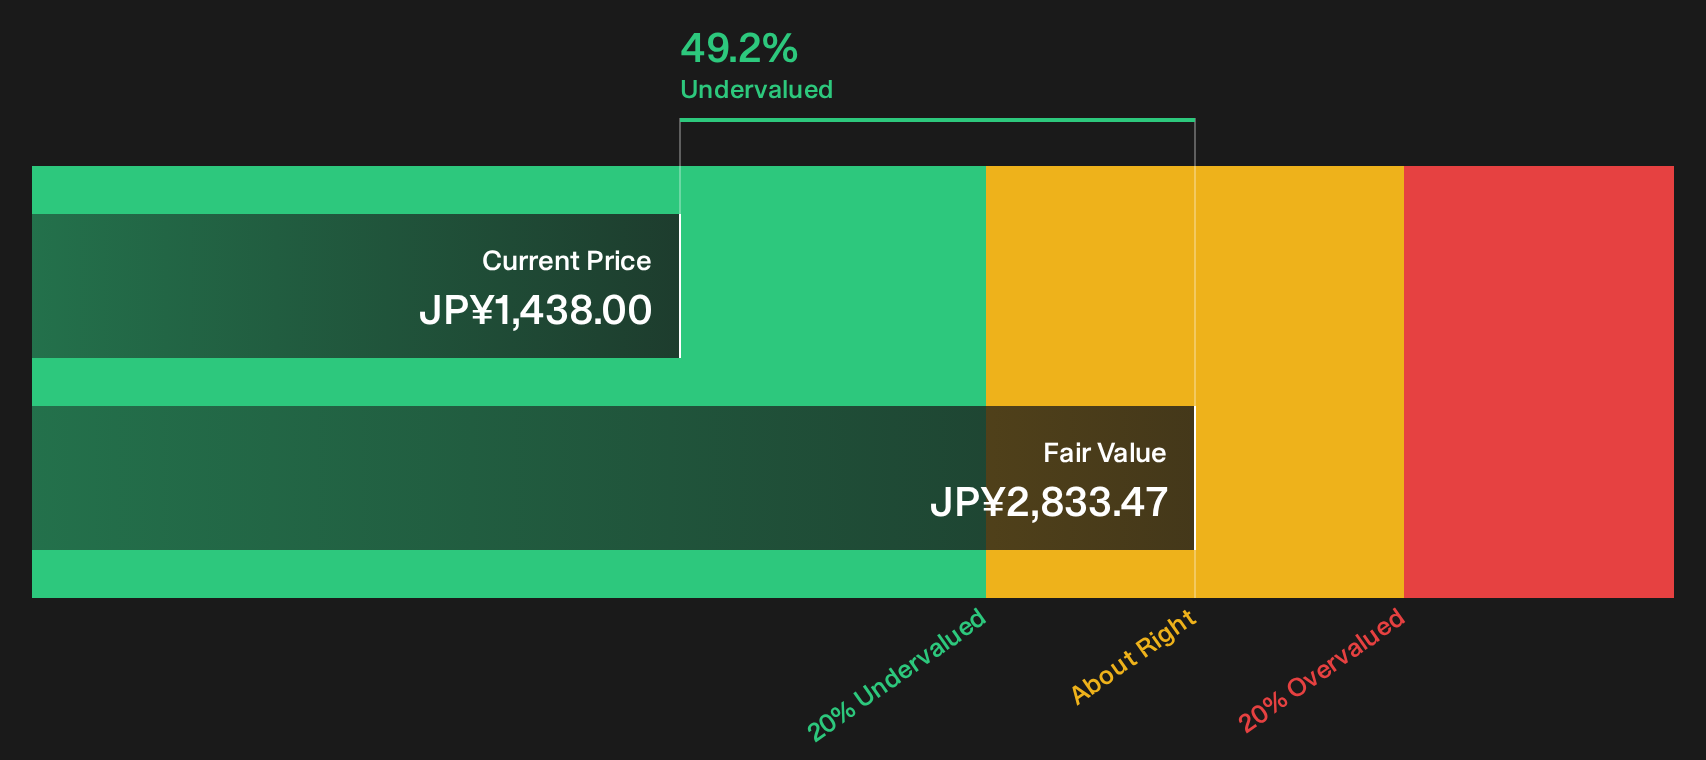
PAL GROUP Holdings fits the High-Quality Undiscovered Gems theme through its profitable apparel brands, with ROE around 20.6% and a mid teens P/E that underprices cash flow estimates. At the same time, a growing dividend that leans on weaker free cash flow coverage leaves everything hinging on how pressure on future cash generation plays out.
With that cash flow tension in mind, review the 4 key rewards and 1 important warning sign to see how PAL GROUP Holdings’ payout, earnings power, and valuation might be quietly decoupling.
Seeking Alternatives Before The Crowd
Fresh breakouts, fading laggards, and under the radar momentum do not wait. Screens age fast as prices move, expectations shift, and stories get repriced.
- Spot income workhorses that might keep paying while others stall, starting with the 36 dividend fortresses built to surface cash return specialists before yields get compressed.
- Track AI infrastructure momentum from current levels by scanning the curated 52 AI infrastructure stocks focused on real businesses behind the compute build out.
- Hunt for resilient operators that may hold up when sentiment drops by running the hand picked 19 resilient stocks with low risk scores and pressure testing your watchlist against sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com