
Assured Guaranty (AGO) Stock Could Be A Bargain As 49% Gain Draws Focus
Assured Guaranty has delivered a 49.0% share price gain over the past 5 years, which puts a spotlight on a simple but important issue for anyone looking at the stock today. Is the current US$73.45 price adequately grounded in what the insurer actually earns?
- A 49.0% return over 5 years means long term holders have already seen a substantial payoff, so any new position now leans heavily on what the business can keep generating in earnings.
- The group’s model of insuring financial obligations and managing related investment risk can shape how consistently profits convert into cash and how much capital it needs to hold, which matters directly for how investors judge the earnings that support the valuation.
- There is a second opinion on Assured Guaranty worth weighing. See what analysts think Assured Guaranty's shares could be worth.
The issue now is whether Assured Guaranty’s earnings are strong and resilient enough to make today’s share price look well supported.
If you are weighing Assured Guaranty on its earnings, it can help to compare it with a focused set of resilient candidates using our 29 resilient stocks with low risk scores.
Does Assured Guaranty Look Undervalued on Earnings?
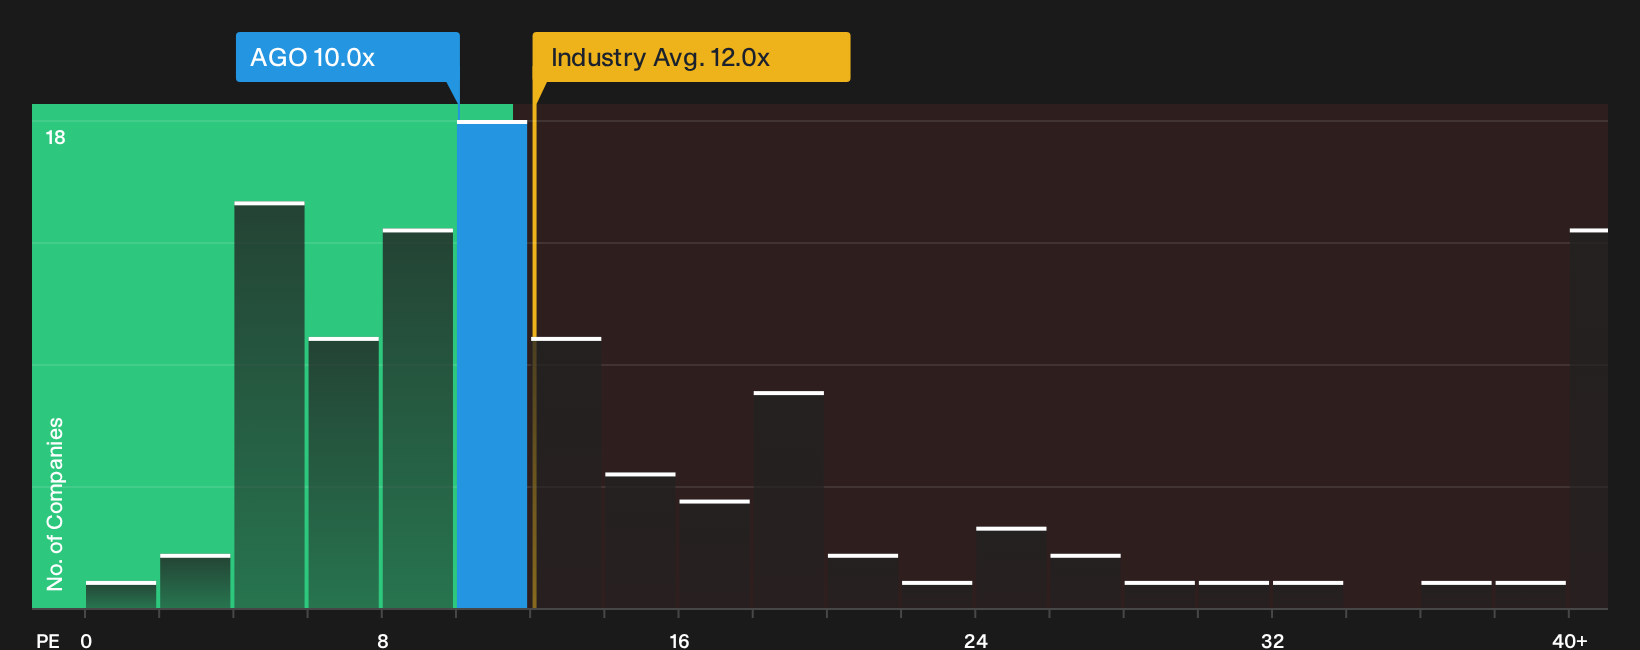
The P/E ratio suits Assured Guaranty because earnings remain the main anchor for how investors judge an insurer’s value. At a P/E of 10.0x, the stock trades slightly above the peer group average of 9.3x, yet below the wider Insurance sector on 12.0x. That places the shares in a middle band where the market is neither assigning a very low multiple nor paying up in line with the broader industry.
The fair P/E that reflects Assured Guaranty’s own economics comes out higher than where the stock trades, so the current 10.0x implies a valuation that screens as undervalued on this framework. For anyone weighing the shares today, that gap suggests the market price does not fully reflect the earnings power implied by the model, although it still needs to be weighed against your view on the quality and stability of those profits. Explore the numbers behind Assured Guaranty's P/E valuation.
The Assured Guaranty Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take that P/E puzzle around Assured Guaranty and turn it into explicit scenarios for what would need to happen to earnings, growth and profitability for the current share price to look either too low or too high. Each scenario anchors its number to a clear view on how Assured Guaranty's growth, margins and risk profile might evolve, which you can then revisit as fresh information comes through.
One of the top community narratives on Assured Guaranty: 19% undervalued
"The current valuation is described as implying that the market is discounting Assured Guaranty’s record adjusted book value per share, its long-run alternative investment returns and its shift toward repeatable, higher velocity business..."
Discover why this Narrative puts Assured Guaranty at 19% undervalued.
One more side of Assured Guaranty worth checking before you decide
Assured Guaranty’s valuation story is only part of the picture. Recent research has also flagged specific risk checks that deserve a closer look on their own. Take a closer look at 1 warning sign before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com