
Earnings Update Might Change The Case For Investing In Bank of China (SEHK:3988)
- Bank of China reported third quarter 2026 results with net interest income of CNY 122,873 million and net income of CNY 63,888 million, and nine month basic earnings per share from continuing operations of CNY 0.55, matching the prior year.
- The combination of higher net interest income and slightly stronger quarterly earnings per share points to resilient core banking activity and indicates how Bank of China is managing its lending and deposit book through current operating pressures.
- We will now examine how Bank of China's third quarter net interest income figures influence the existing investment narrative for the bank.
Scan how Bank of China’s latest interest income trends compare with peers by reviewing our curated list of list of solid balance sheet and fundamentals (192 results) for ideas beyond this single stock.
Bank of China Investment Narrative Recap
To own Bank of China you need to be comfortable with a large state linked lender that leans on net interest income, fee based services and a big overseas footprint. The fresh Q3 numbers keep that broad story intact. Higher quarterly net interest income and net profit support the idea that core banking activity is holding up under current margin pressure.
The key short term catalyst still looks like how quickly management can re mix assets toward higher yielding, better quality books such as technology and green finance, while keeping reported non performing loans contained. The biggest near term risk remains sector wide credit quality concerns, especially in Chinese real estate, rather than anything new in this quarter.
The fixed income offering of US$250 million in floating rate notes due 2029 is worth your attention alongside the earnings release. It sits within the broader funding stack and may slightly influence the bank’s interest expense profile as policy rates and reference benchmarks move from current levels.
For an investor tracking catalysts, this kind of issuance matters because it interacts with the net interest margin risk already on the table. A more complex external backdrop and the large overseas business mean funding choices, currency mix and regulatory costs all feed into how much of Bank of China’s higher net interest income actually drops through to the bottom line.
Bank of China's narrative projects CN¥853.4 billion revenue and CN¥278.0 billion earnings by 2029. This assumes 14.1% yearly revenue growth and an earnings increase of about CN¥41.4 billion from CN¥236.6 billion today.
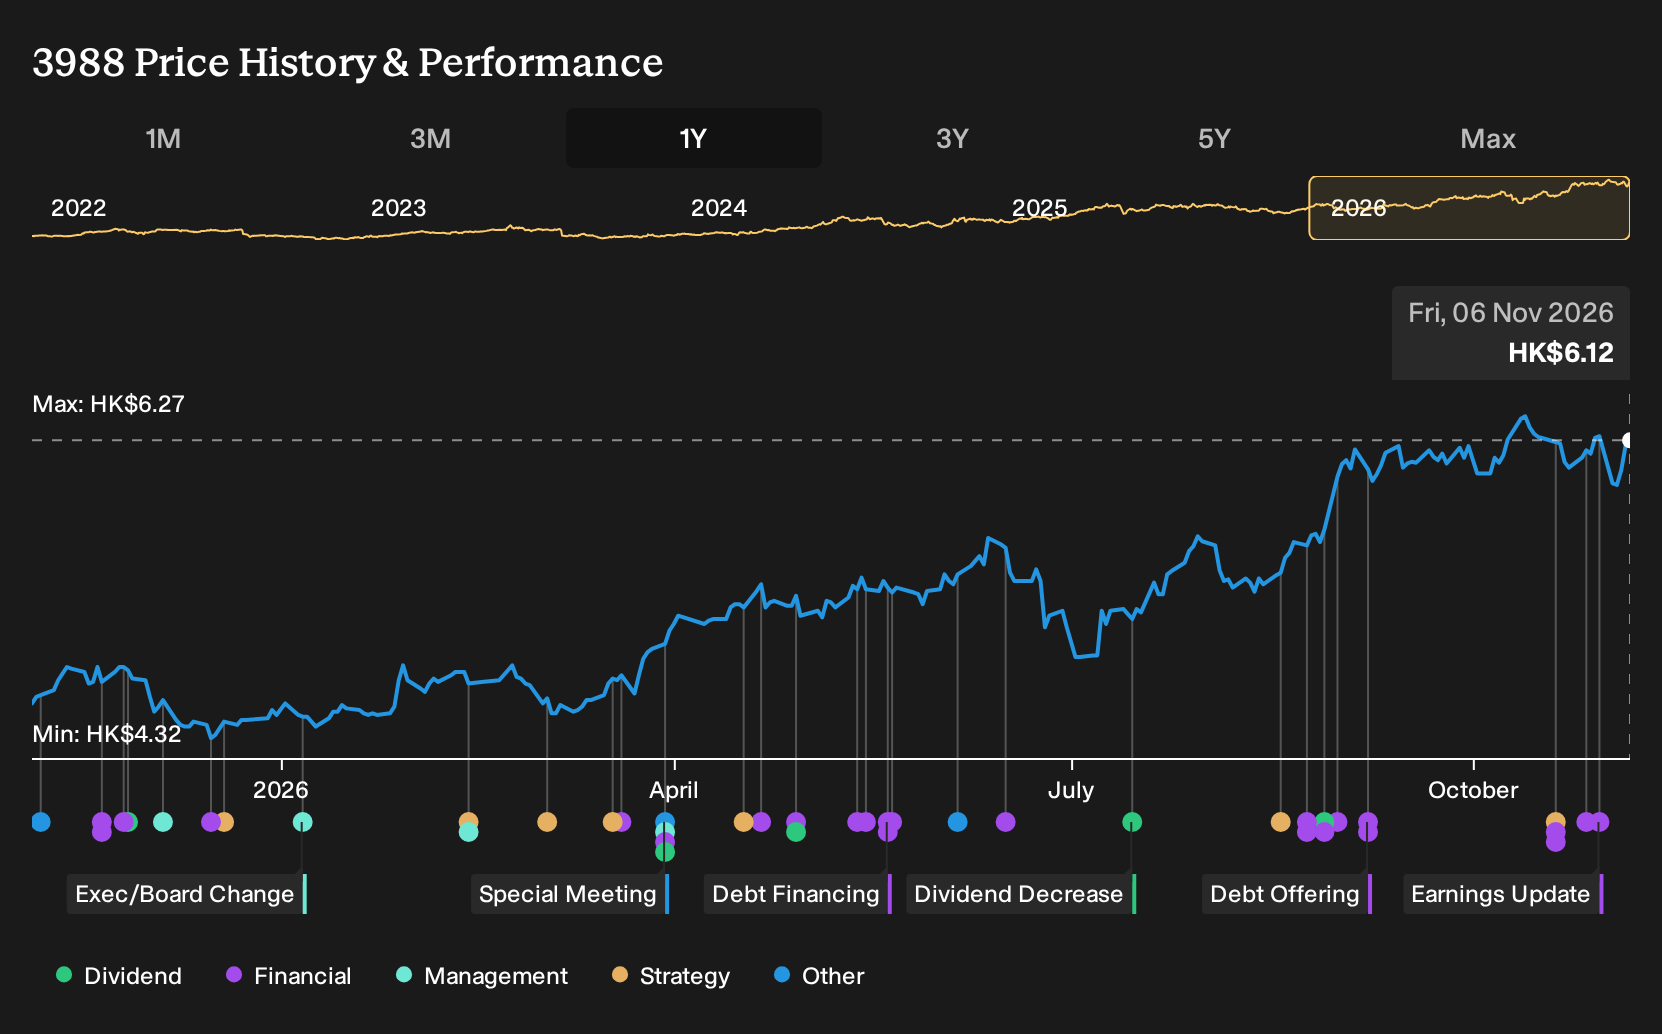
Uncover why Bank of China's fair value indicates a 6% potential upside to its current price. This may represent a discount that could close sooner than many investors expect.
Exploring Other Perspectives
One alternate view on Bank of China leans heavily on credit risk. The most cautious analysts were working off revenue of about CN¥818.3 billion and earnings of roughly CN¥278.7 billion by 2029, yet paired that with a much lower 6.5x P/E. Those forecasts came before this Q3 report, so opinions may change.
Explore 5 other Bank of China fair value estimates, including one that suggests as much as 15% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bank of China research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Bank of China. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bank of China's overall financial health at a glance.
Looking For More Investment Ideas Beyond Bank of China?
Once you have a view on Bank of China, it can help to cross check that thesis against other listed businesses with different balance sheets, payout policies and risk profiles. A quick sweep through the Simply Wall St Screener lets you line up stocks by the factors that matter most to you and spot opportunities you might otherwise miss.
- If you care most about stability, start with companies that pair modest valuations with stronger financial footing through our 212 resilient stocks with low risk scores.
- If dependable income is a priority, focus on businesses offering higher yields with an emphasis on sustainability by using the 232 dividend fortresses.
- If you want potential mispricing ideas, look across companies that combine quality fundamentals with lower implied valuations via the 227 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com